How to Form a US LLC from Comoros
Can you form a US LLC from Comoros? In general, a Comorian citizen or resident can own a US LLC remotely without US citizenship, a visa, or an SSN. The harder questions come after filing: whether a US bank or payment service will accept your real residence and business, which US tax forms apply, and what Comoros expects from a resident earning through a foreign company. This practical guide explains each step, the costs, the IRS process, and the local questions to ask before you move money.
Quick Answer: How to Form a US LLC from Comoros
To form a US LLC from Comoros, decide what business problem the US entity solves, choose a state, appoint a registered agent there, file the state’s formation document, sign an operating agreement, apply for an EIN with the IRS, and then approach banks and payment providers that confirm they support your residence and activity. Put state renewals and tax review dates on a calendar as soon as the state approves the company.
You usually do not need US citizenship, a US visa, a US-based co-owner, or a Social Security number simply to form an LLC. These points do not guarantee a bank account, make your business tax-free, or give you a right to work in the United States. If you live and perform services in Comoros, Comorian rules can remain relevant even if your clients, company registration, or bank account are in the US.
For a remote service business with no US office, staff, or inventory, Wyoming and New Mexico are common states to compare. Delaware may suit a planned US investment round where counsel or investors ask for it. If you have an actual US operating footprint, investigate that state first: forming elsewhere may create a second registration rather than reduce compliance.
Table of Contents
- Why Comorian founders consider a US LLC
- Is a US LLC right for you?
- How an LLC works
- Foreign ownership, visas and addresses
- Choose the state
- Formation and ongoing costs
- Prepare before filing
- Registered agent explained
- Seven-step Northwest walkthrough
- Get an EIN
- Banking and payments
- US tax basics
- Form 5472 and US filings
- Comorian tax and KMF questions
- Treaties, E-2 visas and sanctions
- Business model examples
- Compliance calendar
- DIY versus a formation service
- Mistakes to avoid
- FAQs
- Master checklist
Why Comorian founders consider forming a US LLC
Comorian entrepreneurs increasingly serve customers and partners across borders, from local professional services to software, e-commerce, creative work and trade. A founder in Conakry, Kindia, Labé, Kankan, or abroad may serve US clients, sell software subscriptions, publish online, or operate an e-commerce business with suppliers and customers in several countries. In these cases, a US entity can provide a familiar contracting party to customers who prefer to contract with a US company.
An LLC may also help put the business’s contracts, intellectual property, and operating records in one entity. Proper separation between personal and company activity can support limited-liability protection, though no entity protects an owner from every claim or personal guarantee. A US entity can also be useful where a provider has a product specifically for eligible US companies. Provider acceptance has to be confirmed; it is not automatic.
The US entity does not replace a Comorian business registration or personal tax assessment where local law requires one. Think of it as one legal component of a cross-border business, not a mechanism that moves your home, employees, or daily management to America.
Is a US LLC the right structure for your business?
Start by identifying the exact business need. “I want access to Stripe” or “I want to look more established” is not enough until you check eligibility and compare other options. A US LLC may add annual agent charges, state reports, bookkeeping, tax preparation, foreign exchange costs, and local advice. It may not be worthwhile for an occasional freelance project that can already be invoiced locally.
Reasons to consider it
- A specific US customer requires a US contracting company.
- A provider confirms that it can onboard an owner living in Comoros.
- You want a separate entity to hold contracts or business assets.
- You are preparing for a US-facing venture and have a realistic compliance budget.
- You have asked a Comorian tax professional how a foreign LLC is treated locally.
Reasons to pause first
- You assume the company automatically grants a US account or visa.
- You are relying on outdated screenshots or a provider’s generic marketing promise.
- You cannot document where you work or where the money comes from.
- You have no way to receive official mail or pay annual renewals.
- You have not considered local tax, VAT, registration, or currency requirements.
Before spending money, list your customers, the service or goods you sell, the places you perform work, the locations where inventory is held, and the route from customer payment to your suppliers or personal income. Then ask an accountant in Comoros and a US cross-border tax preparer to review those facts. This simple exercise often reveals whether a US LLC solves the right problem.
How a US LLC works
A Limited Liability Company is established under the law of one US state. It can own property, sign contracts, hire people, and hold accounts in its own name. For legal purposes, it is separate from its members. The members are its owners. Members can manage the business directly or appoint a manager.
State law and federal tax classification are separate. A single-member LLC is usually treated as a disregarded entity for US federal income tax unless it elects corporate taxation. A multi-member LLC is usually treated as a partnership by default. “Disregarded” does not mean ignored for every tax purpose: foreign-owned single-member LLCs can have information-reporting duties, and income source, US trade or business, withholding, and state taxes still need analysis.
| Term | Plain-English meaning | Practical effect for an owner in Comoros |
|---|---|---|
| Articles of Organization | The formation document filed with the state; Delaware uses “Certificate of Formation.” | Keep the approved, stamped document and confirm the legal name is correct. |
| Member | An owner of the LLC. | List actual owners and percentages in the internal records and disclosures requested by providers. |
| Registered agent | An in-state person or company that receives state and legal notices. | Must have a physical address in the formation state and be available during business hours. |
| Operating agreement | Private agreement defining ownership, management, contributions and distributions. | Banks and partners may ask for it even though it is not ordinarily filed with the state. |
| EIN | Employer Identification Number issued by the IRS. | Often requested by a bank and used for federal filings. |
| Foreign qualification | Registering the LLC in another state where it is doing business. | Forming in one state does not automatically avoid filings where real US operations occur. |
| Good standing | State status showing that required reports and fees are current. | May be needed for banking, contracts, financing or a later registration. |
A single founder commonly chooses a member-managed, single-member LLC. If two or more people own the company, the operating agreement should say how votes work, how profits and losses are allocated, whether new capital can be required, who owns work product, and how an owner can leave. A default statutory rule may not match the founders’ intent.
Can a Comorian citizen own a US LLC without moving to America?
Generally, yes. US states do not normally require an LLC member to be a US citizen or resident. The entity can be filed remotely through a state portal or a formation service. You do not normally need a US partner or nominee owner. A company may have a Comorian individual as its sole member.
Keep four separate questions in view:
- Company ownership: state LLC law normally permits foreign members.
- US immigration: owning an entity does not grant entry, residence, or work authorization in the US.
- Tax filing: depends on ownership, classification, income and activities in each relevant country.
- Financial account approval: belongs to the bank or fintech and depends on its country and risk policies.
A registered agent’s street address is also not your personal address or automatically the company’s genuine operating address. Give each government form and provider the address it requests: registered office, mailing address, residence, principal business location, and trading address may all mean different things.
Choose the right state for your US LLC
There is no single best state for every Comorian business. Your actual US footprint comes first. An office, employees, warehouse, inventory, or sustained in-state activities can create registration and tax requirements in a state even if the LLC was organized elsewhere.
If you have no US physical operations and only provide services remotely from Comoros, compare total upkeep, name availability, service provider convenience, and future plans. Popular options include Wyoming, New Mexico, and Delaware, but the lowest initial filing fee does not tell the whole story.
| State | Example filing cost | Recurring state item | Possible use |
|---|---|---|---|
| Wyoming | $100 Articles of Organization filing | Annual report and license tax; $60 minimum, with asset-based computation rules | Remote founder comparing modest filing and renewal costs. |
| New Mexico | $50 LLC filing | No routine annual LLC report under current state rules | Founder prioritizing lower state-level maintenance cost. |
| Delaware | Check current fee calculator and filing options | $300 annual LLC tax due June 1; Delaware LLCs do not file an annual report | Startup where investors or counsel prefer Delaware. |
| State of US operations | Varies | Varies by state and business activity | May be necessary where the company has a real office, people or inventory. |
Wyoming’s Secretary of State publishes a $100 LLC formation filing fee and its annual report requirements. Delaware’s Division of Corporations states that LLCs pay $300 per year and do not file an annual report. Fees and process charges can change, so use official state schedules when placing an order.
Example state filing fees (USD)
State filing only. It excludes registered-agent fees, expedited filing, card charges, and tax work. Check the current state portal before filing.
If you are seeking outside investment, ask prospective investors whether they expect a Delaware entity and whether it should be an LLC or corporation. Venture capital funds often use corporate stock structures, so an LLC can require a later conversion. For ordinary consulting revenue, Delaware’s reputation alone may not justify its recurring bill.
State privacy is not anonymity. A formation document might not list every member, but the IRS, bank, registered agent or other authorities may require owner information. Public filing rules also change. Our article on anonymous LLCs and privacy limits explains what public records do and do not conceal.
How much does it cost to form a US LLC from Comoros?
Budget for more than the filing service’s headline price. There are one-time formation expenses, annual state and agent expenses, and bookkeeping and cross-border tax costs. Currency conversion and international card fees can also affect the amount paid from Comoros.
| Cost item | Frequency | Planning note |
|---|---|---|
| State formation filing | Once | Examples above: $50 New Mexico or $100 Wyoming; other states differ. |
| Formation service | Usually once | Northwest’s advertised price in the reference material is $39 plus the state fee; verify current terms and add-ons at checkout. |
| Registered agent | Usually annual | Check whether the first year is included and what renewal costs. |
| EIN | Once | $0 if you apply directly to the IRS. Paid assistance is optional. |
| State annual filing or tax | Annual or state-specific | Wyoming has a $60 minimum annual license tax; Delaware’s LLC tax is $300 annually. |
| Accounting and tax preparation | Annual / ongoing | Quote a professional who handles foreign-owned US entities and local Comorian implications. |
| Banking and payments | Setup and transactional | Review incoming-wire fees, transfer costs, FX conversion, card charges, reserves and chargebacks. |
| Local business or tax compliance | Depends on activity | Ask the AGID or local counsel about registration and filing obligations. |
Illustrative Wyoming checkout: state filing plus advertised service price
Illustration excludes agent renewal, add-ons, international payment costs, accounting, and local taxes. Service prices can change; confirm before buying.
State filing fees as columns (USD)
One-time state filing fees only, before registered-agent or service charges. Official state fee schedules should be checked before filing.
Illustrative state-only cost over three years
Model counts the formation fee in Year 1 and one annual state charge in each later year (WY minimum $60; DE annual LLC tax $300; NM no routine LLC annual report). Excludes agent, service, tax and other-state costs. Actual due dates depend on formation date and current rules.
The table is a planning model, not a quote. An LLC that receives no revenue can still have fixed costs. A company that hires US staff or stores goods in a US warehouse may add payroll, insurance, sales-tax, and foreign-qualification costs. A company with several members may need an attorney to draft an operating agreement and tax advisers in more than one country.
Ready to review a formation quote? Compare the state fee, agent renewal, optional services and how you will pay from Comoros.
See Northwest Formation Options →What information should you prepare?
Prepare your details before opening the filing form. Consistency across the state filing, IRS EIN request, operating agreement, bank application and invoices prevents avoidable verification delays.
- Legal name: use the exact spelling on your passport or identity documents, including middle names where requested.
- Physical and mailing addresses: distinguish your home address in Comoros, the registered agent’s address, and any separate mailing address.
- Company name: search the state database and prepare alternatives. State name clearance is not trademark clearance.
- Business activity: describe actual services, products, customer types and operating countries.
- Ownership: confirm each member’s legal name, percentage, capital contribution, and management authority.
- Funding route: know which card or lawful transfer will pay state fees and recurring agent costs.
- Compliance contacts: identify who will monitor mail, renew the agent, file tax forms, and maintain accounts.
Consider permits and business licenses before launch. Certain professional, financial, travel, education, health, food, and import activities may require separate approval in the US or Comoros. Forming an LLC does not authorize a regulated service.
Registered agent: a required US contact
Every US LLC must maintain a registered agent in its formation state. The agent must have a physical street address in that state and be available during normal business hours to receive legal service and official notices. A Comorian residential address cannot fill this role.
- Mail handling: ask how notices are scanned and how quickly urgent legal papers are forwarded.
- Renewal price: record the annual renewal and payment date separately from the formation fee.
- Address scope: confirm whether the service address is used only for the registered agent role or can also receive ordinary mail.
- Replacement: if changing agents, appoint the new agent and file the state change before the old service ends.
Missing a lawsuit or state compliance notice can cause default judgments, missed deadlines or administrative problems. Keep your own calendar even when the agent offers email reminders. See our Northwest Registered Agent review for service considerations.
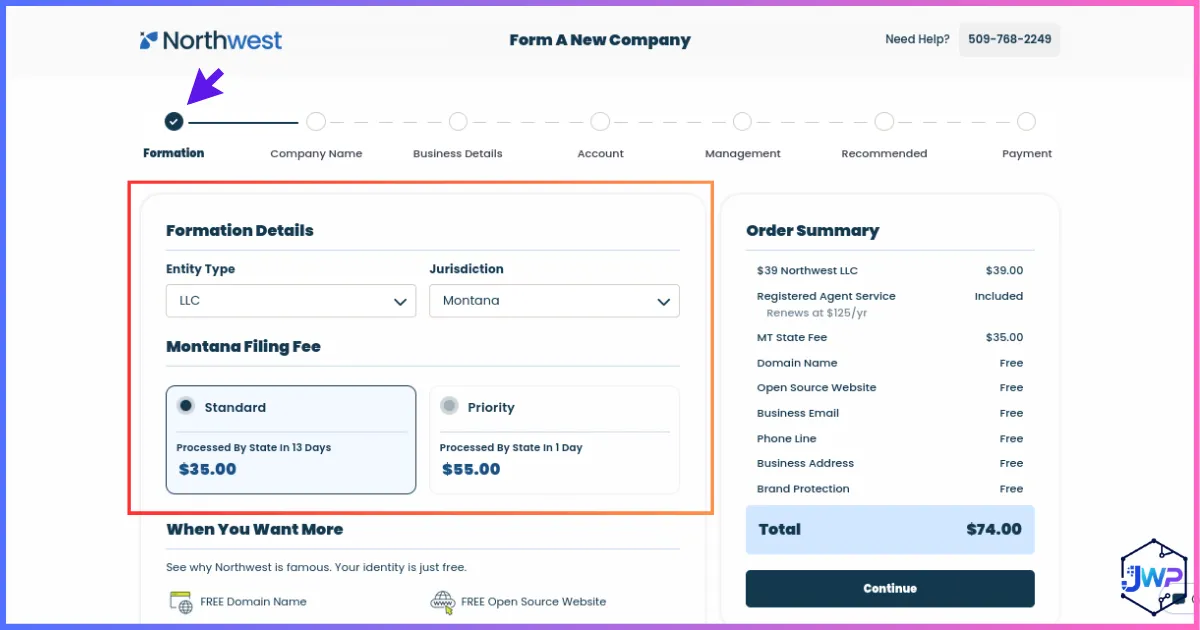
Step by step: Northwest Registered Agent’s seven-screen order
This walkthrough uses the formation service as a practical example. The checkout form can change over time; filing directly with the state is another route. Whichever method you use, check the final legal name, state, agent, fees and management information before submitting.
Choose LLC and formation state
Select an LLC and the state that matches your plan. For a Comorian founder with no US base, compare New Mexico and Wyoming. Choose Delaware when a real fundraising or legal reason points there. Do not select a state solely because a creator calls it “tax-free.”
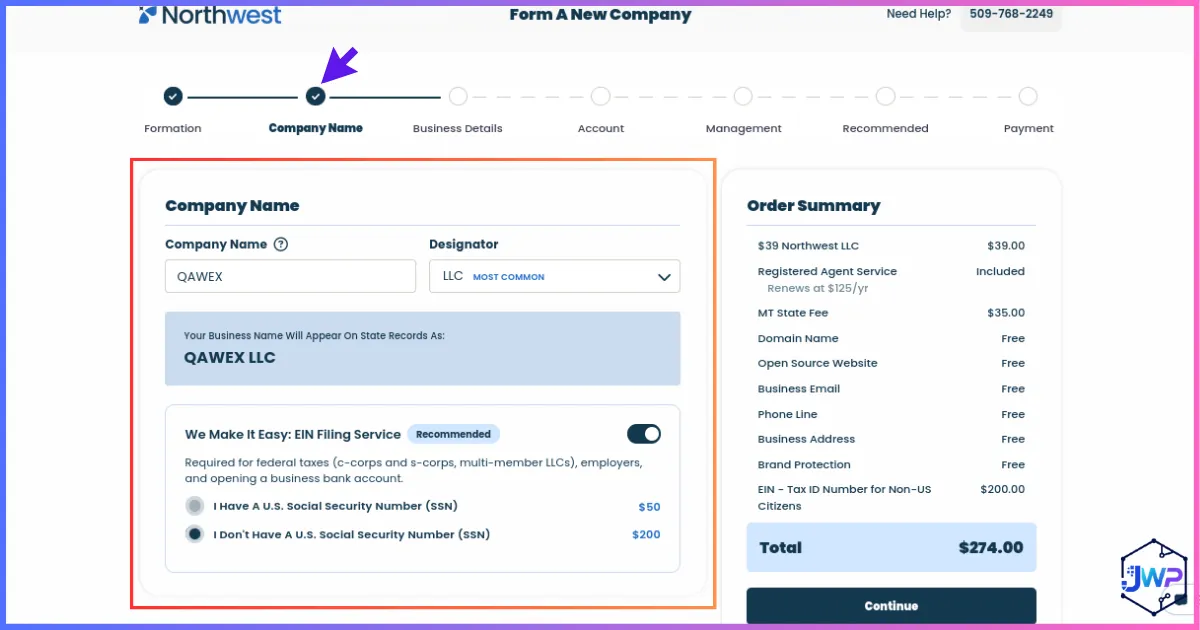
Enter your company name
Enter the exact proposed company name with its required LLC ending. Check availability in the relevant state’s registry. An optional EIN application service may be presented; the IRS itself issues EINs at no charge, and eligible international applicants can apply through IRS channels.
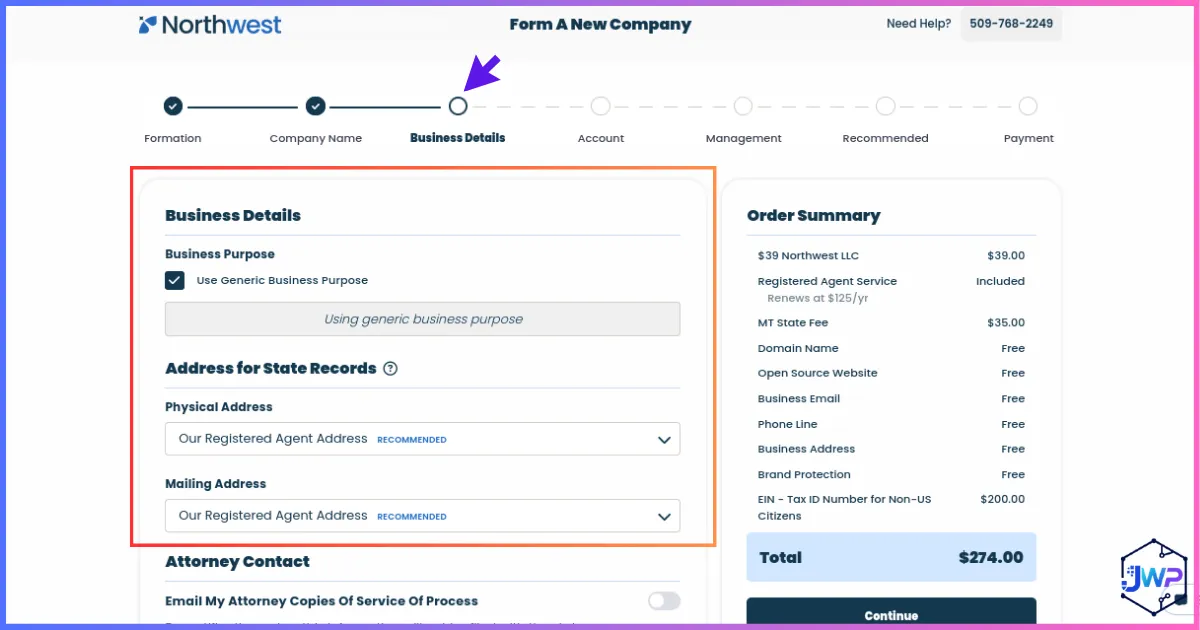
Provide business and contact details
Give the true business activity, contact email, and mailing information requested. If you work from Comoros, state your actual business location when asked. The agent’s in-state street address is not a substitute for your operating address.
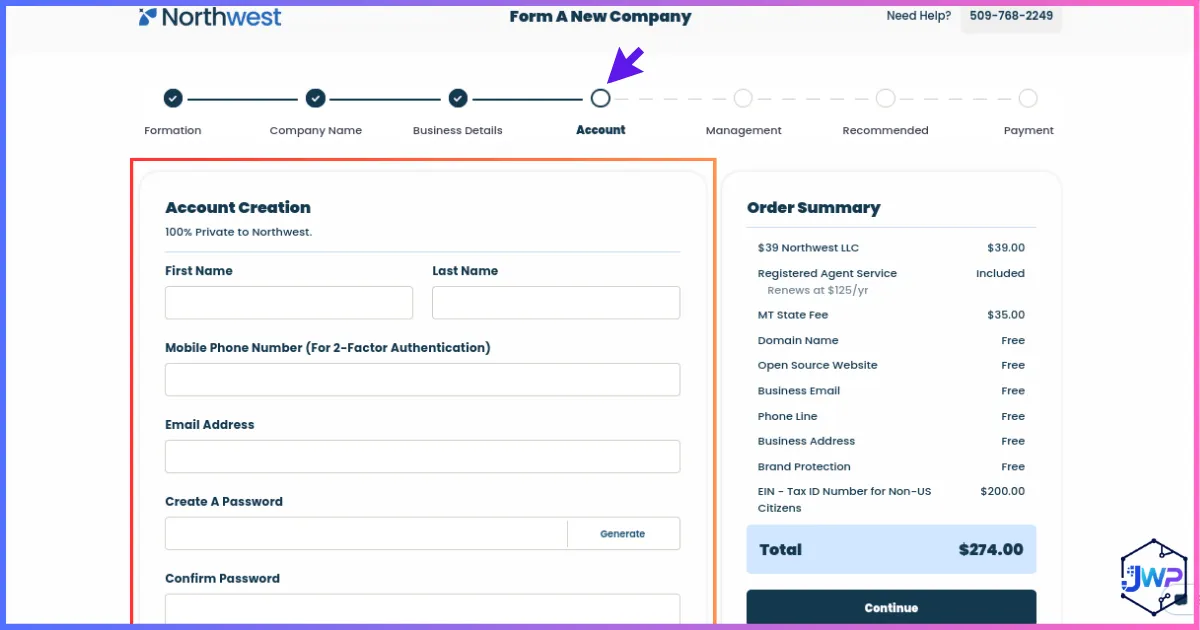
Create your customer account
Choose an email address you can retain long term and protect it with a strong unique password and multi-factor authentication where available. Keep a separate reminder for every annual renewal rather than relying on a single inbox notification.
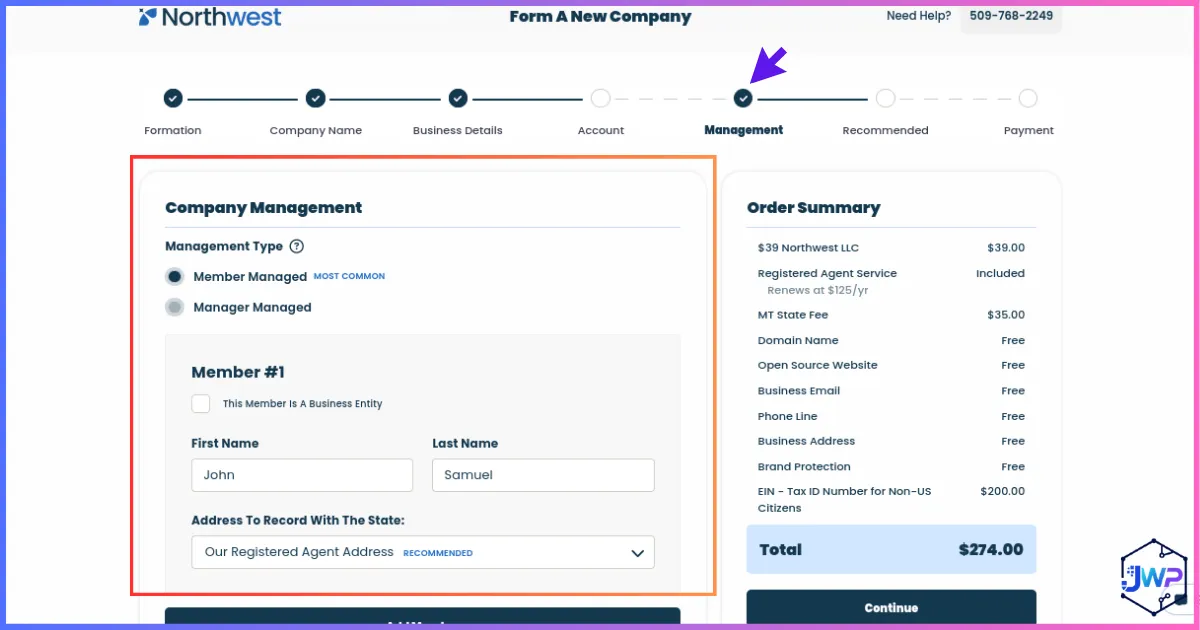
Enter management and ownership details
Choose member-managed when the owners directly run the business. Choose manager-managed only if that reflects the actual arrangement. Enter the member’s passport-matching legal name and real address. For multiple owners, agree on authority and percentage interests before filing.
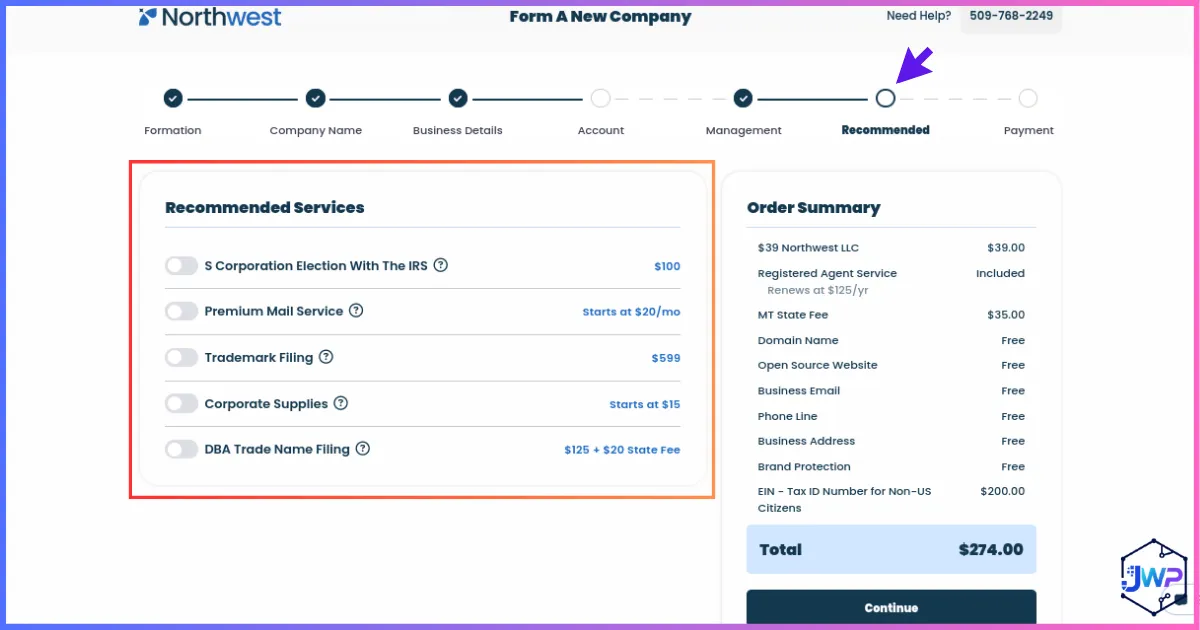
Review optional services
Review any EIN service, mail forwarding, certified documents, compliance reminders or other add-ons. Ask which items are one-time and which renew. Select an add-on only when you understand its use and price.
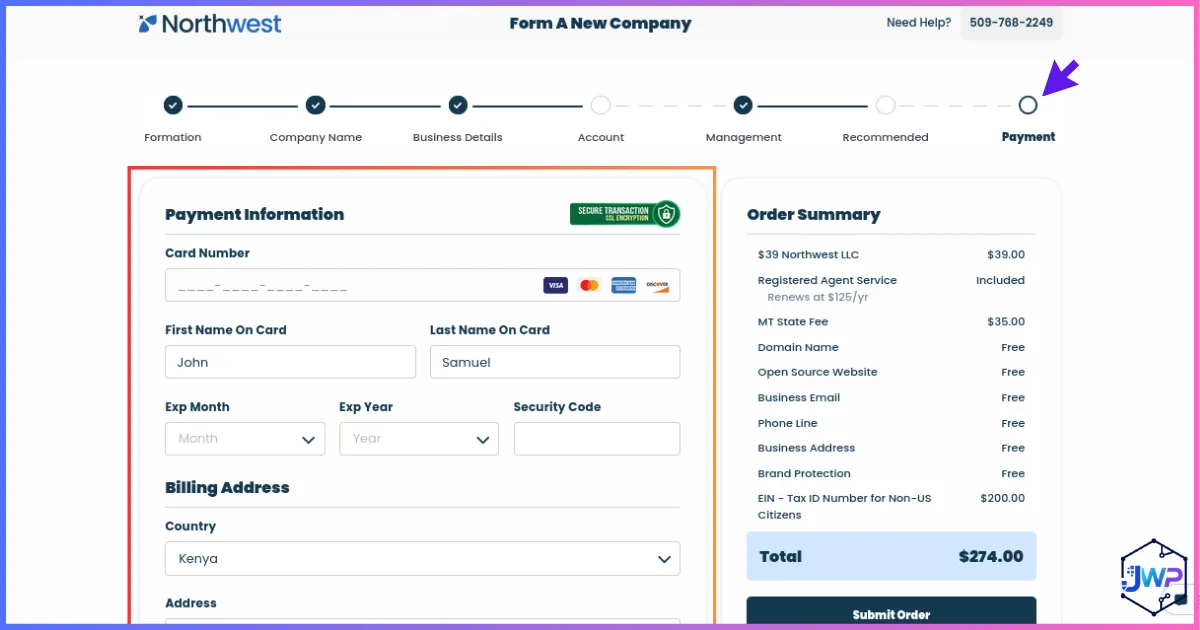
Review the total and submit payment
Check the line items: state fee, service charge, agent service, optional extras, and any payment-processing cost. Make sure your card issuer permits the international transaction and note the amount in franc after conversion. Save the receipt. The receipt shows an order was placed; wait for the approved state document to confirm the LLC exists.
How to get an EIN from Comoros
An EIN is a federal tax ID for the business. It is not the same as a personal ITIN, and the IRS does not charge for issuing it. Current IRS instructions say that applicants with no US legal residence, principal place of business, or principal office or agency cannot use the ordinary online EIN application. International applicants may use the IRS telephone route or submit Form SS-4 by fax or mail.
- Wait for LLC approval. Use the legal name and effective date from the state-approved filing.
- Complete Form SS-4. The responsible party should be a real individual who controls or owns the business as required by the form instructions.
- Line 7b: the IRS says to enter “foreign” or “N/A” when the responsible party has no SSN or ITIN and is ineligible to obtain one. An entry is required; do not leave it blank.
- Use an international application method. Review the current IRS phone number, fax route and mailing address in the live instructions. Details can change.
- Keep evidence. Save the submitted SS-4, fax confirmation or postal record, and EIN assignment notice.
- Wait rather than duplicate. The IRS limits applicants to one EIN per day; duplicate requests can create account confusion.
The IRS says faxed international applications may be handled in about four business days when a return fax number is given, while mailed applications can take about four weeks. Those are estimates, not service guarantees. The responsible party should be ready to answer IRS questions. A paid formation service can act as an authorized designee only when the paperwork properly authorizes it.
You do not automatically need an ITIN to create the LLC or request its EIN. You may later need an ITIN if your own US tax situation requires a personal return and you are not eligible for an SSN. Have a tax professional decide based on your actual filings, not a generic formation checklist.
Banking and payment processing for a Comorian-owned LLC
Bank onboarding is often the most uncertain part of forming from abroad. An EIN and state approval do not require a bank or fintech to accept a Comorian-resident owner. Each institution sets its own onboarding locations, business categories, identity evidence, risk limits, account features and funding rules. Policies change, so verify directly before selecting a formation state or paying a service.
Ask the provider specifically whether it accepts (1) a US LLC with a beneficial owner resident in Comoros, (2) the company’s real trading location in Comoros, (3) your business activity and customer countries, and (4) the route by which you will transfer money from the US account to Comorian suppliers or your local bank. “We accept non-US founders” may not answer all four points.
| Prepare | Why it helps |
|---|---|
| Passport and current proof of residential address | Identity and owner verification. |
| Approved Articles, EIN confirmation and operating agreement | Confirms entity existence, tax number, ownership and authority. |
| Website, contracts, invoices and supplier details | Shows what the company actually sells and to whom. |
| True operating/trading address | Separates the place you work from the registered agent address. |
| Expected payment volume and countries | Helps the provider evaluate account fit and transaction monitoring. |
| Source-of-funds explanation | Connects owner contributions and customer revenue to supporting documents. |
Compare an account that can receive ACH or wire transfers with a payment processor that accepts customer cards. A provider may offer one but not the other. Ask about monthly limits, reserves, chargebacks, refund handling, currency conversion, USD account details, outgoing transfers, account fees, and whether cards are available in your country of residence.
Our guides to opening Wise and opening Payoneer explain general setup. Wise says business account availability depends on country and address support, and its current business address policy requires a physical trading address in a country where it supports businesses. Confirm current service eligibility for Comoros before relying on a particular account.
US tax basics for nonresident LLC owners
US taxation depends on the owner, entity classification, income category, work location, assets and activity. A nonresident alien is generally subject to US tax on US-source income and income effectively connected with a US trade or business, subject to specific exceptions and applicable treaty provisions. The LLC’s location of formation does not determine the source of every dollar it earns.
Where you perform services matters
The IRS generally sources personal-service income where the work is performed, regardless of the customer’s residence, payment address or contract location. If you code, consult, design or manage a project from Comoros, payment by a US client does not by itself mean you physically performed the service in the United States. Workdays spent in the US can alter that analysis and may require a reasonable allocation.
Goods, intellectual property and property have separate rules
Inventory can be sourced based on where goods are purchased, produced or sold, and holding stock in a US warehouse can raise federal and state issues. Royalties may depend on where intellectual property is used. Rental property is tied to property location. Dividends and interest follow different rules. The label “online business” does not tell the tax authority which rule to use.
Withholding and tax forms
A US payer may ask for a W-8BEN, W-8BEN-E, W-9 or another form depending on who is treated as the beneficial owner, how the LLC is classified, and the payment type. Do not submit a W-9 merely because the company has a US EIN. Do not assume a W-8BEN is correct for every single-member LLC arrangement. Ask a cross-border tax preparer to identify the proper form.
The IRS treaty list does not include Comoros. Do not claim treaty benefits based on Comorian tax residence without an applicable treaty provision. It does not mean all income paid from the US is taxed at one rate; source, category and withholding rules still matter.
Form 5472 and other US filings
A foreign-owned US single-member LLC is generally disregarded for income tax, but is treated as a corporation for limited information-reporting rules under section 6038A. If it has a reportable transaction with a related party, it generally files Form 5472 attached to a pro forma Form 1120. Owner contributions, distributions, loans, and certain formation or dissolution transactions may be reportable. An LLC can have no customer revenue and still have reportable owner transactions.
The IRS Form 5472 instructions explain the foreign-owned disregarded entity filing method, due date and $25,000 initial penalty for failing to file a required form correctly and on time. A calendar-year entity generally follows the Form 1120 due date, usually April 15, and may request an extension using Form 7004 by the original deadline. The special Form 5472 submission instructions for foreign-owned US disregarded entities differ from ordinary electronic filing. Use the current IRS instructions or a preparer rather than reusing outdated mailing information.
Recurring state costs compared with a possible information-return penalty
State costs: state sources below. Form 5472 penalty: IRS instructions. Illustrative comparison only.
A multi-member LLC generally has a different tax classification and return path. A corporate election changes the reporting obligations too. If an owner joins or leaves, ownership percentages change, the company lends money, or the entity is dissolved, re-check tax forms and state filings. Keep a ledger that distinguishes customer receipts, owner capital, personal withdrawals, reimbursements, loans, and expenses.
Federal beneficial-ownership information status
FinCEN’s 2026 final rule states that US-created companies are exempt from federal beneficial ownership information reporting, while certain foreign-formed companies registered to do business in the United States remain in scope. Review FinCEN’s current BOI FAQ at formation because the rules have changed more than once. A federal BOI exemption does not mean banks stop asking for beneficial owners, and states may have separate disclosure rules.
Comorian tax, business registration and KMF planning
Forming a US LLC does not automatically remove obligations in Comoros. If you are a Comorian tax resident and perform the company’s work from Comoros, consult Comoros’s Administration Générale des Impôts et des Domaines (AGID) or a qualified Comorian accountant about how local law treats the income and entity. The answer can depend on residence, business activity, source rules, local registration, management location, payment type and the relationship between the owner and LLC.
The Code général des impôts, 2023 edition is an official starting point for checking Comorian tax rules. Ask the Administration Générale des Impôts et des Domaines (AGID) or a qualified Comorian tax professional about later finance laws and how local law classifies your US LLC. Tax residence, work location, management activity, and the nature of each payment can affect the analysis. This guide does not assume a specific Comorian rate or threshold.
Ask an adviser to consider these separate issues:
- Personal income tax: how are payments or distributions from a foreign LLC treated when the owner lives and works in Comoros?
- Business presence: does day-to-day management or local service delivery require registration or create local taxable activity?
- VAT: could digital services, consulting, goods or marketplace sales require local VAT registration or reporting?
- Employees and contractors: what payroll, withholding, social protection or contract rules apply when people work in Comoros?
- Foreign receipts: what records support USD or other foreign-currency revenue and conversions?
- Business permits: does the sector require a license or special registration independent of tax?
The Comorian franc (KMF) is Comoros’ currency; Comoros is not part of the CEMAC currency union. The Banque Centrale des Comores (BCC) states that KMF is the only currency accepted for transactions in Comoros and directs people to banks, financial institutions, and licensed exchange offices for currency operations. Its monetary-cooperation information describes the fixed euro–KMF parity and notes that foreign-currency assets are subject to exchange rules. This does not set the fees or USD conversion rate your bank will offer. Ask your bank and a local adviser which route and records apply to customer receipts, transfers to yourself, supplier payments, and conversion into KMF. Keeping a US account does not remove local tax, reporting, or exchange-control questions.
A practical path for cross-border business receipts
- 1Customer paysInvoice and contract identify the LLC
- 2Record the receiptKeep the statement, invoice, and transaction purpose
- 3Transfer compliantlyConfirm the bank channel and required documents
- 4Plan KMF useTrack conversion and local expenses
Process illustration, not a legal requirement checklist. Ask your bank and adviser how current Banque Centrale des Comores requirements apply to your specific receipts and transfers.
If you are Comorian by nationality but live elsewhere, the residence country’s rules may also apply. The US filing does not determine your personal tax residence. Our guides to Madagascar, Mauritius, and Tanzania cover African and Indian Ocean regional examples, but their laws should not be substituted for Comorian advice.
US–Comoros treaties, E-2 visas and sanctions screening
Comoros does not appear on the IRS’s current list of countries with an operative US income-tax treaty. A Comorian resident should not claim treaty rates for US-source income merely because they own an LLC. The default tax treatment still depends on the income’s source, category, and applicable US rules.
Company ownership also does not qualify someone for an E-2 investor visa. The US Department of State’s Comoros visa reciprocity schedule lists “No Treaty” for E-1 and E-2. This visa-treaty status is separate from income-tax treaty coverage. Anyone considering moving to the United States needs separate immigration advice; an LLC registration by itself gives no immigration status or work authorization.
Sanctions screening is not a country label to guess at. Restrictions may target named persons, entities, sectors, regions or types of transaction. Screen relevant counterparties using the official OFAC Sanctions List Search and obtain legal advice if a transaction raises a concern. Banks can apply risk policies beyond legal minimums. Never omit an owner, customer or destination to evade review.
How your business model changes the setup
Consultant, designer or software developer
If you carry out all client work in Comoros, the work location matters for US sourcing of personal services. Keep contracts, invoices, deliverables, and a travel diary if you work some days in the United States. Also ask about Comorian personal or business tax, local registration, and whether a US client needs a particular tax form.
Digital product, SaaS or online education
Subscription software, downloadable content, training and advertising revenue may fall into different categories. Contract terms and intellectual-property rights matter. Decide which entity owns the code, brand and content, and document any transfer from you personally to the LLC. Check sales-tax exposure for US customers and VAT rules where customers or the business are located.
Online seller with stock in the United States
A marketplace seller holding inventory in a US warehouse has more US contacts than a consultant working from Accra. Inventory location, fulfillment, sales tax, import responsibilities, returns, product liability and foreign qualification may matter. Identify every state where goods are stored before choosing where to form.
Creator, publisher or affiliate marketer
Ad revenue, sponsorships, affiliate commissions, subscriptions and licensing are not automatically the same income type. A platform’s payout location does not alone determine US source. Use contracts and platform statements to track each revenue stream and ask how withholding forms should reflect the beneficial owner and LLC classification.
Founder raising venture capital
Some US investors prefer a Delaware corporation with stock, a board and familiar financing terms. An LLC may not fit a fund’s structure or tax-exempt investors. Ask prospective investors and counsel about entity choice before creating a company that may need conversion soon after formation.
Two or more owners in different countries
Multiple owners create more questions about partnership returns, profit allocations, withholding, tax residency and bank identity verification. Draft a detailed operating agreement before accepting money. Specify decision authority, access to funds, expense reimbursement, deadlock resolution, member departure, intellectual property and procedures if one member cannot complete bank onboarding.
A practical annual compliance calendar
Exact due dates depend on the state, tax year, entity classification and local rules. Add the following checkpoints to your calendar and confirm the date with the official authority for your situation.
| When | Task | Records to keep |
|---|---|---|
| On formation | Save state approval, signed operating agreement, agent confirmation and initial contribution record. | Entity folder and payment receipt. |
| Monthly | Reconcile bank transactions, customer receipts, owner deposits, draws and expenses. | Ledger, invoices, bank statements and FX rates. |
| Quarterly | Review customers, US activities, inventory locations, contractors and provider-policy changes. | Short internal review and updated adviser questions. |
| Federal filing season | Check Form 5472/pro forma Form 1120, any personal return or other forms; submit an extension by the original due date if applicable. | Filed copy, fax or mail evidence and extension confirmation. |
| Wyoming anniversary month | File the annual report and pay the applicable license tax by the state deadline. | Wyoming confirmation and updated asset calculation. |
| June 1, if Delaware LLC | Pay Delaware’s $300 annual LLC tax. | Payment confirmation. |
| Agent renewal date | Renew the agent or appoint a replacement before ending the old service. | Agent contract and invoice. |
| Comorian statutory dates | Review local income tax, VAT, business, payroll and foreign-exchange documentation needs. | Returns, receipts and supporting account records. |
Do not assume that a year without profit means no filing. Conversely, do not file every form listed in a generic online checklist without determining if it applies. A tax preparer should know the ownership structure and every owner transaction, including money put in at formation.
If the business closes, dissolve it formally. Stop new transactions, settle liabilities, close platform and bank accounts as appropriate, cancel state registrations, file final returns where due, and retain company records. Letting the agent expire is not the same as dissolving the entity.
DIY filing versus a formation service
Most states allow direct filing, and their websites are the authoritative source for state fees. A foreign founder still needs an in-state registered agent and must complete the filing accurately. A formation service can package the registered agent and provide a dashboard, but it does not take over your local tax filings, bank approval or annual IRS work.
| Option | Works well when | What remains your responsibility |
|---|---|---|
| Direct state filing | You are comfortable with the state portal and can contract with an agent directly. | Name, filing details, agent, operating agreement, EIN and all ongoing compliance. |
| Formation service | You prefer a guided order and bundled registered-agent support. | Review add-ons and renewals; arrange tax advice, records, accounts and local filings. |
| US lawyer and cross-border accountant | You have multiple owners, investors, US staff, inventory, regulated activity or complex tax facts. | Provide complete records and follow through on assigned filings. |
See our comparison of LLC formation services for non-US residents before deciding. Compare customer support, agent renewal price, mail handling and the checkout total; the lowest headline offer may not include what you need.
Have a state in mind? Compare the itemized state fee, registered-agent term and optional services before paying.
Review Northwest’s Formation Order →Common mistakes to avoid
Risky assumptions
- “Wyoming means I owe no tax anywhere.”
- “A US LLC guarantees a US bank account.”
- “I can use my agent’s address as an office.”
- “No sales means no IRS filing.”
- “Every payment from a US customer is US-source service income.”
- “I can claim an E-2 visa because I own a US company.”
- “My local tax rules stop applying once I form abroad.”
- “The order receipt proves the state approved my company.”
Safer habits
- Map work, residence, ownership, customers and assets before selecting a state.
- Confirm eligibility with a bank using your real country and activity.
- Keep registered, mailing and operating addresses distinct.
- Track owner transfers and have Form 5472 assessed annually.
- Separate service, inventory, licensing and property income.
- Use State Department guidance for immigration eligibility.
- Ask the AGID or a Comorian adviser about local obligations.
- Save the approved Articles and calendar every renewal.
A useful rule is to match each question to its authoritative source. State Secretaries of State explain formation fees and annual reports. The IRS explains EIN and federal tax forms. FinCEN handles federal BOI rules. Comorian authorities administer local law. Banks decide whether to onboard customers under their own current policies. A formation service helps submit a filing but does not replace those authorities.
FAQs: forming a US LLC from Comoros
Can a Comorian citizen own a US LLC?
Can I form a US LLC while living in Accra?
Do I need a US visa, SSN or US business partner?
Which state is best for a Comorian founder?
How much does it cost to form a US LLC from Comoros?
Can I get an EIN without an SSN?
Will a US bank accept my Comorian-owned LLC?
Does the United States have an income-tax treaty with Comoros?
Does forming a US LLC make my Comorian income tax-free?
Do I owe US tax if I work from Comoros for US clients?
Does every foreign-owned single-member LLC file Form 5472?
Can owning an LLC qualify me for an E-2 visa?
Is federal BOI reporting required for a US LLC formed in 2026?
Can I use a virtual mailbox as my registered office?
What if I later add a business partner?
Master checklist: US LLC from Comoros
- ☐ Identify why a US entity is needed and compare a Comorian or other local alternative.
- ☐ Map residence, actual work location, customers, suppliers, employees and inventory.
- ☐ Check provider eligibility for a Comorian-resident owner and genuine operating address.
- ☐ Ask a Comorian adviser how the US LLC and owner income are treated locally.
- ☐ Pick a state based on real US activities, filing fee and annual cost.
- ☐ Prepare owner identity, business details, name options, and payment route.
- ☐ Keep the state-approved Articles and agent confirmation.
- ☐ Sign an operating agreement and document initial owner funding.
- ☐ Apply for an EIN using current international IRS instructions.
- ☐ Prepare accurate account applications with passport, address proof, contracts and website.
- ☐ Start monthly bookkeeping and distinguish company money from personal money.
- ☐ Review US income source, Form 5472, state, withholding and other tax forms.
- ☐ Calendar state report, agent renewal, federal filings and Comorian compliance dates.
A US LLC can make sense for a Comorian founder serving international customers, but only when it fits the actual business, works with a verified payment route, and sits inside a realistic tax and recordkeeping plan. Choose the state deliberately, make truthful disclosures, and budget for annual duties from the outset. That is what turns a remote filing into a dependable business structure.
Sources & Research Notes
Official sources reviewed September 2026. Prices and regulations change, so confirm current requirements before formation. Provider policies are not government guarantees.
- IRS, Instructions for Form SS-4 — international EIN application routes, line 7b and processing estimates.
- IRS, Instructions for Form 5472 — related-party transaction reporting, foreign-owned US disregarded entity procedure, due date and penalties.
- IRS, Nonresident aliens: sourcing of income — source rules for services, inventory, rents, royalties and other categories.
- IRS, United States income-tax treaties A–Z — list of operative US income tax treaties.
- FinCEN, Beneficial Ownership Information FAQs — current 2026 rule for domestic and foreign-formed entities.
- US Department of State, Comoros visa reciprocity schedule — lists “No Treaty” for E-1 and E-2.
- Wyoming Secretary of State, LLC Articles and instructions and fee schedule — formation and annual-report details.
- New Mexico Secretary of State, domestic LLC guidance — state formation process and fee context.
- Delaware Division of Corporations, tax FAQ — LLC annual tax and annual-report requirements.
- Comoros, Code général des impôts, 2023 edition — official tax-code reference; check later finance laws and AGID guidance.
- Banque Centrale des Comores, monetary-cooperation agreement — currency, euro parity, and foreign-currency asset context.
- Banque Centrale des Comores, public reminder on domestic currency — states that KMF is accepted for transactions on Comorian territory.
- Wise, Business address verification — provider requirements for trading addresses.
- US Treasury OFAC, Sanctions List Search — official screening resource.