How to Form a US LLC from Australia A practical guide to formation, US filings and Australian tax treatment
Australians can own and operate a US limited liability company without moving to America. The filing is often straightforward; deciding whether the LLC is the right vehicle takes more thought. This guide covers the complete process from Sydney, Melbourne, Brisbane, Perth or elsewhere in Australia, including state choice, real costs, an EIN, banking, US tax returns, the Australia–US treaty and the Australian rules that can change how your LLC income is taxed.
Quick Answer: How to Form a US LLC from Australia
An Australian citizen or resident can generally form and wholly own a US LLC remotely. First decide whether a US entity solves a genuine customer, investor or operational need. Choose a state based on where the business will actually operate; appoint its registered agent; file Articles or a Certificate of Formation; adopt an operating agreement; obtain an Employer Identification Number (EIN); apply for suitable banking; and track US and Australian tax and reporting obligations.
The Australian tax analysis comes before the filing. A single-member LLC is normally disregarded for US federal income tax, but Australia does not simply copy that classification. An Australian resident may be taxed on worldwide income; a US LLC can be treated as a company or, if Division 830 conditions are met, a foreign hybrid treated as a partnership. Residence, management and control, GST, ASIC registration and foreign tax offsets can also matter. The Australia–US treaty does not make all LLC income tax-free or guarantee treaty benefits to an LLC.
For a remote services business with no US premises, Wyoming or New Mexico can be cost-conscious options. Delaware may suit a particular legal or financing plan. An Australian Pty Ltd may be simpler when management, staff and customers are mainly in Australia. Ask an adviser familiar with both systems to model the structure before transferring valuable assets or revenue into a new LLC.
Table of Contents
- Is an LLC right for you?
- Ownership and LLC basics
- Choose a US state
- Fees and visual comparisons
- Documents and decisions
- Seven-step formation walkthrough
- Get an EIN
- Banking, payments and FX
- US tax and information returns
- Australia–US treaty
- Australian tax and foreign hybrid rules
- ASIC, ABN and GST
- Compliance calendar
- Alternatives and decision guide
- Australian founder scenarios
- Launch checklist
- Frequently asked questions
When Does a US LLC Make Sense for an Australian Founder?
A US LLC gives a business a separate state-law identity. It can contract with US customers, own assets, open accounts if approved, and hold membership interests. These are useful features when US activity is real. They do not by themselves reduce Australian tax, create US immigration rights, or make every banking and merchant application eligible.
Australians who work solely from Australia for American clients can often invoice as an Australian sole trader or Pty Ltd. A US invoice address is not inherently required to be paid in USD. The administrative cost of a second entity must earn its keep. A consultant with no US staff, office or inventory might find the US LLC attractive for contracting but still face substantial Australia-side compliance.
Compare the total structure: US entity plus registered agent, banking, US tax, Australian tax, GST and legal registration. If investors expect venture equity, they may ask for a Delaware C corporation rather than an LLC. If most people and assets are in Australia, a Pty Ltd often makes ownership, payroll, GST and local banking easier.
Can Australians Own a US LLC? The Terms You Need
US state law generally allows a non-US citizen to own 100% of an LLC. Neither a US co-owner nor a US Social Security number is normally required for the state filing. You do need a registered agent with a qualifying in-state address. Ownership does not grant a US visa, residence or work authorization; physically working in the US raises a separate immigration question.
| Term | Plain meaning | Australian founder implication |
|---|---|---|
| Articles of Organization | State document creating the LLC | Keep the accepted, stamped copy for accounts and advisers. |
| Registered agent | In-state person or firm receiving legal notices | Your Australian home or accountant cannot replace the agent. |
| Operating agreement | Rules for owners, management and distributions | Essential for partners and useful for a solo owner’s bank file. |
| EIN | Federal employer identification number | Free direct from IRS; Australian principal location affects application channel. |
| Disregarded entity | Default US income-tax status of a one-owner LLC | Does not determine Australia’s classification of the LLC. |
| Foreign qualification | Registration in another US state where business occurs | A Wyoming LLC may still register where its US warehouse or staff are. |
| Foreign hybrid | Australian tax treatment under specified Division 830 rules | Potential partnership treatment requires a factual legal test. |
The LLC’s liability shield normally separates company obligations from owners’ personal assets. It is not absolute: personal guarantees, fraud, commingled funds and failures to respect the entity can undermine protection. Keep separate books and accounts, sign contracts in the LLC name and document transfers between you and the company.
A one-member LLC defaults to disregarded status for US federal income tax unless it elects corporate taxation. Two or more members usually default to partnership taxation. Either can choose a corporate election in appropriate circumstances. Those options have different US filings and may create a mismatch with Australian rules. Decide on classification with tax advice before filing elections or telling a bank that the LLC is a corporation.
Choose the Formation State Based on Operations
Start with the state in which the LLC will actually have people, premises, inventory or repeated physical activity. A low-fee formation state cannot eliminate another state’s registration, income tax or sales-tax nexus. If the US footprint is genuinely absent, compare the base and recurring costs of states commonly used by remote founders.
| State | Base formation | Routine annual state charge | Likely fit | Limitation |
|---|---|---|---|---|
| New Mexico | $50 | No routine LLC annual report | Simple remote business focused on state fees | Agent, tax and licensing costs still exist. |
| Wyoming | $100 | Annual report licence tax, $60 minimum | Remote owner seeking predictable state maintenance | Online convenience fee and assets-based amount can increase cost. |
| Delaware | Check current Certificate fee; illustrative $110 | $400 annual LLC tax, due June 1 | Specific counsel, investor or contract preference | Pay the annual tax even though LLCs do not file an annual report. |
| Actual US operating state | Varies | Varies | US employees, office, inventory or property | May be required even if formed elsewhere. |
Wyoming’s official Articles list a $100 filing fee. Delaware’s Division of Corporations states that LLCs owe $400 annually by June 1; older articles may quote $300. State schedules and processing charges can change, so use the current filing portal or order checkout before paying. New Mexico’s lack of a routine LLC annual report does not remove the need for a registered agent or other applicable filings.
Column chart: illustrative base LLC formation fees (USD)
State filing fees only; Delaware value is an illustration requiring a live fee check. Sources: state filing authorities, September 2026.
Horizontal bar chart: minimum recurring state charges (USD)
Routine state report or tax only. Excludes registered agent, accounting, online processing and state income or sales tax.
What Will an Australia-Based Owner Actually Spend?
Budget separately for formation, keeping the company alive, professional advice and moving money. The cheapest advertised package may exclude the second year’s agent fee or optional services automatically shown at checkout. Currency conversion matters too: a USD invoice may produce a different AUD cost by the time the card or bank settles.
| Item | Planning amount | Timing | How to verify |
|---|---|---|---|
| State filing | $50 NM; $100 WY; DE fee to confirm | Once | Official state portal or itemized service checkout |
| Formation service | Illustrative $39 plus state fee | Once | Live Northwest checkout; add-ons vary |
| Registered agent | Often $100–$200 per year | Every year | Ask whether first year is included |
| Direct IRS EIN | $0 | Once | IRS instructions |
| Wyoming annual report | $60 minimum | Every year | Current Wyoming schedule |
| Delaware LLC tax | $400 | Every year | Delaware Division of Corporations |
| US and Australian tax review | Quote required | At setup and annually | Ask for two-jurisdiction scope in writing |
| Banking and AUD/USD conversion | Provider-specific | Ongoing | Compare both visible fees and exchange spread |
For example, an illustrative Wyoming order using a $39 formation-service charge and the $100 state filing starts at $139 before payment processing, add-ons, registered-agent renewal and tax advice. This is not a current quote. A professional classification review can cost more than the formation; it may also prevent years of difficult filing corrections.
Donut chart: illustrative $139 Wyoming formation checkout
Planning example, not a live quote. Excludes agent renewal and all optional services.
Line chart: cumulative minimum state charges after formation
Uses NM $50 once; WY $100 plus $60 minimum after each of two annual cycles; DE illustrative $110 plus $400 after each of two annual cycles. State-level charges only.
Compare the full order. Include the state fee, optional services and registered-agent renewal in your decision.
Review Northwest Formation Options →Prepare the Facts Before Filing
Decide who will legally own the LLC: you personally, an Australian Pty Ltd, a trust, or several members. This choice affects US Form 5472, US partnership rules, Australian foreign hybrid questions, related-party transactions and banking verification. Changing ownership later can create a taxable transaction or new reporting work. Draw the ownership chart first.
- Name: search the state database; include its required LLC designator; check trademarks separately.
- Addresses: distinguish your real Australian residence, actual principal place of business, US agent address and correspondence address.
- Purpose: describe products and services accurately; an invented US office makes bank and tax records unreliable.
- Management: select member-managed or manager-managed and document who makes decisions.
- Partners: agree on capital, voting, profit splits, withdrawals and exits before filing.
- Evidence: prepare passport or other accepted ID, proof of Australian address, website, contracts and expected payment flow.
- Tax memo: have an adviser outline US classification, Australian treatment, entity residence, GST, treaty and potential ASIC registration.
Search the name before buying a domain. A state can approve an LLC name that infringes someone else’s trademark, and a domain registration does not reserve a company name. Where a US customer requires a particular company name on purchase orders, match the exact legal entity name across the state filing, W-8 or W-9 documentation and invoices.
Your registered agent receives lawsuits and state notices during normal business hours in the formation state. An Australian address or virtual mailbox is not automatically an acceptable agent. Compare document scanning speed, renewal price, account access and what happens if a payment card expires. Keep control of the service account and the email that receives notices.
Seven Steps: Form a US LLC from Australia with Northwest
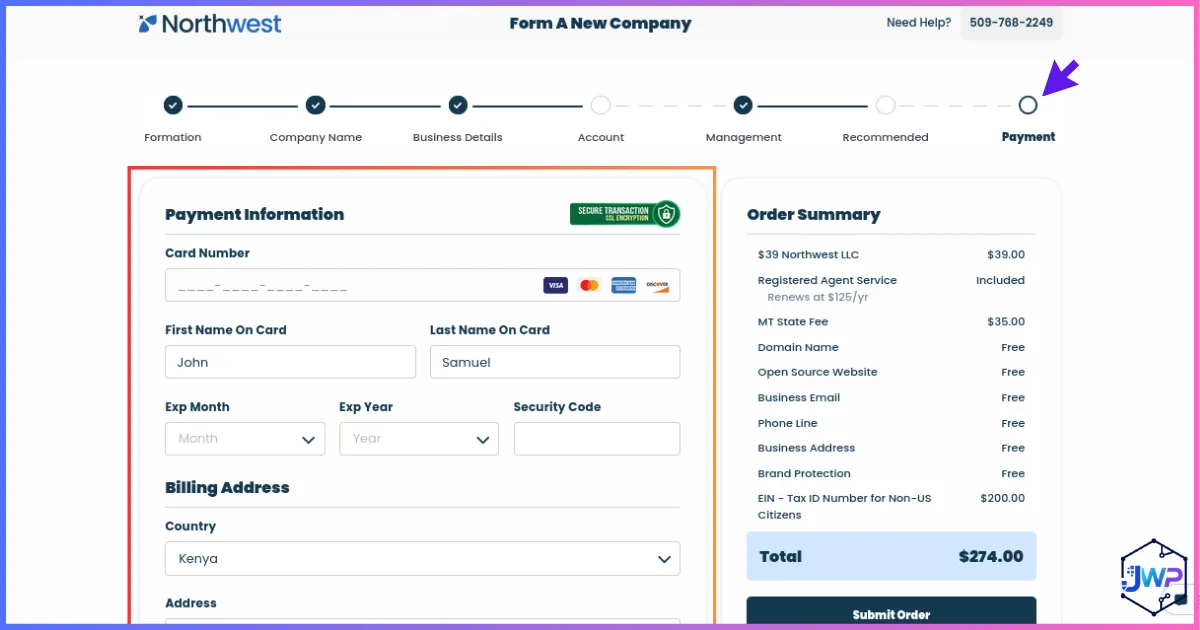
The screenshots below show a guided formation order. Screen labels and live prices can change. The images illustrate choices you will make; read each current order page before paying. Direct state filing is also possible if you appoint your own registered agent and understand the state form.
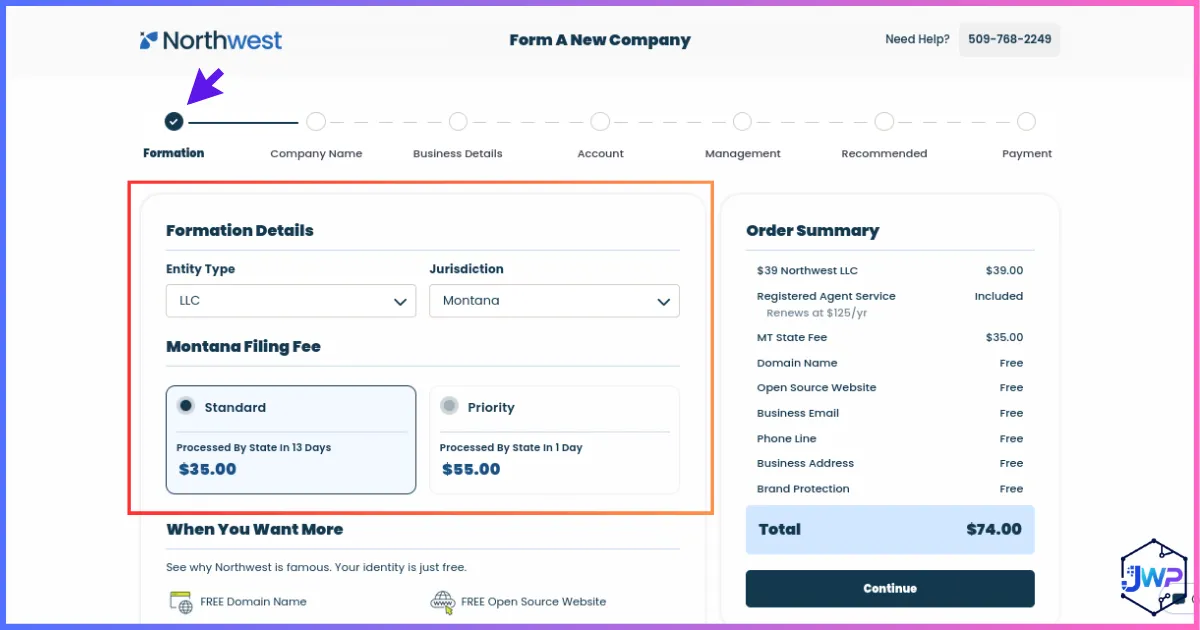
Choose the LLC and formation state
Select LLC, then the state that fits actual operations. If a US office or warehouse exists, discuss whether that operating state should be the formation state. For a wholly remote Australian service business, compare New Mexico and Wyoming against Delaware’s higher annual tax. Record why you chose the state; the answer helps when an adviser later reviews state nexus.
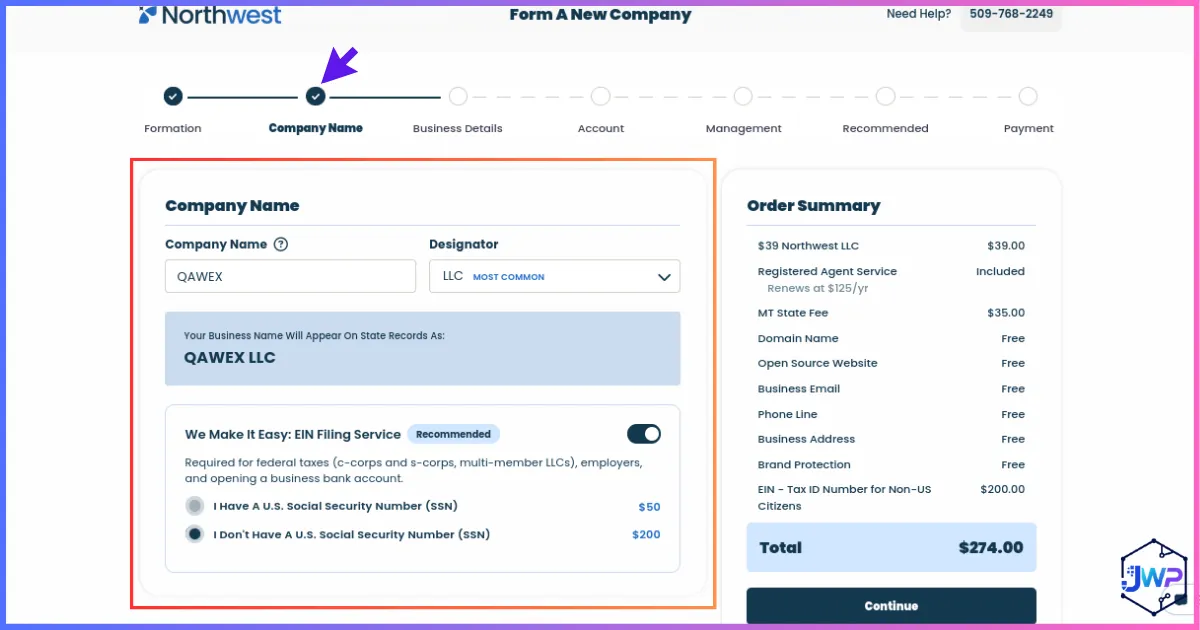
Enter the legal company name
Use the exact name and LLC designator required by your state. Match the spelling you will use on customer contracts and invoices. The order may offer paid EIN assistance; the IRS charges no fee for a direct application, so consider the service only for convenience or professional support.
Provide accurate business details
Describe the activity plainly: software consulting, design, wholesale trading or another real line of work. Give the Australian operating address if that is where work and management occur. Do not present the registered agent’s office as your own workplace or residential address.
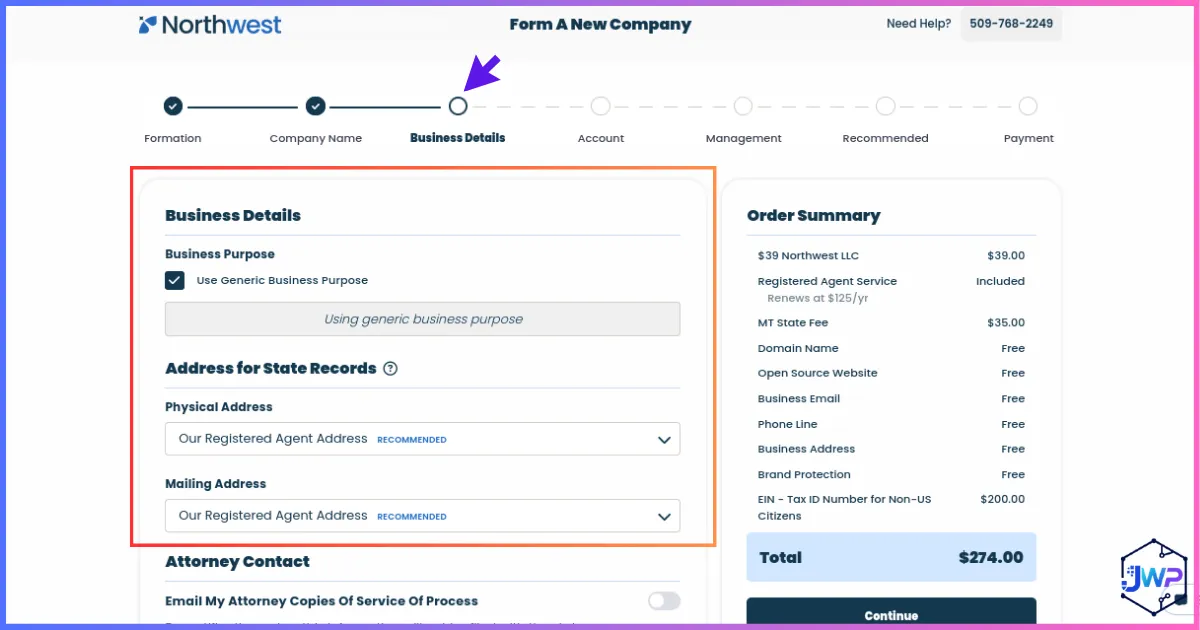
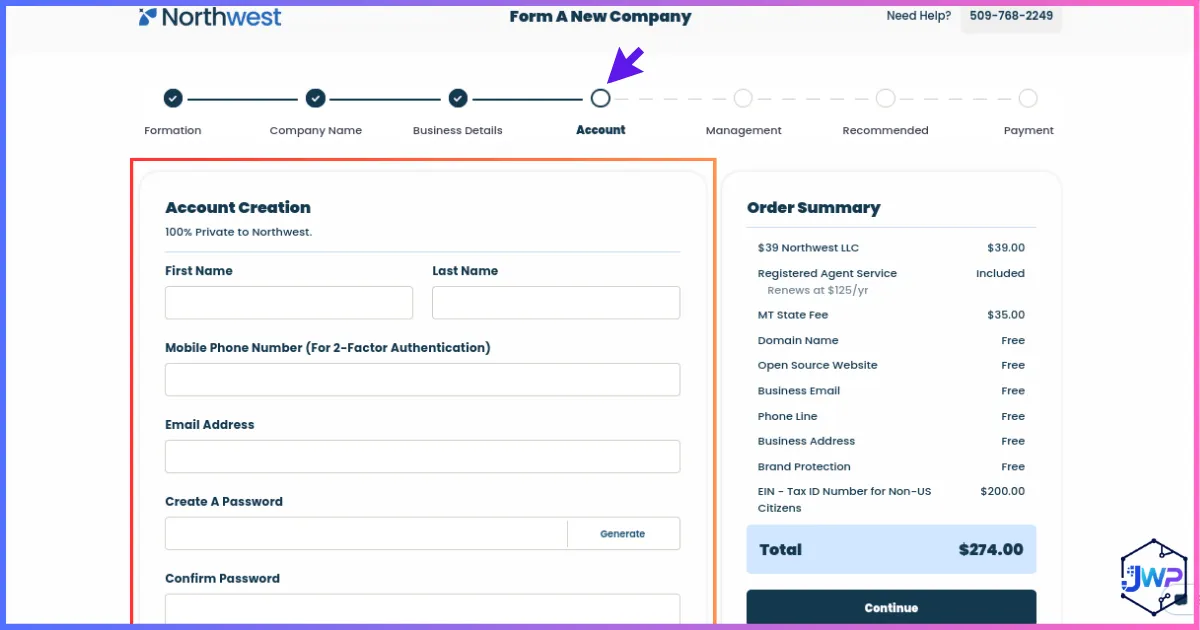
Create and secure the service account
This account may contain approved filings, scanned legal notices and renewal reminders. Use an email that the owner controls and enable account security features. Save access for a second trusted person if the company has partners; a missed legal notice can be more expensive than a late marketing launch.
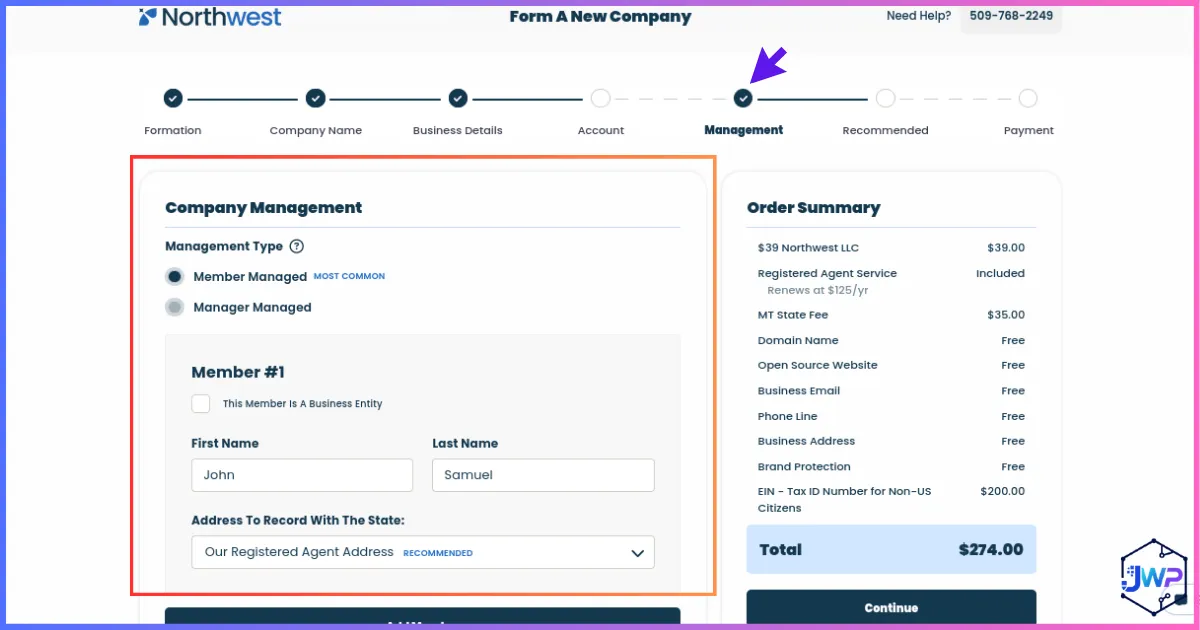
Record owners and managers
Enter the legal names and real details of all members. A solo founder usually selects member-managed unless an agreement calls for another arrangement. If an Australian Pty Ltd or trust will own the US LLC, list the correct legal owner and understand how the bank will trace ultimate beneficial owners.
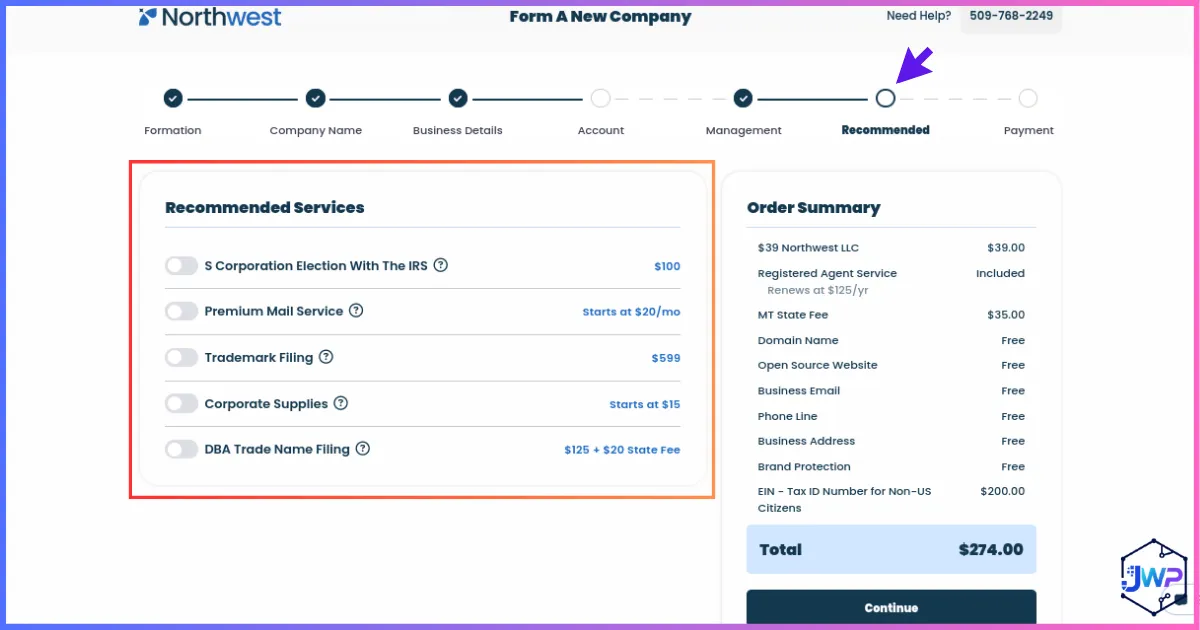
Decide which extras are useful
A registered agent is required. EIN preparation, certified copies, mail forwarding and annual report handling are service options whose usefulness depends on your situation. A US bank may ask for a certified copy later, but buying every extra immediately can raise the formation cost without changing eligibility.
Review, pay and save the approved filing
Check state fee, service charge, agent terms and each add-on against the final total. Keep the receipt. After state approval, download the stamped formation document, agent confirmation and operating agreement. The LLC exists only when the state accepts the filing, not when the payment page says the order was placed.
Obtain an EIN When the Business Is Managed from Australia
The EIN is the US federal tax identification number banks and payers commonly request. A state filing alone does not provide it. The IRS issues it without a fee. A foreign founder does not need to invent a Social Security number or ITIN to apply; follow the current Form SS-4 instructions for the responsible party and entity type.
Application method depends on the principal place of business, not the state of formation. If the business has no US legal residence, principal office, principal place of business or agency, the IRS says its online EIN system is unavailable. International applicants can call 267-941-1099 during the published US Eastern time hours or submit SS-4 by fax or mail. The current IRS page lists fax 304-707-9471 for applications sent from outside the US. Confirm numbers and hours immediately before using them.
- Wait for the accepted formation filing; copy the legal name and date exactly onto SS-4.
- Identify the real responsible party and decide whether that person has an SSN or ITIN. Follow the current line 7b instruction if neither exists.
- For a wholly foreign-owned disregarded LLC formed to meet section 6038A reporting, read the special line 9a guidance carefully.
- Choose phone, fax or mail based on your principal place of business and current IRS instructions.
- Save the signed SS-4, submission evidence and EIN confirmation; correct any name mismatch before opening accounts.
A complete fax application with a return fax number may receive a response in about four business days; mail may take about four weeks under IRS guidance, but processing can take longer. The international phone option may yield the number during the call if the authorized caller can answer the questions. Plan for delays, particularly when an Australian launch depends on US banking approval afterward.
US Banking, Cards and AUD/USD Payments
A valid LLC and EIN let you apply for an account. They do not guarantee acceptance. Bank and fintech eligibility depends on the owners’ country of residence, industry, transaction pattern, website, corporate documents and physical presence. Provider policies change, so ask whether they currently support an Australian-resident owner of a US LLC before paying for formation primarily to access one product.
| Route | Possible use | Questions to ask |
|---|---|---|
| US business bank or fintech | USD account details, domestic transfers, cards | Australian ownership, US address requirement, accepted business types |
| Australian bank | AUD operating account and local compliance | Whether it opens an account for a US LLC, required Australian registration, USD account availability |
| Cross-border platform | Receive or convert USD and AUD | Entity eligibility, source-of-funds checks, spread and transfer limits |
| Merchant processor | Cards, subscriptions and marketplaces | Country and legal-entity support, reserves, chargeback policy, tax forms |
Prepare a consistent file: certificate, EIN letter, signed operating agreement, IDs of ultimate owners, real Australian address, website, contract and sample invoice. Never use the agent’s statutory address as proof of a US operating office. If one bank declines the business, find out whether the problem is an address rule, industry rule, missing document or prohibited ownership structure before submitting the same inaccurate details elsewhere.
Compare the cost of collecting USD and moving it into AUD. A provider with no monthly fee can still charge through intermediary fees or a wide exchange spread. Keep both the USD amount and AUD value used in Australian books, with the exchange-rate source and date. Our guides to Wise and Payoneer explain common account features; their live eligibility terms govern.
Pie chart: illustrative use of US$1,000 in receipts
An illustrative cash-planning example, not tax rates or a recommended distribution.
US Income Tax and Information Returns
Do not equate a US LLC with automatic US tax. For federal income tax, a sole foreign individual normally owns a disregarded entity. The owner’s tax position depends on income type, source and whether the person is engaged in a US trade or business with effectively connected income. A multi-member LLC normally follows partnership rules and may need a Form 1065 and potentially withholding for foreign partners. A corporate election creates a distinct US taxpayer with a different return.
Service income: where the work is done
For personal services, the IRS generally sources income to where the services are physically performed. A Perth-based designer serving a Californian client may earn foreign-source service income for US purposes when all work occurs in Perth. A founder who works for two weeks in California should separately analyze those US workdays. The client’s address, payment currency and bank location do not by themselves source all service income to the US. See the IRS service-income sourcing guidance.
Goods, inventory, licensing, platform revenue, US real estate and employees follow different tests. If the LLC warehouses goods in the US, state sales tax and income-tax nexus can arise. US payroll, a sales office or a manager physically working in the US can materially change the return. Do not infer the result for a marketplace store from the example of a remote consultant.
Form 5472 and the pro forma Form 1120
A wholly foreign-owned US disregarded entity is treated as a separate corporation for certain information-reporting rules. It generally must file Form 5472 attached to a pro forma Form 1120 when it has a reportable transaction with its foreign owner or another related party. The category includes many contributions, distributions, formation-related payments and other monetary or nonmonetary transfers. A no-revenue LLC can still have a reportable owner contribution.
The IRS Form 5472 instructions state an initial $25,000 penalty for failure to file a required, complete return by its due date. For a calendar-year company, the regular Form 1120 due date is generally April 15 of the following year, subject to weekend and holiday adjustments; a timely Form 7004 may extend it. Keep a ledger of capital funding, expense reimbursements, owner withdrawals and related-party payments from day one.
The exact filing depends on the legal owner. A US LLC wholly owned by an Australian individual may be a foreign-owned domestic disregarded entity; an LLC owned by an Australian Pty Ltd may involve corporate-owner information and transactions; an LLC with two members generally enters partnership territory. Map the ownership before deciding which form applies.
| Event | Possible US consequence | Records to retain |
|---|---|---|
| Owner personally pays formation costs | Potential reportable capital contribution or related-party transaction | Receipt, invoice and contribution entry |
| LLC pays owner | Distribution, fee or loan repayment classification matters | Agreement, bank transfer and ledger |
| Consulting performed only in Australia | Generally foreign-source service income for US purposes | Contract, work-location and travel log |
| Services performed during US visit | US-source allocation and possible return | Dates, workdays and client invoices |
| Inventory in US fulfillment center | Sales tax, state nexus and federal income-tax issues | Warehouse contract, shipment and sales records |
BOI and state obligations
FinCEN’s August 2026 final rule exempts entities created in the US from federal Corporate Transparency Act beneficial ownership reporting. This does not remove bank identity checks, US state reports or IRS filings. Recheck FinCEN’s current BOI page if rules change. State income tax, sales tax, franchise charges, licences and payroll filings are separate from federal income tax.
What the Australia–US Tax Treaty Can and Cannot Do
Unlike many country pairs, Australia and the United States have an income-tax treaty with a later protocol. It allocates taxing rights and can limit withholding on particular categories of income for qualifying residents. It does not erase US Form 5472, determine a state’s tax nexus or force Australia to classify a US LLC as disregarded.
The treaty question is not simply whether an owner has an Australian passport. Benefits depend on tax residence, the income category, beneficial ownership, applicable limitation-on-benefits provisions and how the income is treated through a fiscally transparent entity. An Australian-resident individual and an Australian Pty Ltd may reach different outcomes. A US payer may require a correctly completed W-8BEN or W-8BEN-E, but an LLC’s US organization can complicate which person is considered the payee. Do not submit W-9 or a W-8 form solely because a platform suggests it.
US-source dividends, royalties, interest and business profits are separate treaty categories. A rate available for one category cannot be carried to another. If your US customer pays for services performed in Australia, start with sourcing and business-profits analysis; if it pays for a licence to use intellectual property, royalty rules may matter. Ask the payer what income it believes it is paying for and keep the contract consistent with reality.
Where tax is lawfully paid in both countries on the same income, Australia may allow a foreign income tax offset, subject to its limits and timing rules. An offset is not a blanket dollar-for-dollar refund. Record the tax actually paid, the relevant income and AUD conversion. A tax adviser can reconcile the two returns and treaty positions.
Australian Tax Treatment: The Crucial Classification Review
An Australian tax resident generally reports worldwide income, including income connected to a foreign business. Holding the proceeds in a US bank account does not by itself make them exempt in Australia. The ATO’s overseas-business guidance makes this principle clear and explains conversion of foreign amounts into AUD.
US disregarded status does not carry over automatically
Australian law can regard a US LLC as a company. If the detailed Division 830 foreign hybrid conditions are satisfied, it may instead be treated as a partnership for specified Australian income-tax purposes. The ATO explicitly identifies US LLCs as possible foreign hybrids, but the result depends on the facts and the statutory conditions for the relevant year. Single-member status does not let you skip the test. The ATO has considered disregarded single-member LLCs in its interpretation of the foreign hybrid requirements.
This difference changes the timing and character of amounts you report. Depending on classification, income may be attributed to a member as partnership income or appear as a payment or distribution from a company. Foreign tax offsets, losses and related-party deductions can work differently. If an Australian Pty Ltd owns the LLC, the analysis may also involve Australian corporate residency, controlled foreign company and hybrid mismatch rules. Do not copy a US accountant’s “disregarded” label into an Australian return without review.
Where are central management and control?
When strategic decisions are made from Australia, an overseas incorporated entity can raise Australian corporate residence questions. Merely holding an annual meeting overseas may not answer where control actually occurs. Identify who approves contracts, budgets, banking, IP transactions and hiring, and where they genuinely do so. An Australian-resident owner also has personal tax obligations independent of the entity’s classification.
Keep transaction-level records in USD and AUD. Document the conversion method, date, invoice, contract and tax withheld. For transfers between an Australian company and its US LLC, keep a written explanation of capital, loans, service fees, reimbursements and dividends rather than recording every movement as an informal owner draw. The same records support US Form 5472 and Australian reporting.
ASIC, ABN, Australian GST and Local Operations
A US LLC formed by an Australian does not automatically become an Australian company. Equally, a US certificate does not authorize it to ignore Australian registration law. ASIC says a foreign company carrying on business in Australia must register, and registration can result in an Australian Registered Body Number (ARBN). Whether a particular LLC and activity meet the statutory test requires fact-specific advice. If Australian operations will be substantial, compare registering the foreign company with using an Australian subsidiary or Pty Ltd from the start.
An Australian Business Number (ABN) is a different concept from a US EIN. The correct Australian registration depends on the operating structure, GST obligations and whether the enterprise is carried on in Australia. Do not put an individual’s ABN on invoices issued by a separate US LLC unless an adviser confirms that arrangement. If a US entity employs people in Australia, payroll, PAYG withholding and superannuation obligations may arise.
The usual Australian GST registration threshold is A$75,000 in relevant turnover, but the test depends on supplies connected with Australia and other rules. Cross-border B2B services, consumer digital products, goods imported into Australia and marketplace sales can each be treated differently. US state sales tax uses a different set of state nexus and product rules. Budget for both analyses if you sell into both markets.
An Australian Pty Ltd owned by the same people and a US LLC may be a cleaner group structure than asking one LLC to perform every domestic task. It also means two legal entities, intercompany agreements and tax returns. Use a simple diagram showing where customers, people, inventory, IP and banking sit before choosing that route.
Keep Two Compliance Calendars
The US and Australian filing years do not always align. Australian individual and company income years commonly run to 30 June, while many US LLC information returns follow a calendar year. Do not wait for a single annual bookkeeping session to reconstruct currency transfers and owner contributions. Record each month and set reminders well ahead of both countries’ deadlines.
| When | Task | Owner of task |
|---|---|---|
| At state acceptance | Save stamped articles, sign operating agreement, record starting capital | Founders |
| Before first invoice | Confirm EIN, bank eligibility, payer tax form, GST and Australian invoice requirements | Founder with advisers |
| Every month | Reconcile USD/AUD accounts, owner transfers, related parties and work location | Bookkeeper or owner |
| Wyoming anniversary month | File report and pay minimum licence tax if formed there | LLC or service |
| June 1 | Pay Delaware annual LLC tax if formed or registered there | LLC or service |
| Generally April 15 for calendar-year Form 1120 | File required Form 5472 with pro forma 1120 or arrange timely extension | US preparer |
| Australian income-tax cycle | Report foreign income, classification, GST and offsets as applicable | Australian adviser |
| Every year | Renew agent, review state nexus, ASIC status, treaty claims and beneficial-owner records | Founders and advisers |
Partnership, corporate, payroll and sales-tax elections create more deadlines than this baseline. An LLC with no revenue may still have state costs and a Form 5472 trigger from an owner contribution. Dissolving the company requires state cancellation and final returns; abandoning a bank account does not close the legal entity.
Radar chart: issues to examine by business model
Editorial planning scores, not measured data. Greater reach means an issue merits more attention.
DIY, Formation Service or Another Structure?
Direct filing can save a formation-service charge if you are comfortable with the state portal and have already appointed an agent. A service can simplify ordering, document storage and renewals. Neither substitute decides how the ATO treats the LLC. Before ordering, compare three structures: operate in your existing Australian capacity, form a US LLC alongside it, or use a US corporation if investors require it.
Direct filing suits you when
- Ownership is simple and the state choice is clear.
- You can manage an agent and annual dates.
- You have reviewed the US and Australian tax positions.
- You are comfortable handling state forms yourself.
Professional help is useful when
- Australian entities, trusts or several owners are involved.
- The LLC will own IP or US inventory.
- You need coordinated tax classification advice.
- A treaty claim or Australian foreign registration is uncertain.
Read our formation-service comparison and Northwest review for service features. If public-record privacy affects the choice, our anonymous LLC guide explains its limits; banks and tax authorities still require the real owners.
A US LLC can also be owned by an Australian Pty Ltd, but adding the parent does not automatically solve Australian residence or US filing questions. A Delaware corporation may be familiar to US venture investors, yet raises corporate tax, share and governance costs. A purely Australian business can often postpone forming a US entity until there is a specific commercial trigger.
Have a clear reason to form? Compare the service order with direct state filing, then review Australian tax treatment before you pay.
View Northwest LLC Formation →Three Australian Founder Scenarios
1. Remote developer in Melbourne
A developer writes software entirely in Melbourne for US customers. She considers a Wyoming LLC because one customer prefers a US contracting party. Her services are generally sourced to where she performs the work for US purposes; she still needs an Australian worldwide-income and foreign hybrid analysis. She asks the customer whether its purchasing system truly requires a US entity before paying for formation. If she forms one, she logs her work location and owner-funded setup costs.
2. Consumer product brand in Brisbane
A brand buys stock overseas, stores it at a US fulfillment center and sells to American consumers. The physical US inventory raises state registration, sales-tax and possibly federal income-tax questions. The Australian owners also need to decide whether the brand’s IP, marketing and management remain in Australia and how intercompany charges are documented. A low-cost New Mexico filing alone will not settle taxes in the warehouse state.
3. Sydney Pty Ltd forming a US sales entity
An Australian company wants a US sales operation with local staff. It compares a subsidiary LLC taxed as a corporation with a C corporation, models both countries’ returns and plans an intercompany service agreement. The Pty Ltd’s directors document where strategic decisions occur. The business checks payroll, transfer pricing, ASIC and GST questions before customer contracts move to the new entity. The most economical filing fee is a small part of the decision.
- ☐ Define the commercial reason for a US entity and compare an Australian Pty Ltd.
- ☐ Map owners, trust or company interests, assets and management location.
- ☐ Obtain a preliminary Australian foreign hybrid, residence and GST review.
- ☐ Select the US state based on real operations and ongoing cost.
- ☐ Search the name and appoint a qualified registered agent.
- ☐ File the state formation document and keep the accepted copy.
- ☐ Sign an operating agreement and enter each owner contribution in the ledger.
- ☐ Obtain the EIN through the IRS channel matching the principal business location.
- ☐ Verify business bank and processor support for Australian owners.
- ☐ Track US/Australian work location, USD/AUD conversion and related-party transfers.
- ☐ Review Form 5472, treaty, state tax, ASIC and Australian income tax.
- ☐ Schedule state fees, agent renewal and tax returns in both countries.
Frequently Asked Questions
Can an Australian citizen own 100% of a US LLC?
Do I need to visit the United States?
Do I need an SSN or ITIN?
Is a US LLC automatically tax-free for an Australian resident?
Does Australia treat every US LLC as a partnership?
Which US state is best for an Australian remote founder?
What is the Delaware LLC annual tax?
Can I obtain an EIN from Australia for free?
Does an LLC guarantee a US bank account or Stripe?
Does the Australia–US treaty eliminate Form 5472?
What if my US LLC has no revenue?
Do I need to register the LLC with ASIC?
Will the LLC need Australian GST?
Do US-formed LLCs currently file federal BOI reports?
Can I close the LLC if I stop using it?
Final Thoughts
Forming a US LLC from Australia is administratively manageable: choose a state, appoint an agent, file, sign the operating agreement, obtain an EIN, and apply for financial services. The real work is deciding whether the structure improves your business after counting US and Australian compliance. Australia’s foreign hybrid rules and the two countries’ different tax classifications deserve attention before the first customer payment.
Price two years, confirm the intended bank supports your actual owners, and retain a clean record of capital and transfers. If the LLC will hold inventory, IP, employees or a US office, obtain coordinated advice at the start. If the business is wholly Australian and simply bills US clients, an Australian structure may be enough until a concrete US requirement arises.
Sources & Research Notes
Primary official sources reviewed for this guide in September 2026. Fees, administrative practice and individual tax outcomes can change.
- Wyoming Secretary of State LLC Articles: $100 base filing and annual report timing.
- Delaware Division of Corporations: $400 annual LLC tax and June 1 due date.
- New Mexico Secretary of State LLC filing: $50 Articles of Organization application fee.
- IRS Form SS-4 instructions: international EIN routes and responsible-party rules.
- IRS Form 5472 instructions: foreign-owned disregarded entities, reportable transactions and penalties.
- IRS service-income sourcing: physical work location generally controls.
- IRS Australia treaty documents: convention and later protocol.
- ATO company status instructions: Division 830 foreign hybrid discussion.
- ATO doing business overseas: Australian worldwide income and foreign income records.
- ASIC foreign companies: registration when carrying on business in Australia.
- ATO GST registration: threshold and registration framework.
- FinCEN BOI page: August 2026 final rule for US-created entities.