How to Form a US LLC from India A complete guide for Indian founders, freelancers and businesses
An Indian founder can generally own a US limited liability company without US citizenship, a Social Security number or a visit to America. The state filing is straightforward; the hard part is coordinating it with India’s overseas-investment, tax and reporting rules. This guide walks through the LLC order, EIN, banking, US and Indian taxes, treaty questions, costs and a practical compliance plan for founders in Bengaluru, Mumbai, Delhi, Hyderabad or elsewhere.
Quick Answer: How to Form a US LLC from India
An Indian citizen or India-based business can generally form a US LLC remotely. Define the business reason, check whether the intended owner can lawfully fund a foreign entity from India, choose the US state, appoint an in-state registered agent, file the formation document, sign an operating agreement, get an EIN, apply for banking, and maintain both US and Indian records.
India-specific work comes before the US checkout. A person resident in India may need to follow the RBI’s Overseas Investment framework and a bank’s authorised-dealer process for funding a foreign entity. Indian tax residence determines foreign-income and foreign-asset reporting; an India-based business may have GST, corporate, transfer-pricing or permanent-establishment questions. A US LLC does not automatically shield its income from Indian tax or make a USD balance exempt.
For a wholly foreign-owned single-member US LLC, owner contributions, reimbursements and distributions may trigger Form 5472 with a pro forma Form 1120 even if the LLC has no revenue. US income tax is a separate question involving classification, source of income and actual US activity. The US–India treaty may help with specific income categories for an eligible resident, but it does not erase state fees, Form 5472 or Indian reporting.
Table of Contents
- Is a US LLC right for you?
- Ownership and LLC basics
- India-side decisions before filing
- Choose a US state
- Costs and charts
- Prepare your documents
- Seven-step formation walkthrough
- Get an EIN
- Banking and INR–USD payments
- US income tax and Form 5472
- US–India treaty and withholding
- Indian income tax, GST and reporting
- Compliance calendar
- Alternatives and common errors
- Founder scenarios
- Launch checklist
- Frequently asked questions
Should a Founder in India Form a US LLC?
A US LLC is a contracting and ownership vehicle. It can be useful when an American partner wants a US entity, the business will have actual US operations, or a specific customer procurement process requires a domestic counterparty. It also creates an additional legal and tax layer. An Indian freelancer who only serves overseas clients from India may already be able to invoice through an Indian sole proprietorship, LLP or private limited company.
Do not form simply because a social-media post says a US LLC gives everyone tax-free USD income or a guaranteed payment account. Ask the intended customer or provider exactly what legal entity they require. A US bank may still decline an India-resident owner or a particular line of business under its current policy. The business also needs a lawful way to contribute capital and report income in India.
Compare the complete structure. An Indian exporter may already use a local entity, GST export procedures and inward remittance documents. Adding an LLC can mean a second accountant, registered agent, annual US information return and related-party books. If investors require venture equity, a Delaware C corporation may be more suitable than an LLC. A targeted legal and tax memo before formation is often less costly than restructuring later.
US LLC Basics and Indian Ownership
US states generally permit foreign individuals and companies to own all of an LLC’s membership interests. State formation usually requires a name, filing form and registered agent, but not a US co-owner, US visa or Social Security number. You can manage ownership from India. Physical work in the United States is a different immigration matter; an LLC certificate itself grants no US work authorization.
| Term | Plain meaning | Why it matters in India |
|---|---|---|
| Articles of Organization | State document that creates an LLC | Keep the accepted copy for banking and Indian investment records. |
| Registered agent | In-state recipient of legal notices | An Indian home or virtual mailbox cannot replace it. |
| Operating agreement | Ownership and management rules | Important for cofounders and evidence of ownership. |
| EIN | Federal business tax identifier | Direct IRS application costs nothing. |
| Disregarded entity | Default US income-tax status of a single-owner LLC | Indian classification requires its own analysis. |
| Foreign qualification | Registration in another US state where business occurs | Wyoming filing may not suffice for a US warehouse elsewhere. |
An LLC’s liability shield generally separates business obligations from owners’ personal assets, subject to state law and ordinary limits. It does not protect an owner who personally guarantees a debt or commits fraud. Maintain a separate ledger and account, sign contracts in the LLC’s legal name, and document every transfer to or from members. Those records also support Form 5472 and Indian disclosures.
A single-member LLC is normally disregarded for US federal income tax unless a corporate election is made. A multi-member LLC normally defaults to partnership tax status. Elections, corporate parents and changing owners can alter the forms required in both countries. Do not treat US tax classification as an automatic answer to how India taxes the same foreign entity or payments from it.
Three India-Side Questions to Settle Before Filing
1. Who is the owner and where are they resident?
An Indian citizen living abroad is not automatically in the same regulatory position as an individual resident in India. Likewise, an Indian private limited company investing overseas is not the same as its director investing personally. Map legal ownership, tax residence, beneficial owners and the source of capital before opening a US formation checkout. If a resident individual, Indian company or LLP will own the LLC, ask an adviser which RBI Overseas Investment rules apply to that owner and transaction.
2. How can capital leave India?
The Reserve Bank of India’s Overseas Investment directions and Liberalised Remittance Scheme framework govern relevant resident transactions. The classification of an investment, the investor, bank documentation and subsequent reporting matter. A small formation fee paid by card and an equity contribution to a foreign LLC are not necessarily identical transactions. Speak to the authorised-dealer bank before sending meaningful capital or using an informal third-party payment route.
The RBI directions include reporting requirements for certain overseas direct investments, including annual performance reports in applicable cases and exceptions. Whether an LLC membership interest fits a particular category, how a resident individual may invest, and the documentation for later disinvestment should be checked under the current rules. Avoid relying on an old quoted remittance limit or a generic “LLC is allowed” statement.
3. Where will the activity and management be?
If the founder, developers, contracts and strategic decisions remain in India, an American filing does not move those facts abroad. India may tax the resident owner or Indian company, and a foreign entity managed from India can raise place-of-effective-management or business-presence questions. Indian GST can also matter when services are exported or supplied between related entities. Decide who really sells the service, owns intellectual property, invoices the customer and bears the business risk.
Choose a Formation State That Matches the Business
State choice should follow actual US operations. If the LLC will have US employees, premises or inventory, start with the state where those activities occur. A Wyoming LLC with a warehouse in California may still need California registration and taxes. For a genuinely remote service company managed from India with no US physical footprint, compare state filing and annual charges, agent availability and any investor requirement.
| State | Base formation fee | Routine annual state charge | Potential fit | Watch for |
|---|---|---|---|---|
| New Mexico | $50 | No routine LLC annual report | Simple remote business focused on state cost | Agent, tax and licence obligations remain. |
| Wyoming | $100 | Annual report licence tax, $60 minimum | Remote founder wanting predictable state maintenance | Online fee and Wyoming assets can increase cost. |
| Delaware | Illustrative $110; confirm current filing fee | $400 annual LLC tax, due June 1 | Specific investor, legal or contract reason | LLCs pay annual tax though they do not file corporation reports. |
| US operating state | Varies | Varies | Real staff, inventory or premises | Second-state registration can duplicate cost. |
Wyoming’s official Articles list a $100 filing fee. Delaware’s current Division of Corporations instructions state a $400 annual LLC tax by June 1; many older guides still say $300. Check the current state portal for exact fees. A state with no income tax does not make the LLC’s federal or Indian income tax disappear.
Column chart: illustrative base state filing fees (USD)
State fee examples; *confirm Delaware formation charge at filing. Excludes processing and service fees.
Horizontal bar chart: routine annual state charges (USD)
Routine state report or LLC tax only. Agent, US activity tax and Indian compliance are excluded.
Budget for Formation and Ongoing Compliance
Separate initial formation from keeping a cross-border entity in good standing. The filing may be cheap, but a US registered agent, a US preparer familiar with foreign-owned disregarded entities, Indian tax advice, and bank conversion charges can exceed the state fee. Price the first two years before purchasing optional add-ons.
| Item | Planning amount | When | Note |
|---|---|---|---|
| State filing | $50 NM; $100 WY; DE fee to confirm | Once | Use official state schedule. |
| Formation service | Illustrative $39 plus state fee | Once | Check live Northwest checkout. |
| Registered agent | Often $100–$200 | Annual | First year may be bundled. |
| Direct IRS EIN | $0 | Once | Paid assistance is optional. |
| Wyoming annual report | $60 minimum | Annual | Potentially higher based on assets. |
| Delaware LLC tax | $400 | Annual | Due June 1. |
| US and Indian advisers | Quote required | Setup and ongoing | Scope should cover both systems. |
| USD–INR conversion | Provider-specific | Ongoing | Compare fees and exchange spread. |
An illustrative Wyoming checkout is $139 if a service charges $39 and the state filing is $100, before any processing charge or add-on. That is a planning example, not a current price quote. The cost of getting the Indian ownership and remittance treatment wrong can be much larger than the amount saved by ordering quickly.
Donut chart: illustrative $139 Wyoming formation checkout
Illustration only. Agent renewal, online fees and adviser costs excluded.
Line chart: minimum cumulative state charges
State-level illustration only. Delaware uses an illustrative $110 formation fee and current $400 annual LLC tax; verify the formation fee live.
Compare the actual checkout with the state fee and next year’s registered-agent renewal before ordering.
Review Northwest Formation Options →Prepare Your LLC and India Documentation
Gather the proposed legal name, state choice, owner information, management structure, actual Indian operating address, business description and email. Search the state name database; then separately check trademark conflicts. Decide whether the owner is an Indian resident individual, an Indian company, an overseas resident or several members. That choice can change the RBI process, tax return and bank paperwork.
- Identity: valid passport or accepted ID, real residence and consistent spelling across documents.
- Ownership: list beneficial owners, percentages, contributions and decision-makers.
- Business proof: website, contracts, sample invoices and a clear explanation of what customers buy.
- Addresses: separate the registered agent, mailing address, actual principal office and each owner’s residence.
- Investment file: obtain authorised-dealer guidance, banking instructions and required filings before remitting capital.
- Tax file: record who invoices customers, performs work and owns IP; review GST and income-tax treatment.
The registered agent must have a qualifying physical address in the formation state. Ask how quickly legal mail is scanned, who receives renewal notices and what happens if your payment method fails. An agent’s office does not become your US workplace or proof of residence. Keep service account credentials under the legal owners’ control.
Seven Steps: Form a US LLC from India with Northwest
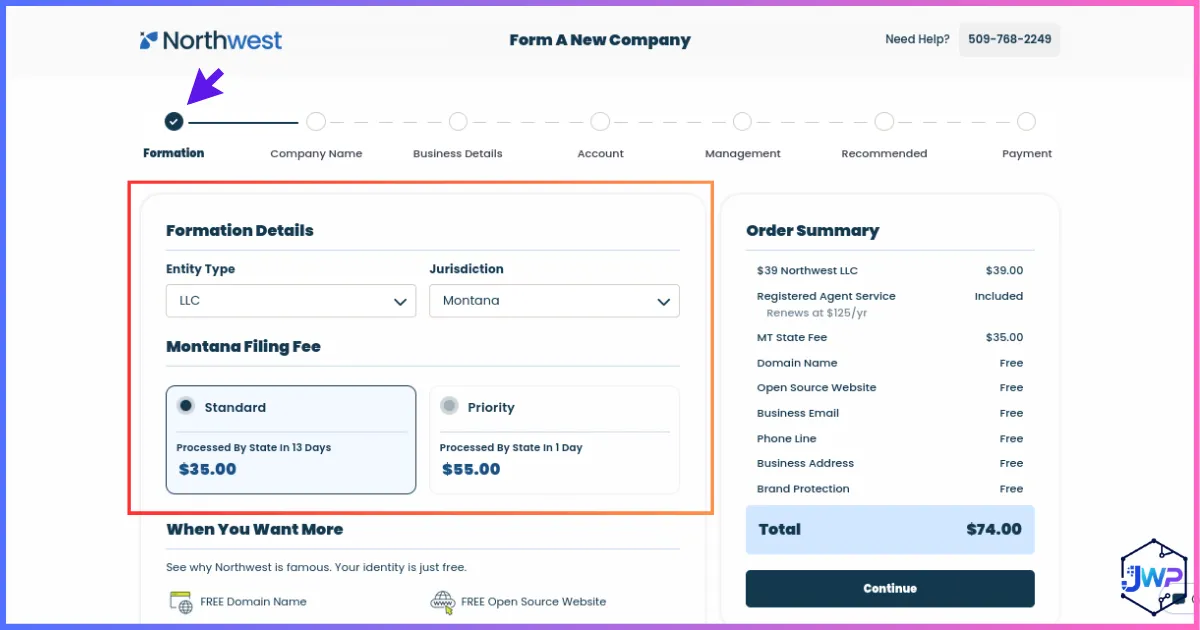
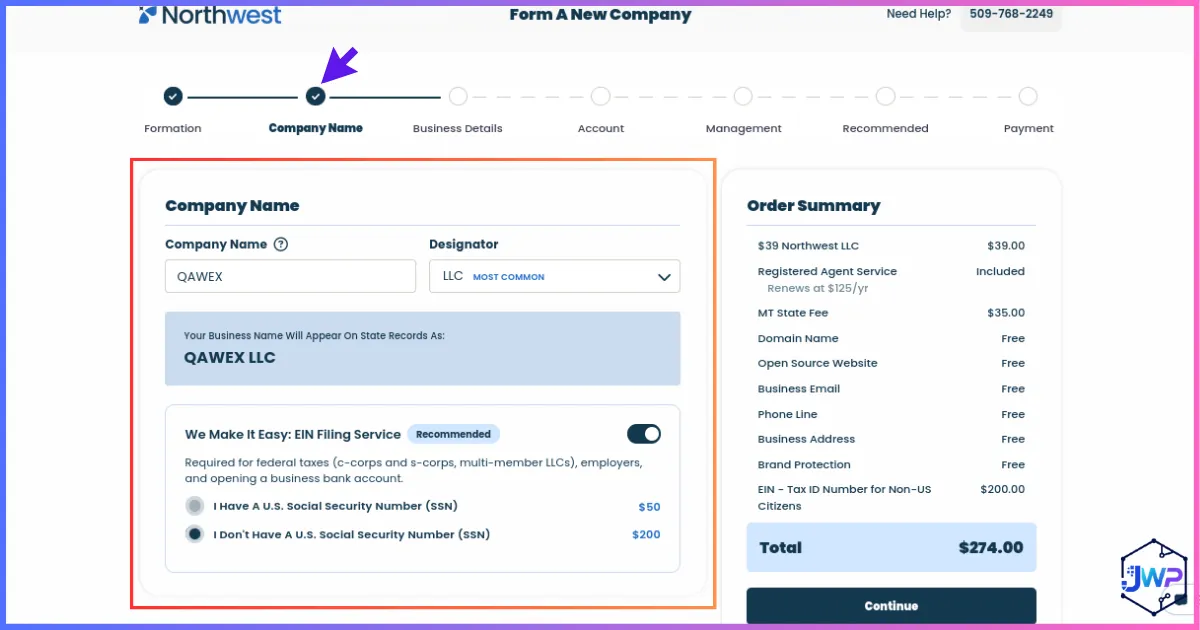
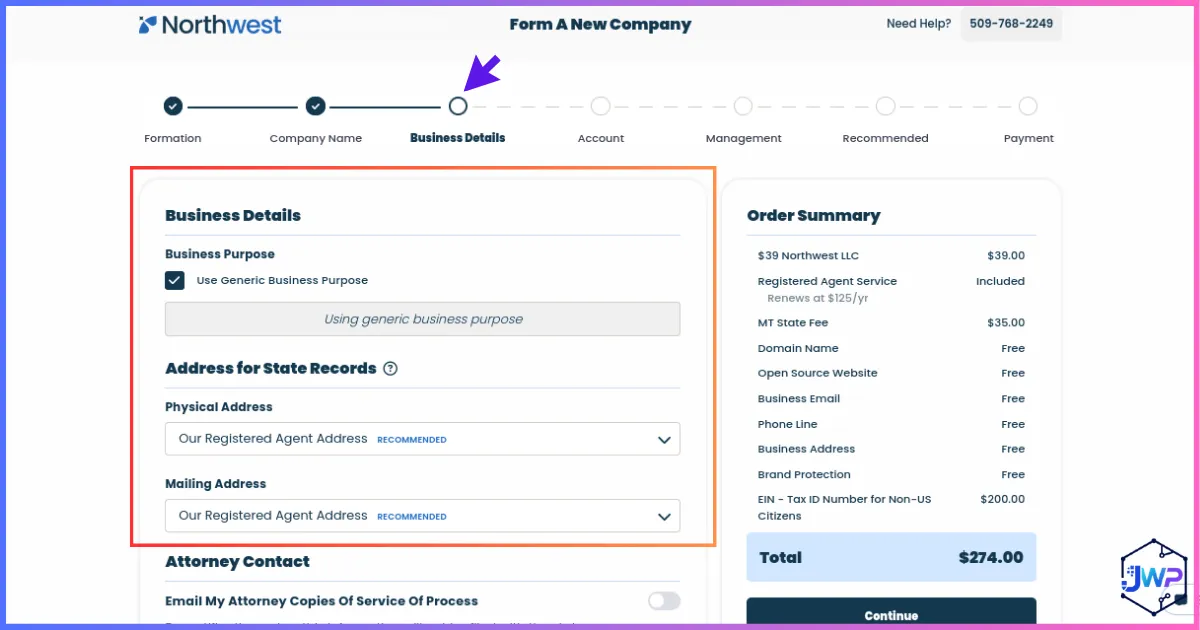
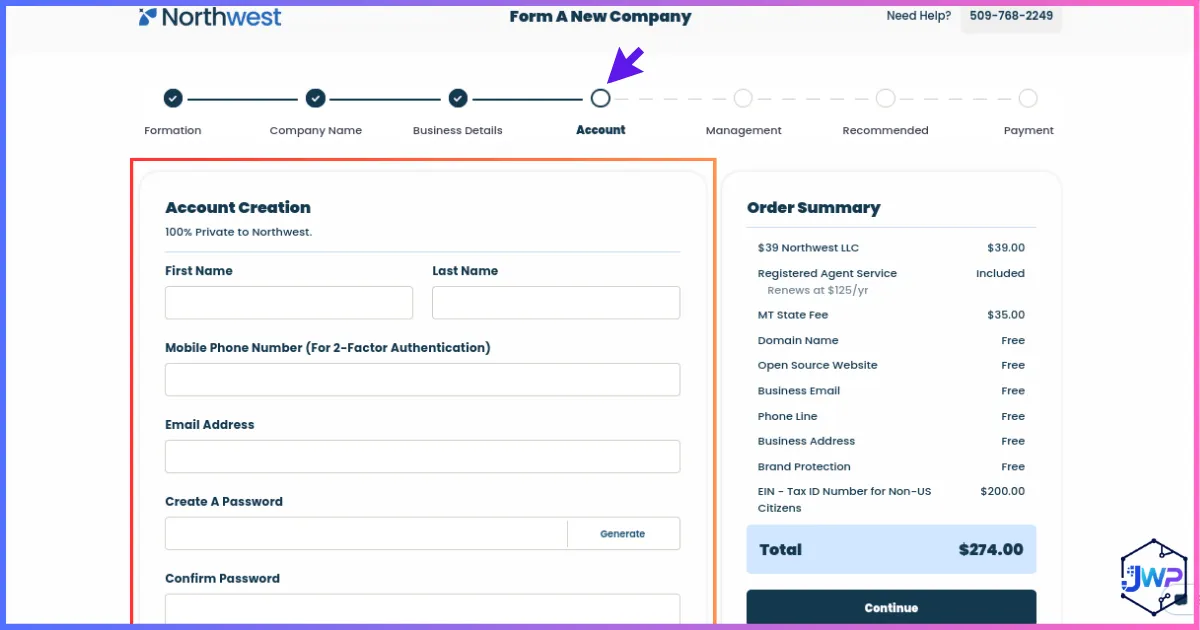
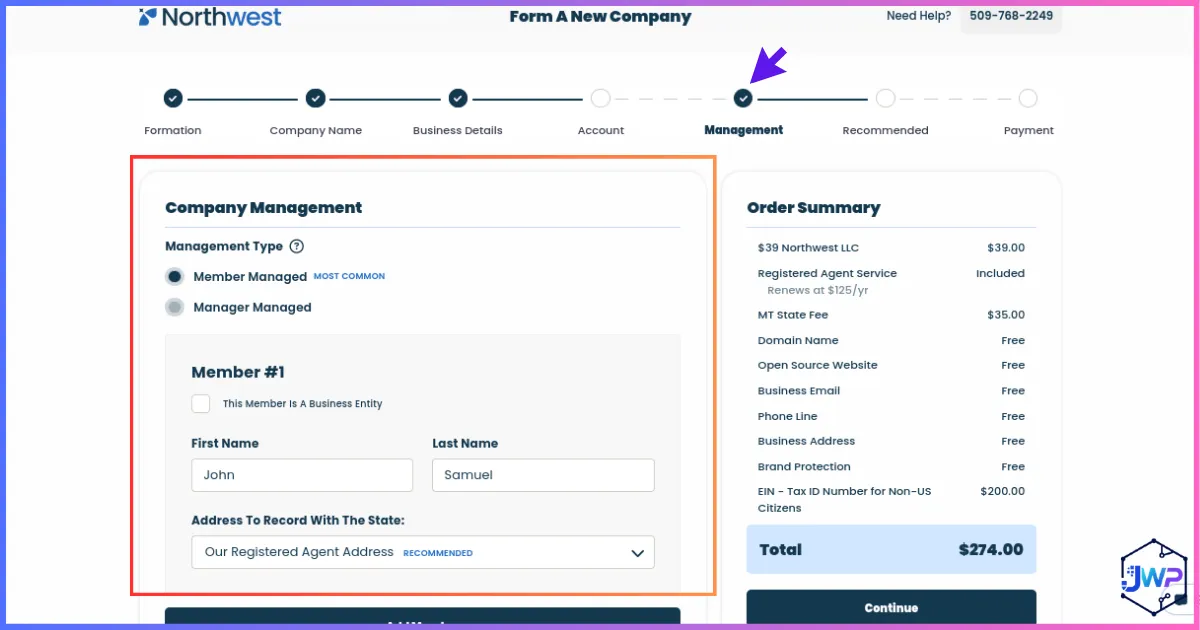
The seven screenshots show an illustrative formation-service sequence. Screens and prices can change; read the live order before payment. You may instead file with the state directly and appoint an agent yourself. A formation service can submit a document, but it cannot decide your Indian investment classification or guarantee bank approval.
Choose LLC and formation state
Select limited liability company and the state based on real US operations. If inventory, employees or an office will exist in America, discuss the relevant operating state. If all work happens from India and no US physical footprint exists, compare New Mexico, Wyoming and Delaware on costs and business needs.
Enter the exact legal name
Use the chosen state’s required LLC designator. Match contracts, invoices and eventual EIN application to the accepted spelling. A paid EIN assistance option may appear; the IRS does not charge for a direct application.
Give accurate business details
Explain whether you sell software, consulting, design, goods or licences. Use the real Indian business location where work and management occur. Do not use the statutory agent address to claim a US operating office.
Create a secure account
Your dashboard may hold approved documents, legal mail and renewal notices. Use an email controlled by the owner, secure the login and keep a backup. If someone else pays the order, ensure ownership details still name the actual owner.
Record managers and members
A solo founder often chooses member-managed unless a specific arrangement needs a manager. Enter each legal owner accurately. If an Indian private company or multiple founders own the LLC, finish the ownership and contribution agreement before checkout.
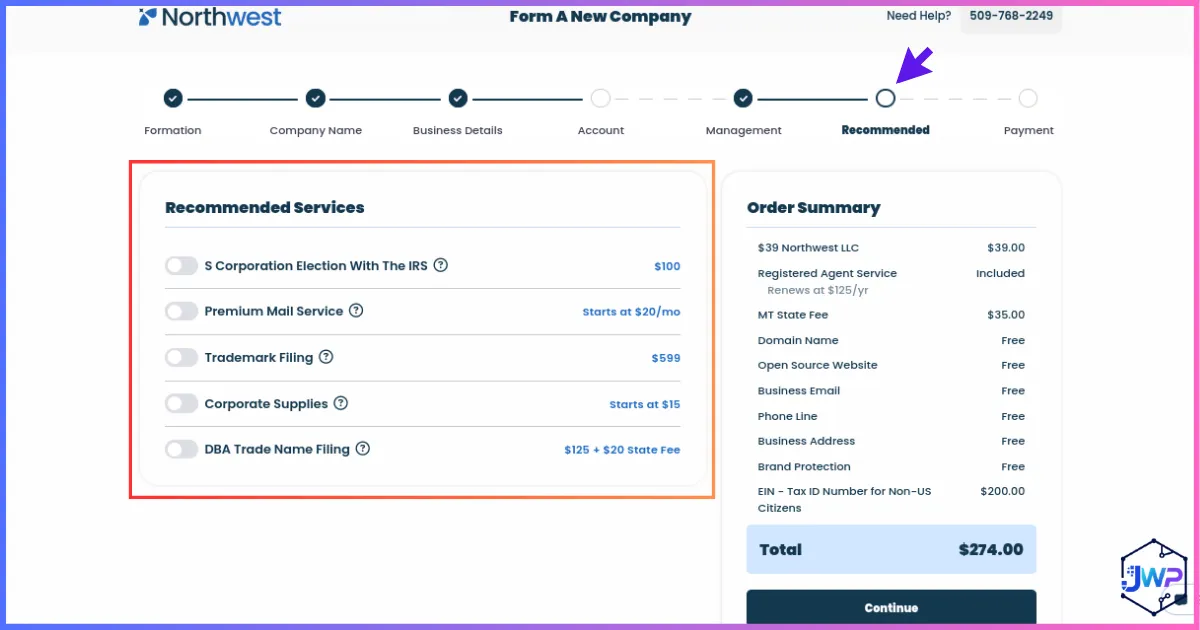
Review optional services
A registered agent is required; certified copies, mail forwarding, EIN assistance and annual-report handling can be optional. Check whether a bank or customer actually needs an extra document before adding it, and ask which services renew each year.
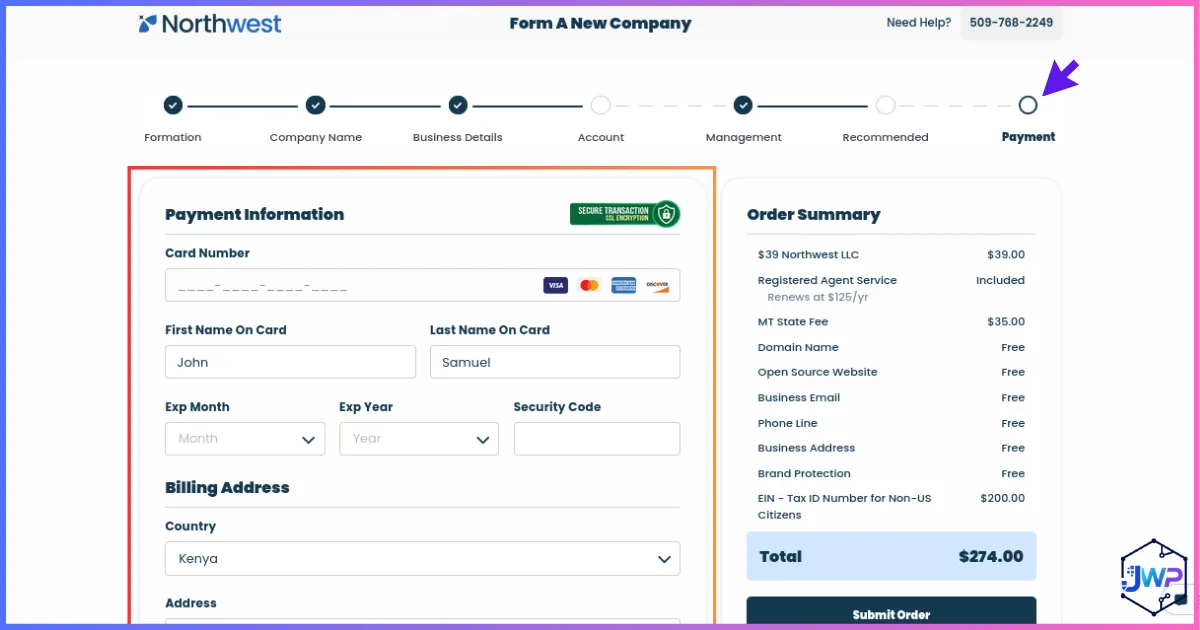
Review total, pay and save evidence
Compare the final total with the state fee, service fee, agent terms and each add-on. Keep the receipt and, once the state approves, download the stamped Articles or Certificate of Formation and agent confirmation. Payment alone does not create the LLC.
Obtain an EIN Without a US SSN
The Employer Identification Number is the LLC’s federal tax identifier. Banks, processors, payers and tax forms commonly request it. The IRS charges nothing for a direct application. Your principal place of business, not merely the state of incorporation, determines whether the online route is available. A Wyoming LLC managed from India can still have its principal office in India.
The current IRS Form SS-4 instructions say an applicant with no US legal residence, principal place of business, principal office or agency cannot use the online EIN application. International applicants can apply by phone, fax or mail. The current IRS page lists 267-941-1099 for the international phone line and 304-707-9471 for fax from outside the US. Verify the published number, hours and address immediately before applying.
- Wait for the accepted state filing and copy the LLC name and formation date exactly onto Form SS-4.
- Identify the real responsible party, normally an individual who controls the business. Follow current line 7b guidance if that person has no SSN or ITIN.
- Read line 9a carefully if the LLC is wholly foreign-owned and disregarded for US tax; the IRS provides a special entry for certain section 6038A reporting applicants.
- Apply once through the appropriate international channel or appoint a properly authorised third-party designee.
- Save the signed SS-4, submission record and IRS EIN notice, and resolve any spelling mismatch promptly.
The IRS says a complete fax with a return fax number may be processed in about four business days and mail in about four weeks, but delays happen. A phone call may provide the number sooner if the authorised caller can answer the questions. Do not promise clients a launch date based only on an estimated EIN time.
Business Banking and INR–USD Transfers
A formed LLC and EIN make you eligible to apply to some US banks and fintechs; they do not guarantee an account. Provider country lists, address requirements and risk policies change. Before forming solely to access a specific provider, confirm it currently supports an India-resident owner, the proposed legal owner and your actual business activity.
| Route | Potential use | Verify first |
|---|---|---|
| US bank or fintech | USD details, US domestic transfers, cards | India-resident owners, US business address rules and accepted industries |
| Indian authorised-dealer bank | Lawful capital remittance and local records | Investment classification, forms and supporting documents |
| Cross-border platform | Client collections and currency conversion | Entity eligibility, payout route, spread and limits |
| Merchant processor | Cards, marketplaces and subscriptions | Country, beneficial owners, product type and reserve policy |
Prepare the state-approved certificate, EIN confirmation, signed operating agreement, passport or other ID, actual Indian residence, ownership chart, website, contracts and expected customer payments. If an Indian private company owns the LLC, the provider may request parent-company documents and ultimate owners. Never call a registered agent’s address your own US operating office.
Ask the Indian bank how it wants outward capital, inbound distributions, service receipts and related-party invoices documented. These are not identical payment categories. Compare the cost of receiving US$1,000 and using it in INR: incoming and intermediary bank fees, conversion spread, transfer cost and tax reporting. Our guides to Wise and Payoneer explain general features; live provider eligibility governs.
Pie chart: illustrative use of US$1,000 business receipts
Illustrative budget, not a statistic, tax rate or recommended distribution.
US Tax and Information Returns for Indian Owners
Federal income-tax treatment starts with the LLC’s classification. A sole-owner disregarded LLC generally passes its income to its owner for US income-tax purposes. A multi-member LLC generally files as a partnership by default; a corporate election creates a separate US taxpayer. Income source and actual US trade or business activity determine whether US tax and returns may arise.
Where services are physically performed
The IRS generally sources personal-service income where the work is physically done. A developer coding entirely in Hyderabad for a US client generally earns foreign-source service income for US purposes; the customer’s address, the USD invoice and the LLC’s US bank account do not move the work. Services performed while visiting the US may create US-source income that needs allocation. See the IRS service-income sourcing guidance.
Goods, inventory, royalties, software licences and real estate do not necessarily follow the simple services example. A US warehouse or employee can create state tax and possibly federal tax issues. Keep a work-location log, travel days, contracts and invoices. The question is factual; do not rely on a blanket claim that foreign owners owe no US income tax.
Form 5472 with pro forma Form 1120
A wholly foreign-owned US disregarded LLC is treated as a separate entity for specified information-reporting purposes. It generally files Form 5472 attached to a pro forma Form 1120 when it has reportable transactions with its foreign owner or another related party. Owner capital contributions, distributions, formation costs and expense reimbursements can be reportable, even when there are no customer sales.
The IRS Form 5472 instructions specify an initial $25,000 penalty for failure to file a required, complete return on time. The form follows the Form 1120 due date; for a calendar-year filer this is generally April 15 of the following year, with a valid extension potentially available through Form 7004. Review every related-party transaction and retain a ledger from the day the company forms.
| Event | Potential US consequence | Evidence to keep |
|---|---|---|
| Indian owner pays filing fee | May be an owner contribution or related-party transaction | Receipt, source bank statement and ledger entry |
| LLC pays owner | Distribution, fee or loan repayment classification | Agreement, bank transfer and tax memo |
| Work performed in India | Generally foreign-source services for US purposes | Contract and work-location record |
| Work performed partly in US | Possible US-source allocation and return | Travel dates, workdays and invoices |
| Inventory stored in US | Possible sales-tax and income-tax nexus | Warehouse and shipment records |
FinCEN BOI and state reporting
FinCEN’s August 2026 final rule exempts US-created entities from federal Corporate Transparency Act beneficial ownership information reporting. That does not remove bank identity checks, state obligations or IRS forms. Recheck FinCEN’s current BOI page as rules can change. US payroll, sales tax and foreign qualification have separate triggers.
US–India Tax Treaty and Withholding Forms
India and the US have an income-tax treaty. It can allocate taxing rights and reduce withholding for specific income categories when the claimant qualifies. It does not grant every Indian citizen a zero rate. Treaty residence, beneficial ownership, the payment’s legal character and the treaty’s conditions must be checked.
An Indian citizen living in another country may not be an Indian treaty resident. A US LLC that is disregarded for US tax can complicate who is treated as earning the payment. If the payer asks for Form W-8BEN, W-8BEN-E or W-9, identify the actual payee under the relevant rules before completing a certificate. Merely being US-organized is not a reason to send W-9 without considering the LLC’s tax classification.
US-source dividends, royalties, interest and certain other income may face withholding under domestic law unless a specific treaty or statutory provision changes it. Service fees require a separate sourcing analysis; a software licence can have different treatment from development services. Do not put a treaty percentage in a customer contract before an adviser reviews the specific article and facts. The IRS withholding guide and the treaty text are the starting sources.
If both countries tax the same income, India may allow a foreign tax credit under its rules. Timing, taxpayer identity and supporting documents matter. A tax paid by the LLC or withheld from the owner may not automatically match the person claiming credit in India. Keep payer statements, US returns and INR conversions for an Indian tax professional to reconcile.
Indian Income Tax, Foreign Assets, GST and Company Presence
Resident income and foreign-asset reporting
An Indian resident and ordinarily resident person’s worldwide income can be within Indian income tax. A nonresident or resident-but-not-ordinarily-resident person may have different scope, so citizenship alone is not enough. Holding money in a US bank does not decide Indian tax residence or exempt income earned while working in India. Use the actual residency status for the year and record when services were performed.
The Income Tax Department’s Schedule FA resources explain foreign asset and income disclosure and caution against using return forms that omit required schedules. A US LLC membership interest, signing authority or foreign account may need disclosure by a person who is required to complete Schedule FA. The details and exceptions depend on taxpayer status and the return year; ask an Indian preparer to map the ownership and account documents accurately.
GST, exports and who supplies the customer
If work is performed by an Indian person or company, examine Indian GST and export-of-services rules before assuming that invoicing through a US LLC changes the supplier. Conditions for export treatment, place of supply and permitted payment must be met. A related Indian company providing development or support services to the LLC may need an agreement and invoices at defensible prices. The CBIC guidance on export refunds and Letters of Undertaking is useful when a registered Indian supplier exports services without paying integrated tax, but the exact facts control.
Management, related parties and transfer pricing
Where key decisions are made can influence whether a foreign company has an Indian tax residence or business presence issue. If founders, staff and management are in India, a US formation certificate does not move those activities to America. An Indian company billing or funding its US affiliate may need transfer-pricing and other international-transaction documentation. Model IP ownership, staff contracts and customer invoicing together rather than assigning all profits to the entity with the most convenient bank account.
Convert USD amounts into INR using appropriate tax and accounting methods, preserve the underlying foreign-currency figures and reconcile bank settlements to invoices. Keep records of the authorised-dealer route for outward investment and later repatriation. India and US tax years and record classifications may differ, so a shared transaction ledger is valuable.
Compliance Calendar for a US LLC Owned from India
Set reminders at least a month before each deadline. An American agent or formation service may email reminders, but the duty remains with the LLC and owners. India’s financial year and common US calendar-year filing schedule do not align, so reconcile books monthly rather than trying to recreate transactions once a year.
| When | Task | Who handles it |
|---|---|---|
| At formation | Save approved articles, operating agreement and investment records | Founder |
| Before funding | Confirm authorised-dealer route and applicable ODI/LRS documents | Founder and Indian adviser |
| Before invoicing | Confirm EIN, payer form, bank, GST and contracting party | Founder with advisers |
| Monthly | Reconcile USD and INR records, owner transfers and work location | Bookkeeper or founder |
| Wyoming anniversary month | File annual report and pay licence tax if applicable | LLC or service |
| June 1 for Delaware LLC | Pay annual LLC tax | LLC or service |
| Generally April 15 for calendar-year 1120 | File required Form 5472 with pro forma 1120 or extension | US preparer |
| India’s tax and RBI cycle | Review foreign income, assets, GST and investment reporting | Indian advisers |
| Every year | Renew agent, review state nexus, bank terms and entity structure | Founder |
Additional dates apply if the LLC has multiple members, a corporate tax election, US payroll, inventory, state sales tax or an Indian affiliate. RBI overseas-investment reporting can have its own timeline and exceptions. Closing an unused LLC requires state dissolution and final tax work; ceasing to use its bank account is not a legal closure.
Radar chart: areas to review by business model
Qualitative editorial planning scores, not measured data. More reach means a subject requires closer review.
DIY, Formation Service or a Different Entity?
Direct state filing may save a service fee if you understand the state form and appoint your own agent. A formation service offers a guided order, document dashboard and possible agent bundle. Neither route answers Indian ODI, tax or GST questions. Compare the total first two years, including agent renewal and professional fees, before choosing.
Direct filing may suit you when
- One clear owner and a simple business purpose.
- You already selected and priced an agent.
- The US state and Indian funding route are settled.
- You can manage annual deadlines yourself.
Get tailored help when
- An Indian company, LLP or trust will own the LLC.
- Several members need a negotiated agreement.
- US inventory, staff or IP complicate taxes.
- ODI, GST, treaty or entity classification is uncertain.
Our formation-service comparison and Northwest review help compare administrative features. If public-record privacy matters, see the limits in our anonymous LLC guide; banks, the IRS and Indian authorities may still need ownership information.
Some founders are better served by an Indian private limited company or LLP that sells to US customers. Others need a US subsidiary owned by an Indian company, or a Delaware C corporation if venture equity is the goal. The right structure depends on the customer requirement, where work and management occur, the planned capital route and the full tax cost. Do not elect corporate taxation for the LLC or transfer IP without modeling the consequences in both countries.
Ready to compare a filing service? Check the live state fee, annual agent renewal and every optional item on the final order screen.
View Northwest LLC Formation →Three Indian Founder Scenarios
1. Solo consultant in Bengaluru
A consultant works entirely in Bengaluru for US customers. She considers a Wyoming LLC because a large customer prefers a US counterparty. Before filing, she asks the customer whether an Indian entity is actually unacceptable, checks the authorised-dealer route for owning and funding the LLC, and obtains an Indian tax view. If she forms, she records her work location, owner-paid formation costs and all later transfers. The US service-income sourcing starting point is where she performs the work, while Indian income reporting remains a separate matter.
2. Indian private company with a US warehouse
An Indian brand wants a US LLC to hold stock in an American fulfillment center. It needs more than a cheap state filing: inventory can trigger US state sales tax, state registration and federal income-tax questions. The Indian parent considers ODI documentation, transfer pricing, GST, customs and intercompany sales agreements. It may choose an LLC or corporation after comparing tax classification and investor plans.
3. Indian citizen resident in Singapore
A founder with Indian citizenship but Singapore tax residence is not automatically taxed or regulated as a person resident in India. His actual residence, source of funds and ownership structure matter for both countries. He should not claim an India–US treaty benefit merely from nationality. He describes his real Singapore address to the bank and asks advisers to review the US LLC under the tax law of the place where he resides and works.
- ☐ Define the business problem and compare an Indian entity.
- ☐ Confirm the legal owner, Indian residence and beneficial owners.
- ☐ Check RBI/authorised-dealer treatment before funding.
- ☐ Review Indian income tax, foreign-asset, GST and management questions.
- ☐ Select the US state based on real operations and recurring fees.
- ☐ Search the name and appoint an eligible registered agent.
- ☐ File the state document and keep the approved copy.
- ☐ Sign an operating agreement and record initial contributions.
- ☐ Apply for an EIN through the IRS international route.
- ☐ Verify bank and processor support for the real owners and activity.
- ☐ Keep a ledger of USD/INR receipts, owner transfers and work location.
- ☐ Review US Form 5472, treaty, state filings and Indian returns annually.
Frequently Asked Questions
Can an Indian citizen own 100% of a US LLC?
Do I need a US visa, co-owner or Social Security number?
Can I register the LLC from India without visiting the US?
Does the LLC automatically avoid Indian tax?
Is funding a US LLC covered by RBI rules?
Which US state should I choose?
What is the current Delaware annual LLC tax?
Can I obtain an EIN from India for free?
Will the LLC guarantee a US bank account or Stripe?
Do I need Form 5472 if the LLC has no sales?
What is the penalty for missing Form 5472?
Does India have a US income-tax treaty?
Must I disclose my LLC on an Indian tax return?
Are exported services automatically free of Indian GST?
Do US-created LLCs file a federal BOI report now?
Can I close an unused LLC?
Final Thoughts
The US filing process for an Indian founder is manageable: choose a state, appoint an agent, file the LLC, document ownership, obtain an EIN and apply for financial services. The difficult decisions usually concern how a person resident in India can fund the entity, where profits are taxed, and which US information returns are required.
Start with the business reason, map ownership and funds flow, and ask the authorised-dealer bank and cross-border advisers about the intended structure. Price the first two years, keep clean USD and INR books, and schedule the US and Indian reporting calendars. An LLC can be a useful operating vehicle when those pieces fit together.
Sources & Research Notes
Primary official sources reviewed September 2026. Individual tax, investment and provider outcomes require a current, fact-specific review.
- Wyoming Secretary of State LLC Articles: $100 base filing and annual report timing.
- New Mexico Secretary of State LLC filing: $50 application fee.
- Delaware Division of Corporations: $400 annual LLC tax and June 1 due date.
- IRS Form SS-4 instructions: international EIN routes.
- IRS Form 5472 instructions: reportable transactions and penalties.
- IRS service-income sourcing: work-location principle.
- US–India income-tax treaty: treaty text and categories.
- RBI Overseas Investment Directions: investment and reporting framework.
- Indian Income Tax Department Schedule FA resources: foreign-asset disclosure guidance.
- CBIC GST export guidance: LUT and export refund administration.
- FinCEN BOI page: August 2026 final rule for US-created entities.