How to Form a US LLC from Mozambique A practical guide for Mozambican founders and global businesses
A founder in Maputo, Beira, Nampula or the Mozambican diaspora can generally own a US limited liability company without US citizenship or a trip to America. The useful work comes after filing: obtaining an EIN, qualifying for banking, recording owner transactions, and handling taxes and foreign-exchange rules on both sides. This guide shows the seven Northwest ordering screens, compares state costs, and explains what the metical, Mozambique’s export rules, and local licensing mean for a US-facing business.
Quick Answer: How to Form a US LLC from Mozambique
A Mozambican individual can generally form and wholly own a US LLC remotely. Select a state based on real operations and cost, hire a registered agent there, file the formation document, sign an operating agreement, obtain a free EIN from the IRS, then apply for banking with accurate personal and business information. Wyoming and New Mexico are common states to compare for a solo remote business without US staff or premises. Delaware may suit a specific investor or legal plan, but its annual LLC tax is now $400.
Formation is only the first step. A foreign-owned single-member LLC must review whether owner contributions, distributions or other related-party transactions trigger Form 5472 with a pro forma Form 1120. An LLC does not automatically provide a US visa, bank account, payment processor, or tax exemption.
Mozambique-specific issue: Mozambique uses the metical (MZN), with a floating exchange rate against the dollar. Banco de Moçambique administers foreign-exchange rules, including procedures for cross-border capital operations and repatriation or conversion of some export earnings. A US account does not automatically let a Mozambique-based exporter keep all receipts offshore. Local tax, company registration and licensing can still apply to work performed from Mozambique. The IRS lists no US–Mozambique income-tax treaty.
Table of Contents
- Who benefits from a US LLC?
- Ownership and LLC basics
- Choose a US state
- Formation and ongoing costs
- Prepare to file
- Seven-screen formation walkthrough
- Obtain an EIN
- Banking and payments
- US tax and Form 5472
- Mozambican tax and foreign exchange
- Compliance calendar
- DIY versus services
- Founder scenarios
- Launch checklist
- FAQs
When Does a US LLC Make Sense from Mozambique?
A US LLC can give overseas clients a defined counterparty, separate business obligations from its owner’s personal affairs, and document ownership among collaborators. Some US payment providers accept applications from foreign-owned US LLCs. Their support for a Mozambican resident is a separate decision, so verify it before forming solely to reach a particular provider.
If you mainly sell to local customers and receive meticais, a Mozambique-registered company or sole proprietorship may be simpler. A US LLC cannot substitute for local tax registration or an activity license where those are required. If a Mozambican company will own the US LLC, assess that ownership chain before filing; a foreign entity owner may change US reporting and bank documentation.
US LLC Basics and Mozambican Ownership
An LLC is a US state-law entity. Properly maintained, it can limit an owner’s personal exposure to ordinary company debts; a personal guarantee, fraud or poor separation of funds can undermine that protection. A one-owner LLC is normally disregarded for US federal income tax unless it elects corporate status. The state-law company still exists, and IRS information reporting may still apply.
| Term | Meaning | Practical effect from Mozambique |
|---|---|---|
| Articles or Certificate of Formation | State filing creating the LLC | Retain the approved document for banking and contracts |
| Registered agent | In-state recipient for legal service | A Maputo home address cannot act as a Wyoming agent address |
| Operating agreement | Private ownership and management rules | Useful even for a sole owner; banks may request it |
| EIN | IRS business tax ID | Free if obtained directly; international applicants may use phone, fax or mail |
| Disregarded entity | One-owner LLC whose income is generally attributed to its owner | May still need Form 5472 and a pro forma Form 1120 |
| Foreign qualification | Registration in a second US state where business is conducted | Wyoming formation will not cover operations in every other state |
Can a Mozambican citizen own 100%?
Generally yes. US states do not impose a general US citizen co-owner or residency requirement for an LLC. A visa is not needed merely to own and manage it from Mozambique, and an SSN is not generally required to file the state formation document. Physically working in the United States raises a separate immigration issue; LLC ownership creates no work authorization.
Expect an agent, bank or payment processor to request an actual residential address, passport, names of all beneficial owners, business description, website or contracts, expected transaction volume and the source of initial funds. Use your true operating and residence details. A registered-agent address is for legal notices; it is not proof that you or the business work from that office.
Choose the Right US State
There is no single best state for every founder. If you will have a US office, staff, inventory, property or regular in-person activity, start with the state where that activity occurs. Otherwise compare formation price, annual charges, investor expectations and the available registered-agent service. Incorporating in a low-cost state will not exempt operations in another state from registration or tax there.
| State | Base formation fee | Recurring state charge | Good fit | Watch for |
|---|---|---|---|---|
| Wyoming | $100 | Annual report license tax, $60 minimum | Remote owner wanting predictable state costs | Online convenience fee may add to the base filing fee |
| New Mexico | $50 | No routine LLC annual report | Cost-conscious, simple business | Registered agent and federal obligations continue |
| Delaware | Commonly $110; confirm current filing schedule | $400 annual LLC tax, due June 1 | Specific investor or legal reasons | LLCs do not file the corporation annual report; they still pay tax |
| Operating state | Varies | Varies | Actual US premises, people or inventory | Extra-state registration can duplicate costs |
Wyoming’s $100 base filing fee appears on its official LLC form. Delaware’s current tax-payment page lists a $400 annual LLC tax. State fees change, so use the state filing portal or service checkout for the exact current total. New Mexico’s no-report feature should not be confused with zero maintenance: you still need a registered agent and any applicable tax or licensing filings.
Column chart: illustrative base state formation fees
Delaware filing figure follows its official published fee schedule. Verify all state fees and online charges at filing. Sources: state filing authorities, September 2026.
Horizontal bar chart: recurring state charges, simple LLC
State-level routine charges only. Excludes registered agent, tax preparation, business licenses and variable Wyoming assets-based charges.
Budget for Formation and Ongoing Compliance
Separate the amount needed to create an LLC from the amount needed to maintain one. A bare state filing may cost less than a service order. Professional tax help, bank fees and local legal advice are business-specific, and they may cost more than formation. If cash is tight, budget for year two before spending on optional branding or certified copies.
| Item | Planning amount | When | Notes |
|---|---|---|---|
| Wyoming state filing | $100 base | Once | Online processing may add a fee |
| Northwest formation | Illustrative $39 + state fee | Once | Check live checkout; optional services change total |
| Registered agent | Often $100–$200/year | Every year | Ask whether first year is bundled |
| IRS EIN | $0 direct | Once | Third-party assistance is optional |
| Wyoming annual report | $60 minimum | Every year | May be higher based on in-state assets |
| Form 5472 preparation | Quote required | As applicable each year | Complexity and book quality determine cost |
| Banking, wires, FX | Provider-specific | Ongoing | Price includes conversion spread, not just visible fees |
Donut chart: illustrative $139 Wyoming checkout before add-ons
This is a planning example, not a live price quote. Agent renewal, online fees, tax help and add-ons are excluded.
Line chart: cumulative minimum state charges through two annual cycles
Illustrative base fees: NM $50 and no routine annual report; WY $100 + $60 minimum each annual cycle; DE $110 illustrative filing + $400 each annual cycle. Excludes agent, processing fees, taxes and professional services; confirm Delaware filing fee.
Compare the actual checkout price with the state filing fee and next year’s registered-agent renewal before ordering.
Review Northwest’s Formation Options →Prepare Before You File
Gather your proposed LLC name, preferred state, owner details, business description, contact email and payment method. Search the state database for an available name and check trademark conflicts separately. Name availability in one state is not nationwide trademark clearance. Decide whether the LLC will be member-managed or manager-managed; a solo consultancy normally chooses member-managed unless a specific agreement requires otherwise.
- Identity: valid passport, real home address and consistent name spelling across documents.
- Business evidence: website or profile, sample contract, invoices or a clear product description. Banks may request these later.
- Ownership: list every member, contribution and percentage. Multi-member LLCs have more complex federal tax reporting.
- Address plan: distinguish registered-agent address, mailing address, principal business location and owner’s residence.
- Money plan: decide how the initial fee will be paid lawfully and how future transfers between Mozambique and the LLC will be documented.
Your registered agent must have a qualifying physical address in the formation state and be available to receive official notices. A virtual mailbox does not necessarily satisfy that legal role. Ask who scans mail, how quickly notices appear, how renewal works and what happens when your payment card expires.
Set a realistic launch sequence
The state filing is often the short stage; bank eligibility and tax setup can take longer. Start by choosing the structure and state, checking the provider’s current support for your real residence, and confirming what local Mozambican registration or foreign-exchange review may be needed. Then file the LLC, receive the approved state document, sign an operating agreement, and apply for the EIN. A business account application usually follows once the EIN notice is available. Only after the payment route is approved should you promise clients that a particular card or transfer method will work.
A formation service can submit documents, but it cannot guarantee that the IRS, a US bank or a Mozambican authorised dealer will finish on your preferred date. Keep alternatives in your launch plan: invoice terms that allow bank transfer, a clear refund procedure, and enough working capital to cover annual agent and state fees while accounts are under review. If you serve clients in Portuguese and English, decide whether the LLC name, website and contract language clearly identify the same legal seller.
Step by Step: Form a US LLC from Mozambique with Northwest
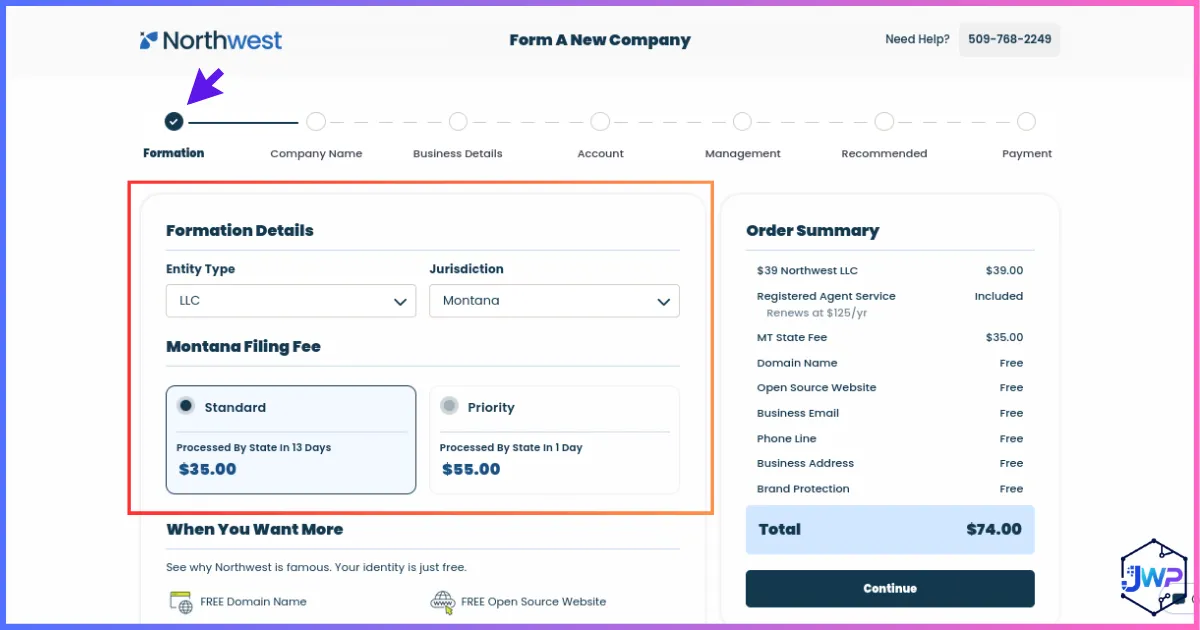
The seven images below illustrate the ordering sequence supplied for this guide. Screens, labels, pricing and eligibility can change. Use them to understand the decisions you will face, then read the live order summary before paying. The screenshots show a formation-service workflow; you can also file directly with your selected state and appoint an agent yourself.
Choose LLC and formation state
Select a limited liability company, then choose the state based on your actual operations and budget. For a Mozambique-based remote consultant with no US physical activity, Wyoming or New Mexico may be simpler than a state chosen only for name recognition. If you plan to raise venture financing, discuss Delaware and the LLC-versus-corporation question before filing.
Enter the legal company name
Use the state’s required LLC designator and compare the spelling with your planned invoices, domain and operating agreement. A state database search helps avoid an immediately rejected name. An optional paid EIN service may appear here; the IRS does not charge for a direct EIN application, so purchase help only if you value the assistance.
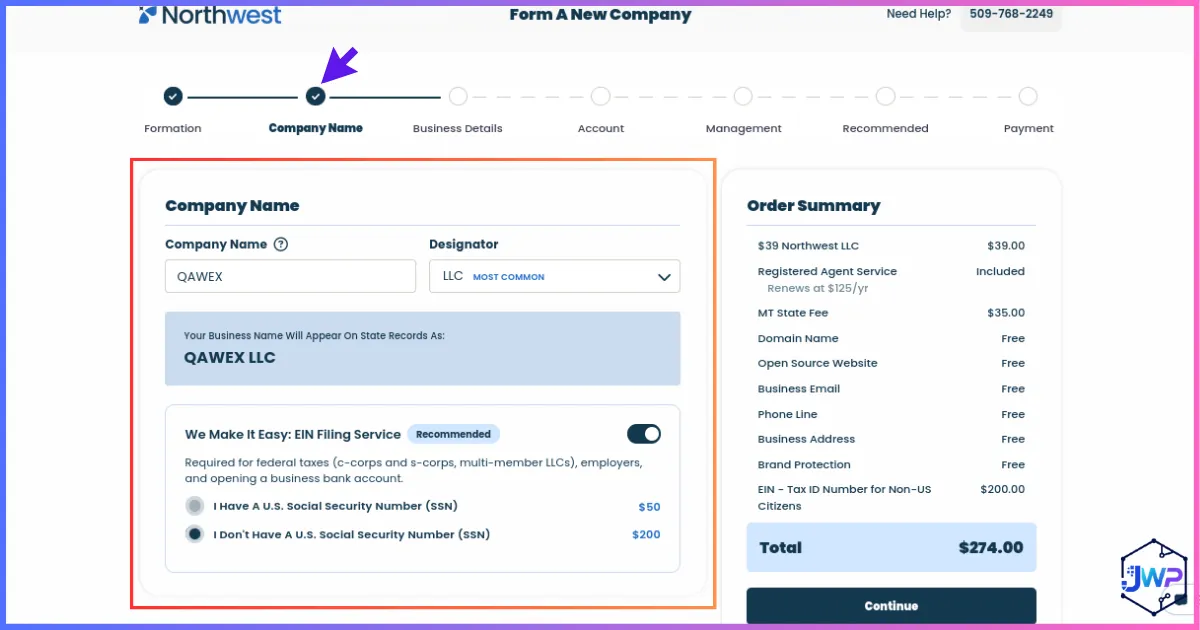
Describe the business truthfully
Give a concise, accurate purpose such as software consulting, design services or online retail. Do not claim an office, employee or line of business you do not have. Use the right mailing and operating addresses; a registered-agent address serves a specific legal purpose and should not be repurposed as proof of your Mozambican residence.
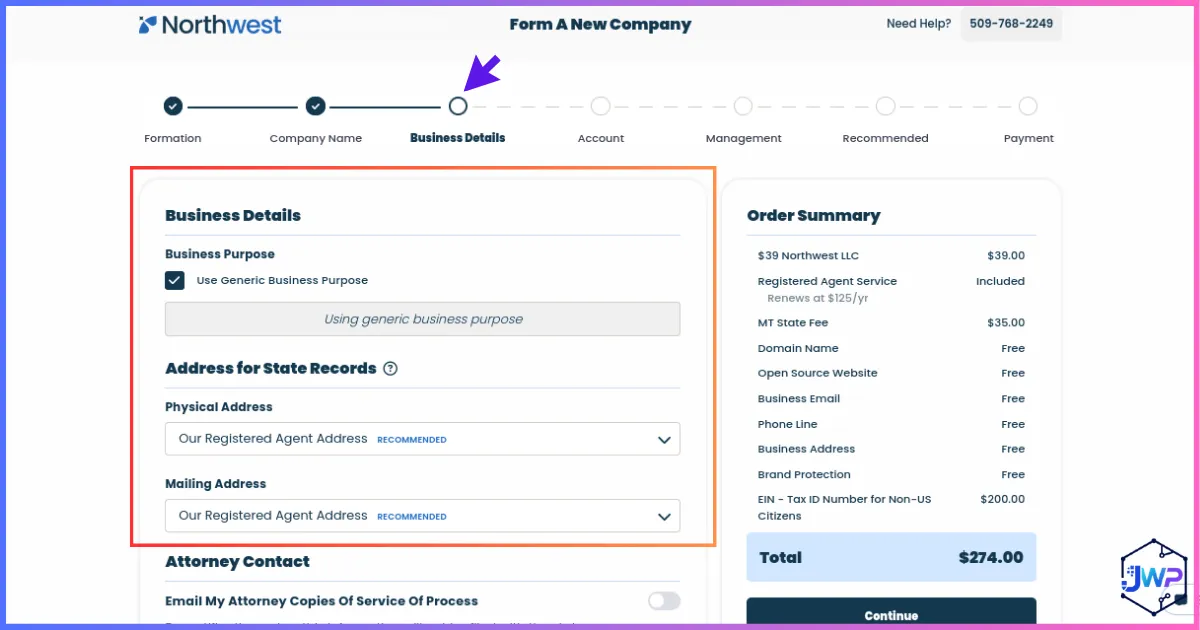
Create an account you will retain
This login may hold state-approved documents, scanned legal mail, invoices and renewal notices. Use an email address with two-factor security and preserve a backup. If another person pays for your formation, keep the account and legal ownership information under the actual owners’ control.
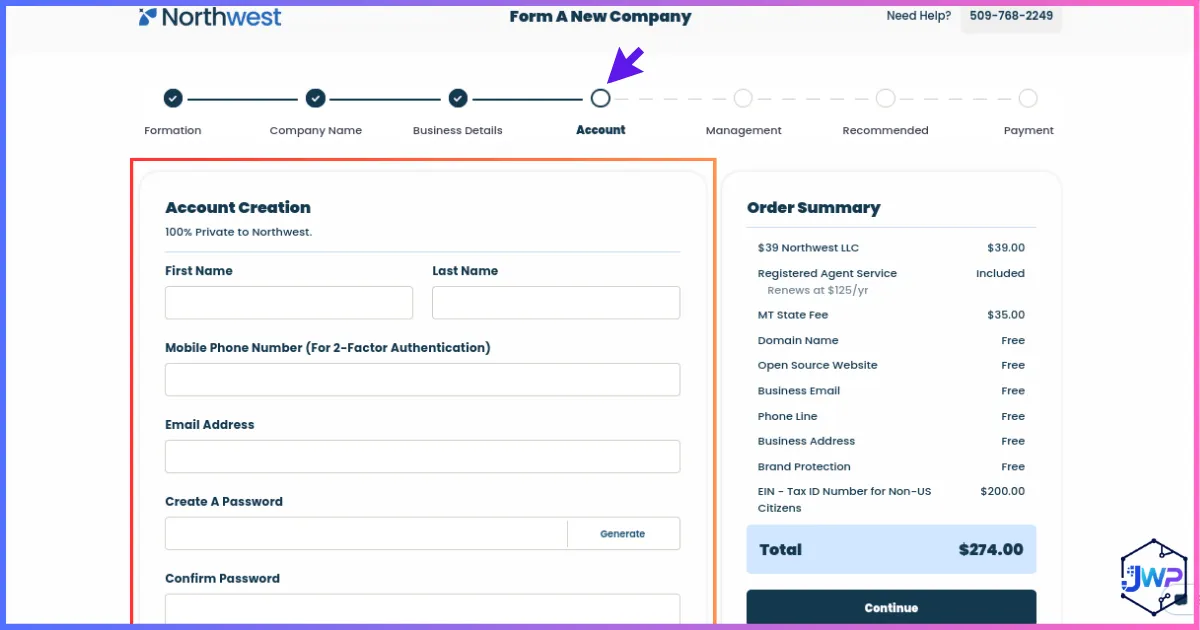
Set management and owner information
A single owner often selects member-managed. Enter legal names and addresses exactly as shown on identity documents. Multiple owners should agree in writing on contributions, voting, exits and tax allocation before ordering; a multi-member LLC is usually taxed as a partnership by default, which is a materially different filing regime.
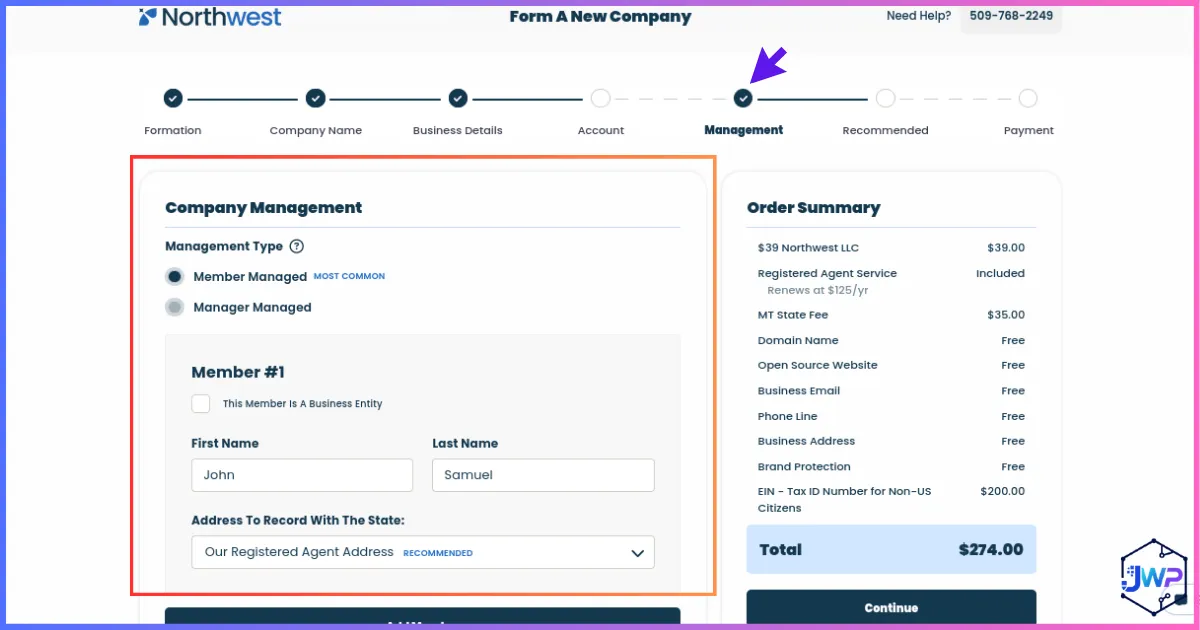
Review optional services
Separate legal requirements from conveniences. A registered agent is required; an EIN assistance package, certified copies, mail forwarding and annual-report filing service are optional in many situations. A bank may ask for particular documents later, so consider buying certified copies only when needed.
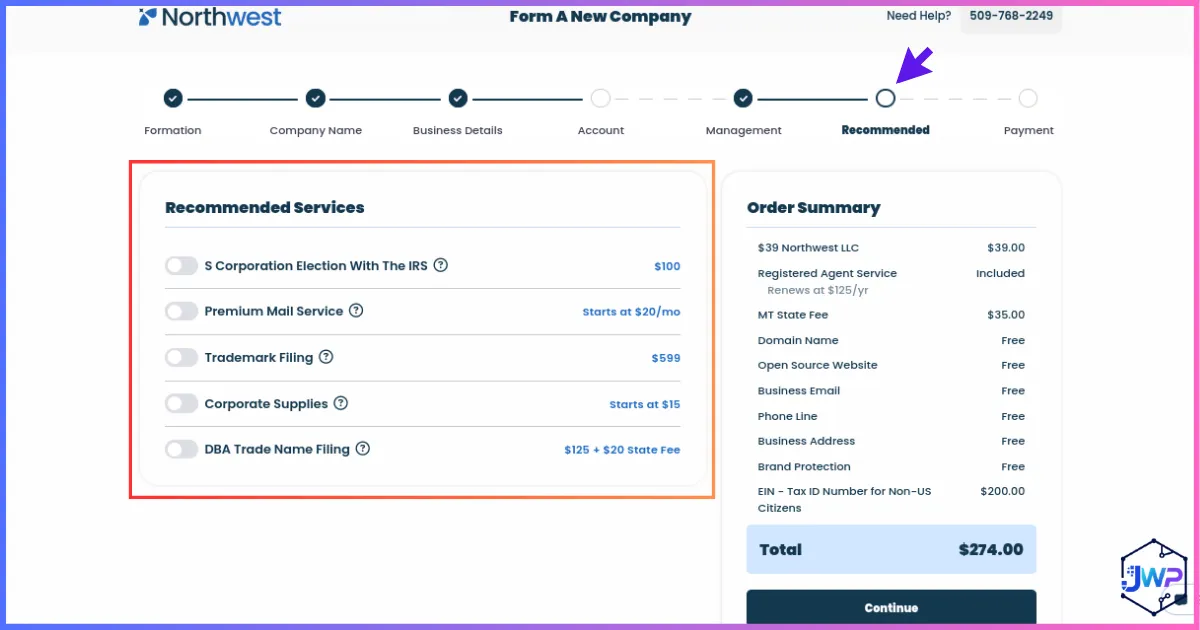
Review total, pay and save evidence
Compare the order total with the state fee, service fee and every optional line item. Save the receipt. Once the state approves the filing, download the stamped Articles or Certificate of Formation, registered-agent confirmation and any operating-agreement template. State processing times vary; do not promise a client a launch date until the filing is accepted.
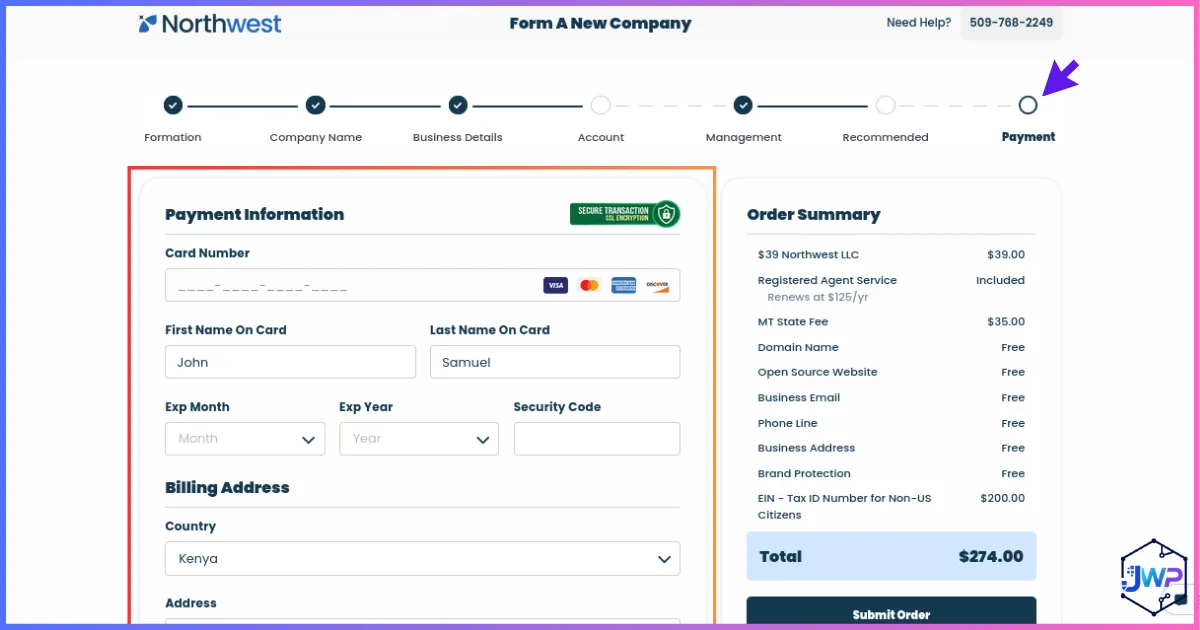
Get an EIN as a Foreign Owner
The Employer Identification Number identifies the LLC to the IRS and is commonly requested by banks, processors and clients. Applying directly is free. The important distinction is the principal place of business: an LLC organized in Wyoming can still have its principal place of business in Mozambique. If there is no US legal residence, principal place of business, principal office or agency, the IRS says the online EIN application is unavailable. International applicants may use the telephone, fax or postal route in the current Form SS-4 instructions.
- Complete Form SS-4: use the approved LLC name and formation date. Identify the real responsible party. Follow current line 7b instructions if that person has no SSN or ITIN; do not invent a number.
- Choose the correct channel: the IRS currently lists 267-941-1099 for international applicants by phone, and 304-707-9471 for a fax sent from outside the US when no US principal office or agency exists. Read the official instructions before sending because numbers and hours can change.
- Keep proof: save the signed SS-4, fax confirmation or call notes and the IRS EIN notice. Match the notice against your state documents immediately.
- Apply once: repeated submissions can produce confusion. Check status with the IRS if the expected response does not arrive.
IRS guidance says a complete fax application with a return fax number can be processed in about four business days and mail takes about four weeks; actual waits can be longer. The telephone route can be faster when available and when the caller is authorized to answer the IRS questions. A formation service cannot guarantee the IRS response time.
Business Banking and Payment Acceptance from Mozambique
Formation and banking are separate applications. A US LLC and EIN make you eligible to apply to some US banks and financial technology providers, but neither guarantees approval. Provider country lists, product features and risk policies change often. Check whether the provider currently supports an owner resident in Mozambique before paying for formation primarily to obtain that account.
| Provider route | What it may offer | What to verify first |
|---|---|---|
| US business bank or fintech | USD account details, domestic payments, cards | Mozambican residency eligibility, acceptable industries, US business address rules |
| Cross-border payment platform | International collections, currency conversion | Whether US LLCs with Mozambican owners are supported and how payouts reach Mozambique |
| Mozambican bank via SWIFT | Local regulated relationship and MZN conversion | Incoming currency, transfer documentation, fees and exchange spread |
| Merchant processor | Online cards and subscriptions | Supported owners, goods, chargeback risk and reserve policies |
Prepare the formation certificate, EIN notice, signed operating agreement, passport, real Mozambican address, business description, website and sample contracts. Keep invoices and payment flows aligned with the entity named in your account application. If a provider asks for a US operating address, an agent’s statutory address is not an operating office. Misstating that fact can result in rejection or closure.
Compare the full cost of receiving $1,000 and converting it to MZN: account fee, incoming fee, intermediary charges and exchange-rate spread. A nominally free account can still be costly once funds move across borders. For an introduction to payment choices, see our guides to opening a Wise account and opening a Payoneer account. Each service’s current country and entity policies control.
How to compare a payment provider before forming
Check the provider’s current supported-residence list for the owner, not only its supported-incorporation list for the LLC. Ask whether a Mozambican home address is accepted, whether a US business address is required, and what counts as proof of actual operations. A registered agent can receive legal notices; it cannot truthfully prove that your team works from its office.
Then map the complete flow of a real customer payment. For example: a US client pays a $1,000 invoice to your LLC; the provider verifies the payer, settles the amount, deducts any fees, and transfers the balance to an eligible account. If you need MZN in Mozambique, the final bank or platform converts the funds. Ask which entity appears as the merchant, how refunds and chargebacks are funded, how long reserves can be held, and whether payouts to a Mozambican account are supported. These answers may be more important than a headline “free account” claim.
- Ownership file: keep each member’s passport, address evidence and ownership percentage consistent across state, IRS and bank records.
- Commercial file: keep a working website, service description, client agreement and sample invoice showing what customers buy.
- Funds file: document the original owner capital, every related-party transfer and how the business will use a US account.
- Transfer file: ask a Mozambican authorised dealer which invoices, bank statements or tax documents it will request for inbound or outbound payments.
If your preferred provider does not support a resident owner in Mozambique, do not list a relative’s foreign address as your residence or open an account in someone else’s name. Choose a provider that supports your real facts, use a different lawful payment route, or revisit whether the US LLC still solves your problem.
Pie chart: illustrative allocation of $1,000 in business receipts
Illustrative budgeting example, not a statistic, tax rate or recommended distribution. Your business may require a different allocation.
US Tax Rules a Mozambican Owner Must Understand
The federal income-tax answer depends on the LLC’s classification and actual activities. A single-member disregarded LLC generally passes income to its owner for federal income-tax purposes. A multi-member LLC generally files as a partnership unless it elects another classification. A corporation election creates a separate taxpayer and different forms and potentially different tax costs.
Where is income sourced?
For personal services, the IRS generally looks to where the work is physically performed, not the client’s location, the invoice currency or the receiving bank. Work performed entirely from Mozambique is generally foreign-source service income. Work performed during a US visit may create US-source income, and mixed-location work requires allocation. Product sales, inventory, royalties, platform income, US real estate and employees raise different rules. See the IRS personal-service sourcing explanation.
Foreign source does not settle every question. US trade-or-business activity and effectively connected income may create a US return and tax. A Mozambique-resident person may also have local tax duties on income attributable to them. Do not rely on a blanket claim that foreign owners pay “zero US tax.” A qualified cross-border accountant should assess the actual activity, ownership, client contracts and bank flow.
Form 5472 and pro forma Form 1120
The key information-return rule for a wholly foreign-owned US disregarded LLC is Form 5472. The IRS requires it when the LLC has a reportable transaction with its foreign owner or another related party. The definition includes many formation, contribution, distribution and other monetary or nonmonetary transactions; it is broader than taxable profit. The required Form 5472 is attached to a pro forma Form 1120 and filed by the Form 1120 due date, with extensions possible through Form 7004. For a calendar-year filer the ordinary due date is generally April 15 of the following year, adjusted for weekends and holidays.
The IRS instructions specify a $25,000 initial penalty for failure to file a required, complete Form 5472 on time. That penalty can matter even when no income tax is due. Keep a ledger of owner funding, reimbursements, transfers, distributions and related-party payments from the first day. If you believe there were no reportable transactions, document why rather than assuming that zero revenue means no filing. Review the official Form 5472 instructions with a preparer familiar with foreign-owned disregarded entities.
| Example | Potential US implication | Record to keep |
|---|---|---|
| Owner pays formation costs personally | May be treated as a reportable contribution or related-party transaction | Invoice, receipt and owner ledger |
| LLC sends money to owner | Distribution or repayment may be reportable | Bank transfer, resolution and classification |
| Consulting delivered in Maputo | Generally foreign-source services; assess US business facts | Contract and work-location log |
| Consulting delivered partly in the US | US-source allocation and possible return | Travel dates, workdays and invoices |
| US warehouse holds inventory | Potential sales-tax, income-tax and state nexus issues | Warehouse contract and shipment records |
Treaty, withholding and W-8 forms
The IRS treaty list does not show a US–Mozambique income tax treaty, so a Mozambican tax resident generally cannot claim a treaty-reduced withholding rate just by asserting Mozambican residence. US-source fixed or determinable annual or periodic income, such as some royalties or dividends, can be subject to a default 30% gross withholding rate unless a specific statutory exception applies. Service fees, dividends and royalties should not be treated as interchangeable categories.
The right payee form depends on who legally and fiscally receives the payment. A nonresident individual may be asked for Form W-8BEN; a foreign entity may use W-8BEN-E; a US entity that is a US person for the relevant purpose may use W-9. A US disregarded LLC with a foreign owner can involve look-through rules and requester-specific documentation. Ask a tax adviser before sending a form, especially if a US customer or platform automatically suggests W-9 merely because the LLC is US-organized.
BOI and state obligations
Under FinCEN’s August 2026 final rule, entities formed in the United States are exempt from the federal Corporate Transparency Act beneficial ownership information report. This is separate from bank know-your-customer checks, state filings and IRS forms. Monitor FinCEN’s BOI page because the rule can change. An LLC with a second US state’s activity may need foreign qualification there and may face state tax, sales-tax or employment filings.
Mozambique Taxes, BAU Licensing and Foreign Exchange
Forming a company in the US does not erase obligations arising from residence or business activity in Mozambique. A founder working in Maputo for overseas clients should examine Mozambican personal or business income tax even when invoices are issued by a US LLC. A Mozambican company that owns the LLC may have its own accounting and related-party issues. Tax residency, income source, the legal payee and the nature of each withdrawal must be reviewed together; US disregarded-entity treatment is not a promise that Mozambique will classify the entity the same way.
Local registration and the NUIT
Mozambique’s Balcão de Atendimento Único (BAU) coordinates services including legal-entity registration, commercial or industrial licensing and tax-administration services. Its economic-activity licensing guidance also discusses registration for import and export operators and the Número Único de Identificação Tributária (NUIT). If you actually conduct activity in Mozambique, ask BAU and a local adviser whether you need local registration, an activity license, a NUIT, VAT registration or an exporter certificate. A US filing does not answer those questions.
The metical and overseas receipts
The Banco de Moçambique describes the metical’s exchange regime as floating. A $1,000 invoice therefore has no permanent MZN value. Record the conversion date, quoted rate, bank spread and any intermediary fees when comparing a US account with a local bank route.
Banco de Moçambique administers foreign-exchange controls and classifies transactions involving residents, nonresidents, foreign currency and assets abroad. Its official exchange-control guidance states that documents may be required for cross-border operations and that repatriation, bank-channel and declaration duties can apply. The bank’s 2024 regulatory notice identifies the current framework for capital operations and export-earnings repatriation or conversion. Exceptional rules have also been issued, so check the rule in force on the day of your transaction with an authorised bank.
| Flow | Question to ask | Records to keep |
|---|---|---|
| Owner funds the US LLC | Is the transfer an overseas investment, loan or service payment under Mozambican exchange rules? | Bank instruction, LLC contribution ledger, approval if required |
| Foreign client pays for services done in Maputo | How are the receipts taxed and must any earnings be repatriated or converted? | Contract, invoice, work record, settlement statement |
| LLC pays the owner | Is this a distribution, reimbursement, salary or loan repayment? | Resolution, transfer record, tax classification |
| Goods leave a Mozambican port | What exporter, customs and foreign-exchange documentation applies? | Shipping documents, customs entry, invoice, bank evidence |
Keep USD and MZN records side by side. The US accountant needs owner transactions for Form 5472; a Mozambican adviser may need invoices, local work locations, conversion records and evidence of how export receipts were handled. If your activity involves both digital services and physical goods, separate them in the ledger because tax source, VAT, customs and currency rules can differ.
Distinguish services, digital products and physical exports
The label on a US invoice does not settle every legal question. A software consultant performing hours in Nampula has service activity that can be documented with work logs and deliverables. A business licensing software or copyrighted material may need to analyse royalty and intellectual-property rules, including possible US withholding on US-use royalties. A trader shipping goods from Beira needs a separate record of inventory, title transfer, export declarations and any US warehouse. Mixing these three flows in a single ledger makes both US sourcing and Mozambican exchange-control review harder.
For each revenue stream, record who sold it, where performance or production occurred, the customer’s location, where payment was received, and what happened to the foreign currency. This is particularly useful when a US payment processor pays the LLC but work and fulfillment happen in Mozambique. A tax professional can then evaluate the correct income category rather than assuming every dollar paid to a US LLC has the same tax result.
A Realistic Compliance Calendar
Keep dates in two calendars with reminders at least 30 days ahead. A provider’s email reminder is useful, but the legal duty belongs to the LLC or its owner. The annual dates below assume a calendar-year US tax reporting period; a professional can confirm the period and any extension needed for your entity.
| When | Action | Who handles it |
|---|---|---|
| At formation | Save approved articles, sign operating agreement, open ledger | Owner |
| Before invoicing | Confirm EIN, bank and processor terms; tax form requested by payer | Owner with adviser as needed |
| Monthly | Reconcile USD and MZN statements, owner transfers and receipts | Bookkeeper or owner |
| Before Wyoming anniversary month | Prepare annual report and minimum license tax | Owner or filing service |
| By June 1 if Delaware LLC | Pay annual $400 Delaware LLC tax | Owner or filing service |
| Generally April 15 for calendar-year Form 1120 | File Form 5472 with pro forma 1120 if reportable transactions exist, or arrange valid extension | Qualified US preparer |
| Every year | Renew registered agent and review Mozambican reporting | Owner and Mozambican adviser |
If the LLC has US employees, US-source business income, sales-tax nexus or a corporate election, additional dates apply. A New Mexico LLC may have no routine state annual report but still needs its agent and applicable federal filings. Closing an LLC does not erase final returns, state dissolution steps or unpaid fees.
Radar chart: planning priorities by business model
Editorial planning scores, not measured data. Higher reach indicates an area needing more attention. Physical goods typically add inventory, customs and state-tax questions.
DIY, Formation Service or a Different Entity?
Direct state filing can save a formation fee if you understand the state portal and separately appoint a registered agent. A formation service offers a guided form, document dashboard and possible agent bundle. Neither route replaces US tax advice or Mozambican legal advice. Compare the complete first two years, including renewal, rather than just a one-time promotional price.
File directly when
- You are comfortable checking the state form and name rules.
- You already selected and priced an agent.
- Your ownership and purpose are straightforward.
- You will manage deadlines yourself.
Consider paid help when
- Several owners need a tailored agreement.
- A US presence or inventory complicates nexus.
- You want a consolidated filing and agent dashboard.
- You need tax classification or cross-border advice.
Our formation-service comparison and Northwest review can help you compare practical features. If public-record privacy matters, read the limits in our anonymous LLC guide; a bank and government authorities can still require your identity.
Some founders should choose a different entity. Venture-backed startups may need a Delaware corporation; a purely local Mozambican shop may need a locally registered company; and a partner-owned venture may need a carefully drafted multi-member agreement. Corporate tax elections and C corporations can sometimes suit retained earnings or investor needs, but they add complexity. Model tax and filing costs before choosing them.
Ready to compare a filing service? Check the state fee, agent renewal and every optional service on the final order screen.
View Northwest LLC Formation →Three Mozambican Founder Scenarios
1. Software consultant in Maputo
A consultant writes code in Maputo for US and European clients. She forms a single-member Wyoming LLC to sign contracts and invoice. For US service-income sourcing, the place where the work is physically performed generally matters more than the client’s address. She records her work location, the capital she personally contributes, and any money withdrawn. She asks a Mozambican adviser how local income tax and foreign-exchange rules apply to the receipts.
2. Exporter operating from Beira
An entrepreneur sources goods in Mozambique and sells to an overseas distributor using a US LLC. His shipping documents, local exporter registration, customs entries and bank settlement instructions need to match the real seller and flow of title. Banco de Moçambique’s export-earnings rules may apply even if the US entity receives dollars. US product, inventory and state tax questions also arise if goods are stored in an American warehouse.
3. Mozambican citizen living in Portugal
A passport holder living and working in Portugal wants a US LLC for software subscriptions. Her nationality does not determine tax residence or bank eligibility. She uses her real Portuguese address, reviews how Portugal classifies the LLC, and checks whether she has any Mozambique-source activity before applying rules written for a Mozambique resident.
- ☐ Define the business activity, customers, inventory and place where work is performed.
- ☐ Compare a Mozambique-registered entity, a US LLC and other structures.
- ☐ Check local BAU licensing, NUIT, VAT and exporter registration as applicable.
- ☐ Choose the US state using actual operations, filing cost and annual charges.
- ☐ Appoint an in-state registered agent and confirm renewal pricing.
- ☐ File formation documents and sign an operating agreement.
- ☐ Apply once for the EIN through the proper IRS international channel.
- ☐ Confirm bank and processor support for your actual residence and business.
- ☐ Record owner contributions, reimbursements, distributions and related-party payments.
- ☐ Ask a Mozambican bank about current exchange, repatriation and conversion rules.
- ☐ Review US Form 5472, state deadlines and Mozambican tax each year.
- ☐ Compare regional approaches in Zambia and Namibia if your business also operates there.
Frequently Asked Questions: US LLCs from Mozambique
Can a Mozambican citizen own 100% of a US LLC?
Do I need a US visa, SSN or ITIN to form the LLC?
Which state is best when I work from Maputo?
What does a Wyoming LLC cost?
What is Delaware’s annual LLC tax?
Can I obtain the EIN free from Mozambique?
Will the LLC guarantee a US bank or Stripe account?
Does a one-owner foreign-owned LLC always file Form 5472?
What is the Form 5472 penalty?
Is there a US–Mozambique income-tax treaty?
Will US incorporation eliminate tax in Mozambique?
What is the NUIT?
Can the US LLC keep all export income offshore?
Does Mozambique have a fixed USD exchange rate?
Does a US-formed LLC file federal BOI reports?
How do I close an unused LLC?
Final Thoughts
A US LLC can be useful for a Mozambican founder with real international clients, a clear banking plan and the capacity to keep records. The basic sequence is manageable: choose a suitable state, file with a registered agent, obtain an EIN, document ownership, apply honestly for financial services, and review US and Mozambican obligations every year. The difficult parts are usually tax classification and payment-provider eligibility, not the state filing form.
Start with the business problem you need the LLC to solve. Price the first two years, confirm that your intended provider supports an owner at your actual residence, and budget for the Form 5472 and local-tax review. A well-maintained entity is an asset; a cheap formation without a compliance plan is an avoidable liability.
Sources & Research Notes
Official sources consulted September 2026. Check current state charges, tax rules, provider terms and exchange-control notices before acting.
- Wyoming Secretary of State LLC form and annual report FAQ: $100 base filing and $60 minimum annual license tax.
- Delaware LLC formation form: $110 base filing; current Delaware tax-payment page: $400 annual LLC tax due June 1. Older PDFs may show an obsolete tax amount.
- New Mexico Secretary of State LLC filing: $50 Articles application fee.
- IRS Form SS-4 instructions: international EIN application routes.
- IRS Form 5472 instructions: related-party transactions, pro forma Form 1120 and penalties.
- IRS service-income sourcing guidance: location of work generally controls.
- IRS treaty list: Mozambique is not listed.
- IRS Publication 515: withholding rules by income type.
- FinCEN BOI guidance: August 2026 final rule exempting US-created entities.
- Mozambique BAU licensing and registration: activity licensing, foreign-trade registration and NUIT references.
- Banco de Moçambique exchange market: floating metical regime.
- Banco de Moçambique exchange control and 2024 rules overview: documentation and export-earnings framework.