How to Form a US LLC from Chad
Yes – citizens of Chad can legally form a US LLC with no visa, no SSN, and no trip to the United States. This guide walks you through state selection, true costs, the exact Northwest Registered Agent ordering flow (7 screenshots), the foreign-founder EIN route, USD banking from N’Djamena, Moundou or the diaspora, and the IRS filings most Chadian owners never see coming. Chad has no US income tax treaty, the Central African CFA franc (XAF) sits inside the CEMAC exchange-control zone where outward transfers must be domiciled through an authorized bank, banking penetration is among the lowest in the world, and the economy runs on oil and humanitarian logistics across a landlocked Sahel territory – all of which shape your formation, funding and repatriation strategy in ways that differ materially from founders elsewhere in Africa.
Quick Answer: How to Form a US LLC from Chad
Citizens of Chad can fully own a US LLC with no US visa, no SSN and no physical presence. The process has six moving parts: (1) pick a formation state – Wyoming is the default recommendation for non-residents, Delaware if you plan to raise investment, New Mexico for the lowest ongoing cost; (2) hire a registered agent in that state (required by law); (3) file the Articles of Organization through a formation service like Northwest Registered Agent ($39 + state fee) or directly with the state; (4) obtain an EIN from the IRS using Form SS-4 by fax or mail – no SSN/ITIN needed for foreign owners; (5) open a US business bank account remotely (Mercury, Relay, Wise Business); and (6) stay compliant: state annual reports, registered-agent renewal, and – critically – the annual Form 5472 + pro-forma Form 1120 information return that every foreign-owned single-member LLC must file even when it owes $0 of US tax.
Chad-specific note: Chad has no bilateral income tax treaty with the United States, so US-source FDAP income (dividends, royalties, certain rents) paid to you as the disregarded owner is subject to the standard 30% withholding – there is no treaty rate to claim on W-8BEN. The Central African CFA franc (XAF) is pegged to the euro at a fixed rate of 655.957 XAF per euro, but the CEMAC exchange-control regime (Regulation No. 02/18/CEMAC/UMAC/CM, administered by BEAC and supervised on the banking side by COBAC) requires that transfers out of the CFA zone be domiciled with an authorized intermediary bank with supporting documentation. Chad is not subject to US sanctions, and Chadian-owned LLCs face ordinary – not enhanced – compliance screening at US banks. The practical bottleneck is domestic: bank account penetration in Chad is estimated in the low teens as a percentage of adults (World Bank Global Findex), internet penetration is roughly 12% – among the lowest in the world – and the banking system (Société Générale Tchad, Ecobank Chad, Orabank Tchad, CBT, BSIC Tchad) is concentrated in N’Djamena, meaning most founders will interact with their US LLC through a diaspora-based funding route rather than a local card.
Total realistic first-year cost: roughly $139-$500 depending on state and add-ons. Total realistic timeline: 1-3 days for the LLC, 3-8 weeks for the EIN (the IRS bottleneck for foreign applicants), then a few days for banking – assuming your funding route (diaspora card, Wise balance, or Payoneer revenue) is arranged first.
Table of Contents
- Why Chadian founders choose a US LLC
- US LLC basics in 90 seconds
- Legality: ownership, visas & compliance
- Choosing your state (with charts)
- True cost: year 1 and beyond
- Registered agent explained
- Step-by-step: Northwest walkthrough
- After formation: EIN, bank, payments
- US taxes for Chadian owners
- No US-Chad treaty: what that means
- The Chad side: BEAC, XAF & domestic taxes
- US LLC vs a local Chadian company
- Compliance calendar
- DIY vs formation services
- Common mistakes to avoid
- Use cases for Chadian founders
- Master checklist
- FAQs
- Final thoughts
Why Chadian Founders Are Forming US LLCs
Chad is one of the most challenging business environments in Africa: a landlocked Sahel country of roughly 18-19 million people, where oil dominates exports and government revenue, where banking and internet penetration sit at the very bottom of global rankings, and where the formal private economy is thin outside N’Djamena, Moundou and the oil-producing south. Yet precisely because of this, the Chadian professionals who do work with international clients – engineers, translators (French, Arabic, plus local languages), logistics coordinators, NGO contractors, developers and traders – face an outsized payments problem: the domestic rails barely exist. For them, a US LLC is not a luxury; it is the difference between getting paid cleanly and not getting paid at all.
- Payment rails that bypass the domestic gap: US clients, ad networks and marketplaces pay US entities with far fewer holds. A US LLC unlocks USD business accounts (Mercury, Relay, Wise Business) that operate entirely outside Chad’s thin domestic banking system.
- CFA-zone convertibility with paperwork: the XAF is freely convertible inside the CEMAC zone and pegged to the euro, but transfers to the rest of the world must be domiciled with an authorized bank against supporting documents. Holding revenue in USD inside a US LLC keeps your international purchasing power outside that queue until you actually need XAF.
- NGO and humanitarian corridor: Chad hosts one of the largest humanitarian operations in the world (UN agencies and INGOs working across the Sahel and Lake Chad basin). Chadian consultants, suppliers and fixers who contract with these organizations – and with the oil sector – need internationally credible invoicing structures.
- Diaspora-first formation: given domestic constraints, a large share of Chadian-owned LLCs are formed by diaspora founders in France, the US, Canada, Cameroon and the Gulf who want a US-facing business identity that matches where their clients are.
- Entity momentum: US business formation has been running above 5 million applications per year since 2021 (US Census Bureau, Business Formation Statistics) – founders from under-banked economies like Chad are part of that non-resident wave.
- Liability shield: an LLC separates your personal assets from business liabilities – particularly important when operating across jurisdictions with different legal regimes (Chad is an OHADA member; the US is not).
US LLC Basics in 90 Seconds
A US Limited Liability Company (LLC) is a state-created business entity that blends corporate liability protection with partnership-style tax flexibility. It is not a corporation, and it does not require US citizenship, residency, or a US bank account to form.
| Term | Plain-English meaning | What it means for you in Chad |
|---|---|---|
| Articles of Organization | The one-page certificate filed with the state that creates the LLC | Filed online by you or your formation service; approval = your LLC exists |
| Registered agent | A person/company with a physical address in the state to receive legal mail | Must be hired; you cannot act as your own agent from N’Djamena, Moundou or Abéché |
| EIN | Employer Identification Number – the LLC’s tax ID from the IRS | Free; foreign owners apply by fax/mail (Form SS-4), no SSN needed |
| Operating agreement | Internal rulebook: ownership, voting, profit splits | Not filed publicly; banks and marketplaces often request it |
| Single-member LLC (SMLLC) | One owner; “disregarded entity” for US tax | The default structure for solo Chadian founders |
| Member-managed vs manager-managed | Owners run it vs appointed managers run it | Member-managed is simplest for solo founders |
| Franchise tax / annual report | Yearly state fee to keep the LLC in good standing | Ranges from $0 (NM) to $800+ (CA) – see state chart below |
| Form 5472 | IRS information return for foreign-owned US disregarded entities | Mandatory annual filing even with $0 US tax; $25,000 penalty for skipping |
| W-8BEN | IRS certificate of foreign status you give to US payers | Certifies you’re foreign; with no US treaty you cannot claim reduced withholding rates |
Legality: Can a Citizen of Chad Own a US LLC?
Yes. All 50 US states permit foreign individuals and foreign companies to own LLCs. There is no citizenship test, no residency test, and no requirement to ever visit the United States. Chad is not on any US sanctions program, there is no OFAC country-based restriction on Chadian nationals, and the compliance profile here is ordinary – Chadian-owned LLCs pass standard KYC at US fintechs without the enhanced screening seen for founders from sanctioned or grey-listed jurisdictions.
One nuance to know about: security-adjacent vetting
Chad sits in the Sahel, a region where US financial institutions apply heightened attention to terrorism-financing risk. This is a geographic risk-rating, not a sanctions restriction: it means your bank or fintech may ask extra questions about your clients, your business purpose and your source of funds. Answer them plainly, keep your invoices and contracts, and onboarding proceeds normally. Founders whose work touches humanitarian logistics should keep their UN/NGO contract documentation especially tidy – it is your best compliance asset.
Three legal myths, cleared
- “I need a visa.” No. Owning and remotely managing a US LLC from Chad (or from the diaspora) requires no US visa. (Physically working inside the US is a different question – ownership alone does not grant work authorization. If relocation is the goal, speak to an immigration attorney; Chad is not an E-2 treaty country.)
- “I need an SSN or ITIN.” No. The IRS issues EINs to foreign-owned LLCs via Form SS-4 filed by fax or mail, with the “foreign” box ticked and no SSN/ITIN on line 7b.
- “I need a US address.” Not yours personally. Your registered agent’s in-state address satisfies the state’s contact requirement, and formation services bundle mail forwarding if you want a business mailing address.
Choosing Your State: Wyoming, Delaware, New Mexico & the Rest
Your LLC can form in any state, but for a Chad-based or diaspora-based owner with no US physical operations, the decision is almost purely about cost, privacy and future plans. Here is the shortlist that matters:
| State | One-time filing fee | Annual state cost | Privacy | Best for |
|---|---|---|---|---|
| Wyoming ⭐ | $100 | $60 min. annual report licence tax | Owners off public record | Default pick for non-residents: cheap, private, no state income tax |
| Delaware | $90 | $300 franchise tax (due June 1) | Members not listed on formation doc | Startups planning VC investment; court precedent (Court of Chancery) |
| New Mexico | $50 | $0 – no annual report, no franchise tax | Owners off public record | Lowest lifetime cost; set-and-forget freelancers |
| Florida | $125 | $138.75 annual report | Names public | Founders with genuine FL ties or LATAM-facing businesses |
| Texas | $300 | Franchise tax report (no tax due under ~$2.47M revenue) | Names public | Founders with real TX operations |
| Nevada | $425 initial | ~$350/yr (list + licence) | Partial | Rarely worth the cost for non-residents |
| California | $70 | $800/yr minimum franchise tax + $20 biennial statement | Names public | Only if you actually operate in CA |
Fees verified against Secretary of State fee schedules, September 2026. Confirm live before filing – states adjust fees periodically.
One-time state filing fee for LLC Articles of Organization (USD)
Source: state Secretary of State / Division of Corporations fee schedules (Sept 2026). Nevada total includes initial list of managers ($150) and state business licence ($200).
Recurring annual state cost to keep the LLC in good standing (USD)
Excludes registered-agent renewal (needed in every state, ~$125/yr with Northwest). California = $800 minimum franchise tax + $20 biennial statement of information amortised.
Our recommendation for Chadian founders
- Wyoming (default): low entry ($100), low renewal ($60), no state income tax, owner privacy, and the most non-resident-friendly banking track record.
- Delaware (if fundraising): investors and accelerators expect Delaware; the state is home to roughly two-thirds of the Fortune 500 and over 1.8 million registered entities (Delaware Division of Corporations). You pay for that prestige with a $300/year franchise tax.
- New Mexico (if minimizing): $50 in, $0/year forever after, no annual report to forget. The trade-off is slightly less name recognition with some banks.
The True Cost of Forming a US LLC from Chad
Two cost layers: one-time (state fee + formation service + optional add-ons) and recurring (registered agent, state annual report/franchise tax, US tax filing help, accounting). In XAF terms, a $139 Wyoming checkout is roughly 75,000-90,000 XAF at typical bureau/bank retail spreads around the 655.957 XAF/EUR peg – but note that paying a US formation service requires an international card or USD balance, which is itself the first practical test of your access to international payment channels (see the funding note in Step 7).
| Item | Typical cost | Frequency | Notes |
|---|---|---|---|
| State filing fee (WY example) | $100 | Once | $50 NM / $90 DE / $125 FL etc. |
| Northwest formation service | $39 | Once | Includes registered agent first year in current bundles – confirm at checkout |
| EIN (DIY via IRS fax/mail) | $0 | Once | Or paid add-on via formation service if you prefer hands-off |
| Operating agreement | $0-$100 | Once | Template included by many services; lawyer-drafted costs more |
| Registered agent renewal | ~$125/yr | Annual | Legally required every year |
| State annual report / franchise tax | $0-$800/yr | Annual | State-dependent (see chart above) |
| US tax return prep (Form 5472 package) | ~$250-$600/yr | Annual | DIY possible but penalty risk makes pros worth it |
| US business bank account | $0 | — | Mercury / Relay / Wise Business have no opening fee |
What you pay at checkout – Wyoming example (USD)
Based on Northwest’s published $39 + state fee pricing and Wyoming SOS fee schedule, Sept 2026.
3-year cumulative cost of ownership: Wyoming vs Delaware vs California (USD)
Illustrative model: state filing fee + $39 service in year 1, then annual state fee + $125 registered-agent renewal. Excludes tax-prep fees and one-off add-ons. California includes the $800 minimum franchise tax each year.
Ready to start? Northwest Registered Agent is our recommended formation service for non-US residents: flat $39 + state fee, in-house registered agent service, and a track record with foreign-owned LLCs.
Start Formation at Northwest →Registered Agent: The Requirement You Cannot Skip
Every US state requires your LLC to maintain a registered agent – a person or company with a physical street address in the formation state, available during business hours to accept service of process (lawsuits) and official state mail. From Chad, you cannot fulfil this yourself.
- Cost: typically $100-$300/year market-wide; Northwest charges $125/year and bundles the first year with most formation orders.
- Privacy bonus: the agent’s address – not yours – appears on public filings as the official contact point.
- Compliance risk: letting the agent lapse triggers “administrative dissolution” in most states – your LLC loses good standing, and banks/payment processors freeze accounts until it is reinstated (with penalties).
We maintain a full independent write-up in our Northwest Registered Agent review, including how their mail-scanning dashboard behaves for overseas clients and what the renewal pricing looks like after year one.
Step-by-Step: Form Your US LLC from Chad with Northwest (7 Screenshots)
Below is the exact ordering flow we ran for a Chadian-owned Wyoming LLC. The whole form takes 10-15 minutes; state approval then typically lands within 1-3 business days for Wyoming, Delaware and New Mexico online filings. Have your passport and an internationally enabled payment method ready before you start.
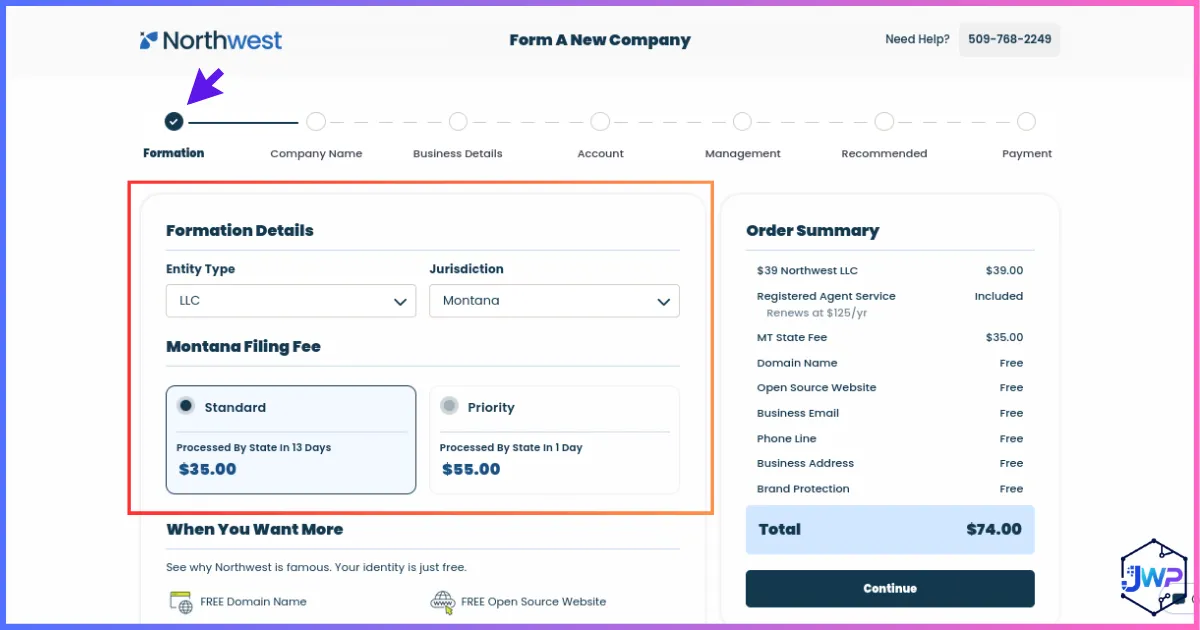
Open the order form and set formation details
Choose your entity type (LLC) and formation state. For most Chad-based founders this is Wyoming; pick Delaware only if investment is on your roadmap.
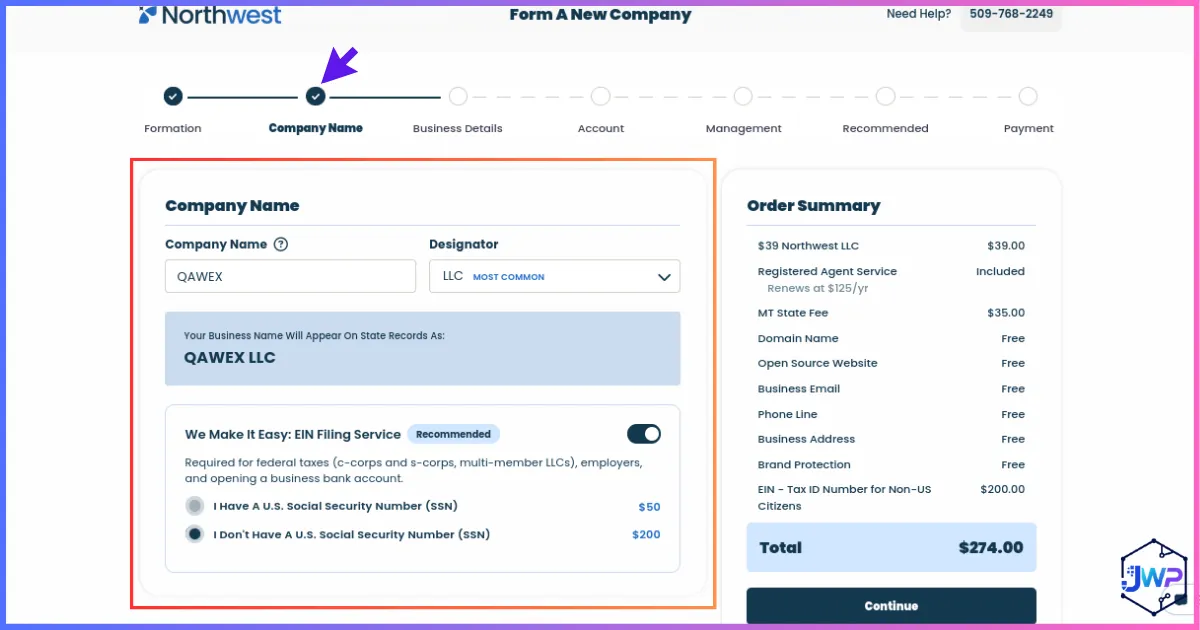
Add your company name (and decide on the EIN service)
Enter your desired LLC name exactly as it should appear, including the “LLC” or “Limited Liability Company” ending. Northwest runs the state availability check for you. On this screen you’ll also see the optional EIN service – recommended if you’d rather not handle IRS Form SS-4 fax correspondence yourself, but skippable to save money (we cover the free DIY route below).
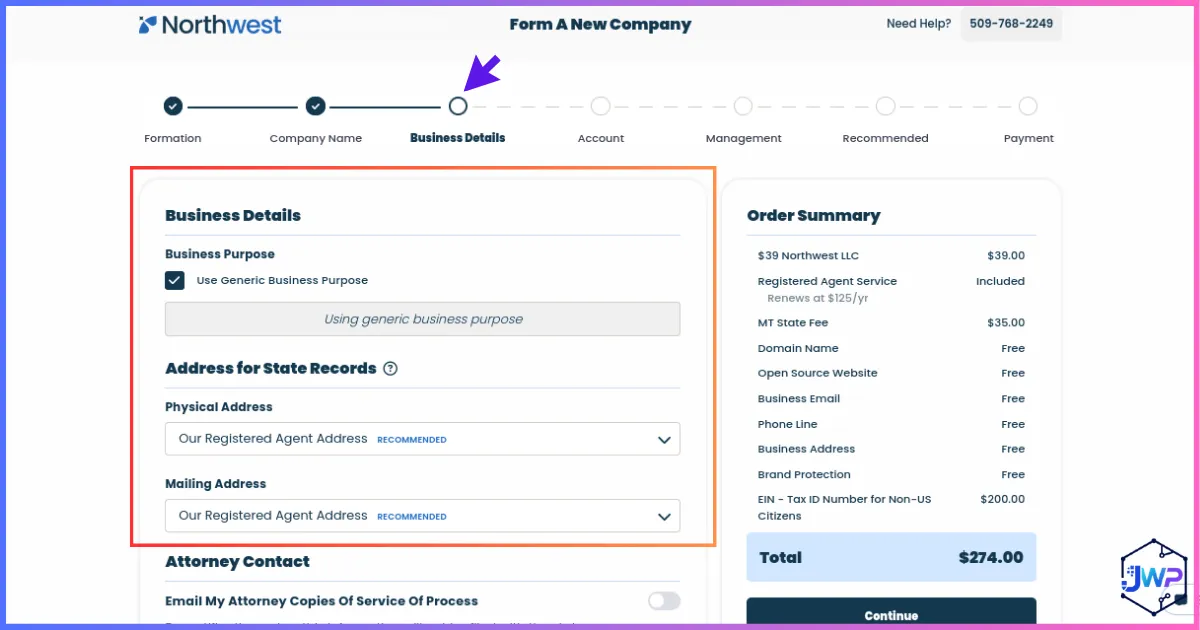
Enter business details
Purpose statement (a generic “any lawful business” line is standard and fine), your contact email, and mailing preferences. Your Chadian residential address (or diaspora address, if you are based outside the country) is used for correspondence; the registered agent’s Wyoming address handles official state service.
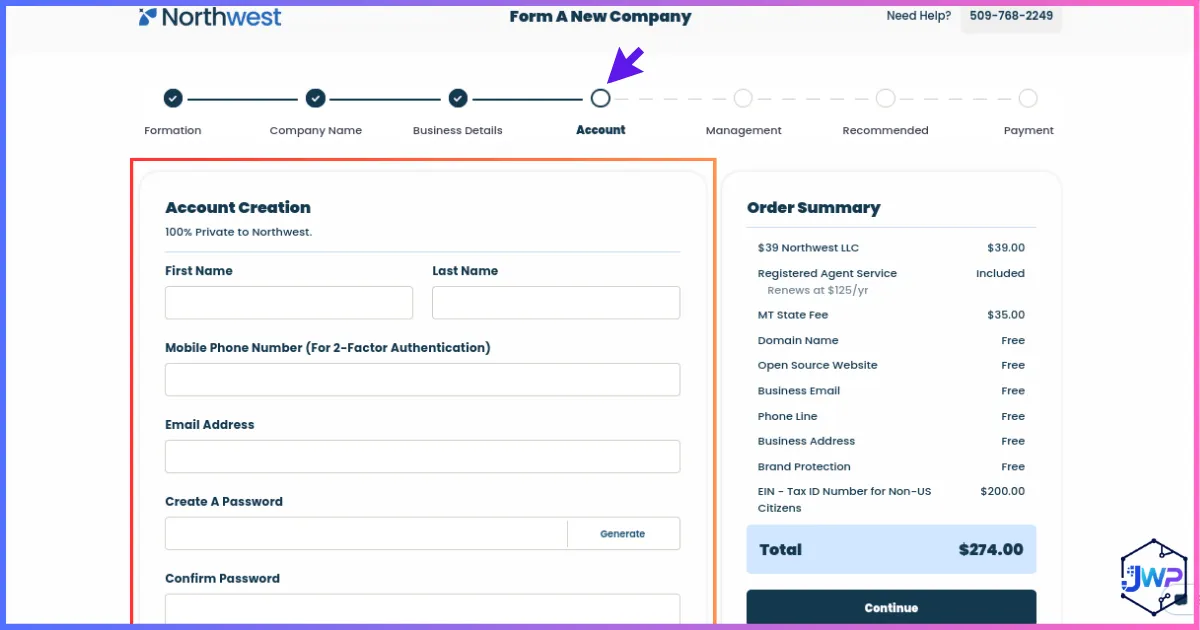
Create your client account
This account becomes your control panel: formation status, scanned mail from your registered agent, annual report reminders and renewal invoices. Use an email you’ll keep for years – losing access complicates renewals.
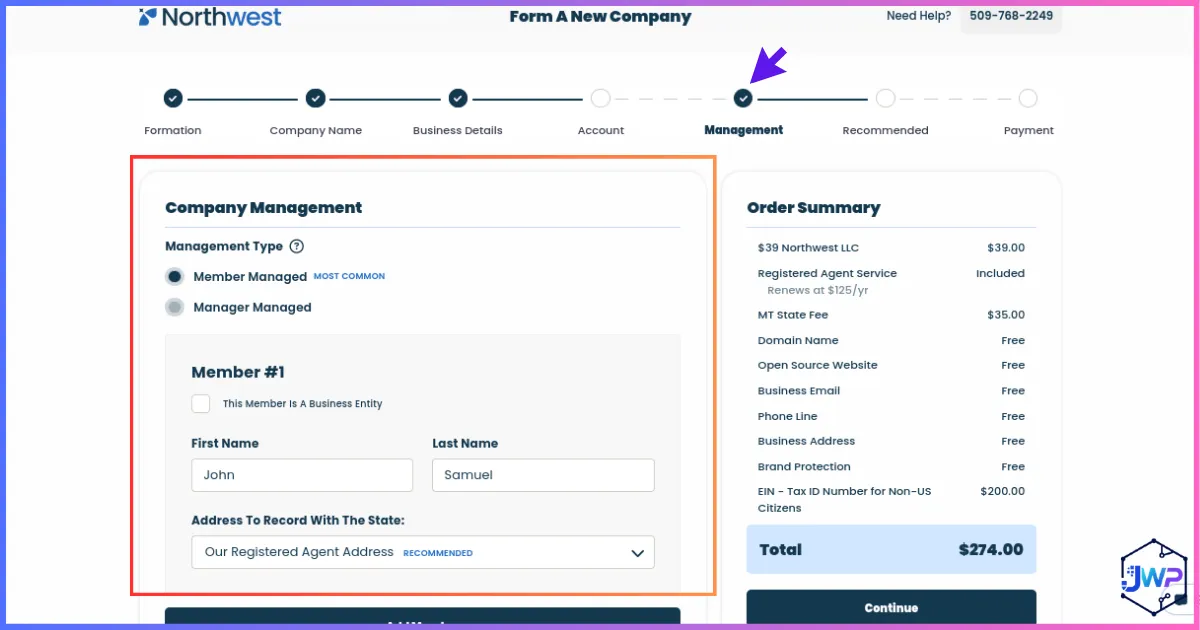
Enter company management details
Declare the management structure (member-managed for solo founders) and the owner’s details – name, residential address, and passport-based identity information. Chadian passports are accepted; nothing on this screen requires US status.
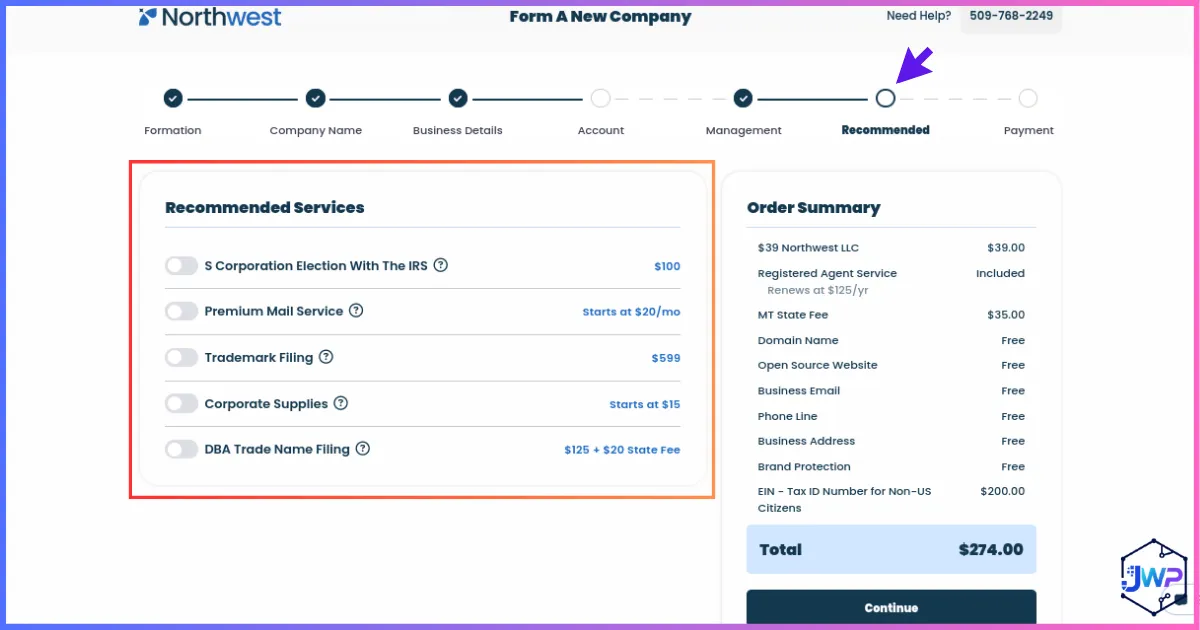
Review optional recommended services
Mail forwarding, certified copies, compliance monitoring and similar add-ons appear here. Honest advice: skip anything you can’t justify. Mail forwarding is the only one most non-residents eventually add.
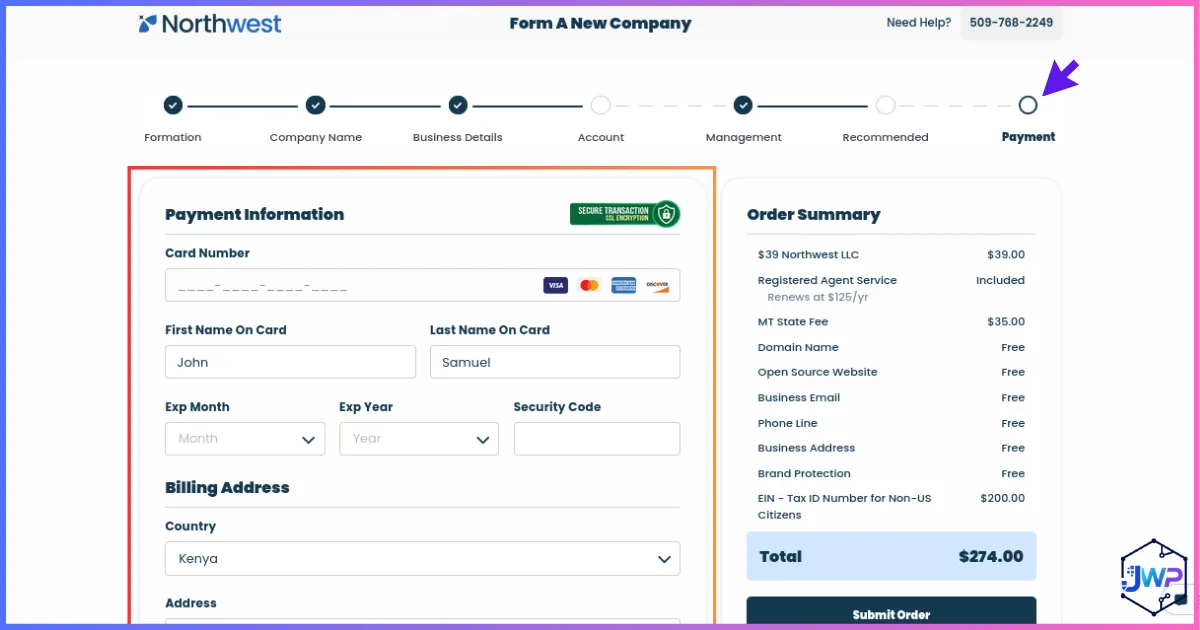
Enter payment information and submit
You’ll see the final breakdown – $39 service fee + your state’s filing fee (+ any add-ons) – before paying by card. After submission, Northwest prepares and files the Articles; you’ll receive the stamped formation documents by email once the state approves. Funding note for Chadian founders: with bank penetration in the low teens and retail international cards scarce, most formation payments are made through a diaspora-based route: a France/US/Canada-based relative’s card or Wise account, your own Wise/Payoneer balance funded by client revenue, or a domiciled foreign-currency card from a N’Djamena-based bank (ask Société Générale Tchad, Ecobank Chad, Orabank Tchad or BSIC about their international card products and documentation requirements). The amount is small ($139+), but arrange the route before checkout day to avoid half-finished orders.
After Formation: EIN, Operating Agreement, Banking & Getting Paid
1. Get your EIN (the foreign-founder route)
- Download Form SS-4 from IRS.gov and complete it for your LLC. On line 7b, leave SSN/ITIN blank and mark the foreign-owner indicators as instructed.
- Submit by fax (using the current international fax number published in the SS-4 instructions) or by mail if you prefer paper trails.
- Wait. IRS guidance suggests ~4 weeks by fax and 4-5 weeks by mail; foreign applications commonly land in the 3-8 week window during peak seasons. Paid formation-service EIN add-ons use the same IRS channels – they save effort, not time.
2. Adopt an operating agreement
Even single-member LLCs should sign one: banks, Stripe-style processors and marketplaces routinely request it, and it reinforces the liability shield by evidencing corporate separateness.
3. Open a US business bank account – from N’Djamena, Moundou or the diaspora
- Mercury and Relay: US fintechs that onboard non-resident-owned LLCs with EIN + formation docs + passport; no US visit required. Chadian-owned entities pass standard KYC; expect a few extra questions about business purpose given Sahel-region risk rating.
- Wise Business: multi-currency USD/EUR/GBP account details; works well for diaspora-based founders resident in Wise-supported countries (France, the US, Canada and Cameroon are common bases for the Chadian diaspora).
- Payoneer: receiving accounts for marketplaces (Amazon, Upwork, app stores) – available to Chadian residents, which makes it a useful bridge while you wait on the full bank account.
PayPal needs care: a US PayPal business account generally expects US tax status, so most Chadian owners route client payments to Mercury/Wise instead. Our walkthrough on creating a US PayPal account as a non-US resident covers the eligibility realities and workarounds that stay compliant.
4. Invoice and get paid
Issue invoices from the LLC (US entity name + EIN + US bank details). For US clients paying for services you perform in Chad or from the diaspora, provide Form W-8BEN (you, the foreign individual owner, since a single-member LLC is disregarded). Because Chad has no income tax treaty with the US, you cannot claim treaty withholding relief – services performed entirely in Chad with no US permanent establishment are generally outside US taxing rights regardless, but FDAP income like royalties and dividends remains subject to the standard 30% withholding. More in the treaty section below.
US Taxes for Chadian LLC Owners: What You Owe (and What You Don’t)
The income-tax picture
A single-member LLC owned by a non-resident alien is a disregarded entity: the IRS looks through it to you. If you have no US trade or business – no US office, no US employees, no dependent agents in the US, and services performed from Chad or a third country outside the US – your business income is generally not US-source and owes $0 US income tax. There is also no US self-employment tax for non-residents on foreign-performed services.
The filing you must not skip: Form 5472
Foreign-owned single-member LLCs must file Form 5472 together with a pro-forma Form 1120 every year – even with zero US tax and zero US activity. The failure penalty is $25,000 per violation under IRC §6038A. See the official IRS Form 5472 guidance for the current filing mechanics.
Other US tax touchpoints
- State level: Wyoming/Delaware-style LLCs with no in-state activity generally owe no state income tax, but the franchise/annual report fees in the charts above still apply.
- Sales tax / marketplace rules: selling digital or physical goods into US states can create economic-nexus sales-tax obligations independent of income tax – get advice before scaling e-commerce.
- Multi-member LLCs: become partnerships (Form 1065 + foreign-partner withholding rules) – a materially harder compliance load; structure deliberately.
- BOI reporting: under FinCEN’s 2025 interim final rule, US-domestic LLCs are not currently required to file Beneficial Ownership Information reports; foreign-formed entities registered in the US remain in scope. Rules are in flux – re-check FinCEN before assuming permanence.
No US-Chad Tax Treaty: What That Means in Practice
Like its CEMAC neighbours Cameroon, Gabon, Equatorial Guinea and the Republic of the Congo – and like Sudan, Niger and Nigeria – Chad has no bilateral income tax treaty with the United States. The US Treasury’s tax treaty table lists no operative treaty for Chad. This is an important factual anchor for Chadian founders planning long-term profit repatriation: nearly everything written for francophone African founders applies to you.
What the absence of a treaty means
- Standard withholding applies: US-source FDAP income (dividends, royalties, certain rents) paid to you as the disregarded owner of the LLC is generally subject to the full 30% US withholding, with no reduced treaty rate to claim.
- W-8BEN claims are limited: you can still file W-8BEN to certify foreign status and avoid backup withholding, but you cannot claim treaty-reduced rates on FDAP income – there is no treaty article to cite.
- Services performed in Chad remain outside US taxing rights: business income from services performed entirely in Chad with no US permanent establishment is generally not US-source regardless of the treaty picture. The absence of a treaty does not create new US tax on your locally performed services.
- No treaty tie-breakers for residency conflicts: if you are diaspora-based (e.g. in France, the US or Cameroon), dual-residency questions are resolved under each country’s domestic law rather than a treaty – plan your physical presence deliberately.
What the absence of a treaty does NOT change
- It does not exempt US filing obligations. Form 5472 is still due. State annual reports are still due. The EIN is still required.
- It does not fix CEMAC transfer frictions. Moving money between your US LLC and XAF accounts is governed by BEAC exchange-control regulation, not by the absence of a treaty.
- It does not grant visa or immigration rights. Chad is not an E-2 treaty country; no treaty means no treaty-investor visa pathway either.
The Chad Side: BEAC, the CFA Franc & Getting Money Home
A US LLC does not switch off Chadian obligations – and the CFA-zone framework has a specific set of rules that every founder moving money between a US LLC and Chad must understand. The good news: the XAF is a convertible, euro-pegged currency (fixed at 655.957 XAF = 1 EUR), which makes the US-LLC-to-XAF corridor workable on paper. The constraint is double-layered: CEMAC’s procedural domiciliation rules and Chad’s extremely thin banking infrastructure.
How the CFA-zone exchange-control system works
- Who regulates: the Bank of Central African States (BEAC) issues the foreign-exchange regulation – currently Regulation No. 02/18/CEMAC/UMAC/CM – and the COBAC (Central African Banking Commission) supervises the banks that apply it. In Chad, authorized intermediary banks include Société Générale Tchad, Ecobank Chad, Orabank Tchad, Commercial Bank Tchad (CBT) and BSIC Tchad, all concentrated in N’Djamena with limited provincial presence.
- Transfers to the “exterior zone” must be domiciled: any transfer from XAF to a non-CEMAC currency or account (your US LLC’s Mercury account, for example) goes through an authorized bank with a supporting document – typically an invoice, contract or service agreement. This is normal for documented trade flows, but it means ad-hoc transfers are not the model; document everything as a business flow.
- Foreign-currency accounts are possible but scarce: residents can hold foreign-currency accounts with bank authorization, but uptake is low given limited banking penetration. Most founders will fund formation through a diaspora route and receive repatriated income as inbound XAF wires.
- Export-proceeds repatriation: CEMAC rules require export earnings (relevant if your LLC sells goods or services into the region) to be repatriated through authorized banking channels within set deadlines. If your business flow includes selling into CEMAC from a US entity, get local advice on domiciliation first.
Domestic taxes to keep in view
- Personal income tax (ITV/IPRS): progressive rates up to 30% on Chadian-source and (for residents) worldwide income, administered under the domestic tax code. As a Chadian tax resident, you are generally required to declare worldwide income – including distributions from your US LLC.
- Corporate income tax: the standard rate is 35% for local companies (with petroleum-sector operations following separate contractual regimes). This applies to Chadian-registered entities, not to your US LLC – but if you create a taxable presence in Chad (office, employees, dependent agents) while running a US entity, Chadian corporate tax and permanent-establishment questions arise. Get local advice before scaling domestic operations.
- VAT (TCA): Chad applies a VAT on domestic transactions (standard rate historically 18%); a US LLC invoicing foreign clients for services performed outside the country generally sits outside that net, but local-sourced supplies are different – get advice if you sell into the domestic market.
- No diaspora tax: unlike Eritrea, Chad does not levy a special tax on citizens abroad. Diaspora founders simply follow the tax rules of their country of residence, plus Chadian-source income rules.
US LLC vs a Local Chadian Company: Which Do You Actually Need?
Chad recognizes commercial companies under OHADA’s Uniform Act (the local equivalents are the SARL and SA, registered through the Commercial Court and the one-stop shop). For most internationally focused founders the two structures solve different problems – and many end up running both.
| Factor | US LLC (Wyoming) | Local SARL (Chad) |
|---|---|---|
| Best for | US/global clients, USD revenue, Stripe-style payments, international contracts | Domestic operations, hiring locally, selling into the Chadian market, public tenders |
| Formation cost / time | $139 all-in, 1-3 days | Higher notary and registration costs; several weeks through the guichet unique |
| Currency of revenue | USD held in US banks | XAF held in CEMAC banks |
| US tax filings | Form 5472 + pro-forma 1120 annually (~$0 tax if no US trade or business) | None – but no access to US banking rails |
| Local tax | None locally unless you create a taxable presence | Corporate income tax 35%, employer obligations, VAT registration |
| Getting paid by US clients | Clean – US entity, US bank, W-8BEN on file | Possible but slower; transfers domiciled with documentation |
| Banking infrastructure needed | None domestic – Mercury/Relay run the account | Full dependence on thin domestic banks |
| Raising US investment | Straightforward (especially Delaware) | Structurally awkward for US investors |
A common pattern for established operators: the US LLC contracts internationally and holds USD working capital, while a local SARL (or sole-proprietor registration) handles domestic delivery and employment. Intercompany invoices between them keep both tax and exchange-control files clean. Get advice before setting up the intercompany flow – transfer pricing and BEAC documentation rules apply.
Your Annual Compliance Calendar
| Task | When | Cost | Consequence of skipping |
|---|---|---|---|
| State annual report / licence tax (WY) | Anniversary month (state-dependent) | $60 (WY) | Administrative dissolution |
| DE franchise tax (if Delaware) | By June 1 | $300 | Penalties + interest + loss of good standing |
| Registered agent renewal | Yearly | ~$125 | Agent resigns → state notices missed → dissolution risk |
| Form 5472 + pro-forma 1120 | April 15 (calendar year; extensions available) | $0 DIY / ~$250-600 preparer | $25,000 penalty per violation |
| Chadian personal tax return (if tax-resident) | Per domestic schedule | Per domestic rates (up to 30%) | Local penalties and interest |
| Country-of-residence tax return (if diaspora-based) | Per local schedule | Per local rules | Local penalties and interest |
| BEAC/COBAC domiciliation paperwork for transfers | Per transfer | Bank charges | Transfer delays or rejection |
| Bookkeeping catch-up (Mercury + Wise + Payoneer) | Quarterly recommended | Time / software | Messy 5472 filings and domiciliation files |
Once money flows, decide deliberately how you’ll compensate yourself – our guide on how to pay yourself as an LLC compares draws, salaries and dividends for non-resident owners.
DIY vs Formation Services: What Should a Chadian Founder Do?
| Route | Cost | Effort | Best for |
|---|---|---|---|
| Full DIY (state site + own RA search + SS-4 fax) | State fee + RA fee only | High – you own every mistake | Experienced founders comfortable with US paperwork |
| Northwest ($39 + state) ⭐ | Low, flat, transparent | Low – guided form, in-house RA, mail scanning | Most non-residents; privacy-minded founders |
| Bizee / similar budget brands | Low headline price; upsells at checkout | Medium | Price-shoppers who read checkout screens carefully – see our Bizee walkthrough |
| Premium non-resident bundles (doola, Business Anywhere) | $299-$500+ | Lowest – banking introductions bundled | Founders who want concierge onboarding; compare in our doola review and Business Anywhere review |
For a fuller market comparison including current non-resident eligibility, see our roundup of the best LLC formation services for non-US residents.
Common Mistakes Chadian Founders Make (and How to Avoid Them)
❌ The mistakes
- Forming in California/New York “because it’s famous” and inheriting $800/yr or publication costs
- Skipping Form 5472 because “I owe no US tax” → $25k penalty exposure
- Letting the registered agent lapse → administrative dissolution → frozen bank account
- Trying to move LLC revenue through informal cash channels instead of domiciled bank transfers → exchange-control violations and unexplained-wealth risk
- Assuming the LLC grants US work rights or a visa pathway (Chad is not an E-2 country)
- Claiming treaty benefits on W-8BEN when no Chad-US treaty exists
- Running LLC revenue through personal accounts that pierce the liability shield
- Applying for the EIN twice out of impatience → duplicate EINs
- Ignoring Chadian tax residency – living in N’Djamena while earning through a US LLC still creates local filing duties
- Assuming a domestic bank card will just work for international checkout – funding routes must be arranged in advance in Chad
✅ The fixes
- Default to WY / NM for cost, DE only for fundraising
- Diary the 5472 from day one; budget a preparer
- Auto-renew the registered agent on the same card as your domain renewals
- Route every transfer through your authorized bank with an invoice or contract attached – treat domiciliation as a feature, not friction
- Treat the LLC as a payments/liability tool; handle immigration separately
- Use W-8BEN correctly: certify foreign status, do NOT claim treaty rate reductions
- Open Mercury/Relay/Wise immediately after EIN; invoice only from the LLC
- File SS-4 once, track the fax, wait the window out
- Declare worldwide income per Chadian rules if resident in-country; use foreign tax credits where domestic law provides them
- Lock in a diaspora funding route (relative’s card, Wise, Payoneer) before starting the order form
Use Cases: Who Benefits Most from a Chadian-Owned US LLC?
- ☐ Confirm your funding route for the formation payment (diaspora card, Wise/Payoneer balance, or domiciled foreign-currency card from a N’Djamena bank)
- ☐ Choose state (WY default / DE for fundraising / NM for minimum cost)
- ☐ Search & reserve your LLC name (must end LLC / Limited Liability Company)
- ☐ Order formation via Northwest ($39 + state fee) with registered agent bundled
- ☐ Receive stamped Articles of Organization + agent confirmation
- ☐ Sign operating agreement (keep with records, don’t file)
- ☐ File Form SS-4 by fax/mail for EIN (or use the paid add-on)
- ☐ Open Mercury / Relay / Wise Business account with EIN + docs
- ☐ Set up invoicing + W-8BEN without treaty claims for US clients
- ☐ Diary: state annual report, agent renewal, Form 5472 (April 15)
- ☐ Plan repatriation: pick your authorized intermediary bank, prepare domiciliation documents per transfer
- ☐ Get advice on Chadian domestic tax (if resident in-country) and country-of-residence tax (if diaspora-based)
- ☐ If you run local operations too, evaluate the local SARL + US LLC two-entity pattern with an OHADA adviser
FAQs: Forming a US LLC from Chad
Can a citizen of Chad 100% own a US LLC?
Do I need a US visa, SSN or ITIN?
Which state is best for someone living in N’Djamena, Moundou or Abéché?
How much does it cost in total for year one?
How long does the whole process take?
How do I pay Northwest from Chad?
Does Chad have a tax treaty with the US?
How do I get money from my US LLC into XAF?
Will I pay US income tax while living in Chad?
Is the CFA franc a problem for a US LLC?
Can I open a US business bank account without travelling?
Does owning a US LLC help me move to the US?
Should I form a US LLC or a local SARL?
What happens if I forget the annual report or registered agent renewal?
Will US banks treat me differently because Chad is in the Sahel?
Final Thoughts: Is a US LLC Worth It for Chadian Founders?
For Chadian NGO contractors, oil-sector consultants, translators, developers, traders and diaspora entrepreneurs serving US and global markets, a US LLC is arguably the single highest-leverage structural upgrade available – in one of the world’s most under-banked economies, it is often the only functional international payments structure: ~$139 to start in Wyoming, 1-3 days to exist, and a USD-denominated, liability-shielded business identity that bypasses the domestic banking gap entirely.
The honest context Chadian founders should hold is that the hard part is not the formation – it is the plumbing: no US tax treaty means structuring income around services performed outside the US; the CEMAC exchange-control regime means every meaningful transfer home is a documented bank transaction; and the domestic infrastructure gap means funding and repatriation routes must be planned around the diaspora and Payoneer rather than assumed. None of these are blockers. All of them reward founders who accept a diaspora-first setup, keep audit-grade books and take advice on both sides of the Atlantic.
The obligations are real but finite – a registered agent, an annual report, one IRS information return, per-transfer bank documentation, and honest tax planning in every jurisdiction where you have a filing obligation. Do it in the right order (funding route → entity → EIN → bank → invoicing → compliance calendar), avoid the $25,000 Form 5472 trap, respect the CFA-zone documentation regime, and the LLC becomes quiet infrastructure that pays for itself with the first international contract it unlocks.
Sources & Research Notes
All fees and rules verified September 2026 against the primary sources below. US state fees, IRS procedures, FinCEN rules, BEAC/CEMAC regulations, OHADA corporate law and Chadian domestic law change – confirm live before filing.
- US Census Bureau, Business Formation Statistics – annual US business applications exceeding 5 million since 2021.
- IRS – Form SS-4 instructions (EIN application; foreign applicant fax/mail routes; $0 cost) and IRC §6038A / Form 5472 penalty provisions ($25,000 per violation); official Form 5472 guidance at irs.gov.
- IRS – About Form 5472 (official filing requirements for foreign-owned US disregarded entities).
- FinCEN – Beneficial Ownership Information interim final rule (2025): domestic reporting companies exempt; foreign-formed registrants remain in scope.
- US Department of the Treasury – IRS Tax Treaty Table: confirms Chad has no operative bilateral income tax treaty with the United States.
- IRS – Publication 515 (Withholding of Tax on Nonresident Aliens and Foreign Entities) – standard 30% withholding on US-source FDAP income absent a treaty.
- BEAC (Bank of Central African States) – Regulation No. 02/18/CEMAC/UMAC/CM governing exchange operations in CEMAC: domiciliation of outward transfers, foreign-currency account rules, export-proceeds repatriation deadlines; CFA franc pegged at 655.957 XAF = 1 EUR.
- COBAC (Banking Commission of Central Africa) – prudential supervision of authorized intermediary banks in Chad (Société Générale Tchad, Ecobank Chad, Orabank Tchad, CBT, BSIC Tchad etc.).
- World Bank Global Findex – Chad’s bank-account penetration estimated in the low teens as a percentage of adults; internet penetration roughly 12% (ITU/World Bank estimates).
- Chadian Ministry of Finance / tax administration – domestic personal income tax framework (progressive to 30%) and corporate income tax (standard 35%); confirm current practice with a qualified local adviser.
- OHADA – Uniform Act on Commercial Companies and Economic Interest Groups (local SARL/SA framework referenced in the comparison section).
- Wyoming Secretary of State – LLC filing fee ($100) and annual report licence tax (minimum $60).
- Delaware Division of Corporations – LLC formation fee ($90), $300 annual franchise tax; entity counts and Fortune 500 incorporation statistics.
- New Mexico Secretary of State – $50 LLC filing fee; no annual report requirement for LLCs.
- Florida Division of Corporations (Sunbiz) – $125 formation ($100 articles + $25 registered agent designation); $138.75 annual report.
- Texas Secretary of State – $300 LLC formation fee; Comptroller franchise-tax no-due threshold (~$2.47M).
- California FTB / SOS – $70 formation, $800 minimum annual franchise tax, $20 biennial statement of information.
- Nevada Secretary of State – initial fees ($75 articles + $150 initial list + $200 business licence) and annual renewals.
- Northwest Registered Agent – published formation pricing ($39 + state fee) and registered-agent renewal pricing ($125/yr).