How to Form a US LLC from Philippines
You can create a US limited liability company while living in Manila, Huye, Musanze or elsewhere in Philippines. The state filing is usually the simple part. The important choices are whether the entity fits your business, how Philippinesn tax and foreign-currency rules apply, whether a bank accepts your residence and activity, and what the IRS expects each year. This guide walks through those questions and the full Bizee order flow.
Quick Answer: How to Form a US LLC from the Philippines
A Philippine citizen or resident can generally own a US LLC without a US co-owner, Social Security number or trip to America. Choose the formation state according to real US activity and annual charges; appoint a registered agent with an in-state physical address; file the formation document; adopt an operating agreement; obtain an EIN from the IRS; then apply to a financial provider that accepts your actual residence, ownership and business activity.
The United States and the Philippines have an income tax treaty, and the Philippines is an E-1 and E-2 treaty country. That does not mean every US LLC automatically receives reduced tax or qualifies its owner for a visa. Tax benefits depend on the type of income, beneficial owner, treaty residence, entity classification and required documentation. Philippine citizens residing there are generally taxable on worldwide income, so a US entity does not remove Philippine tax duties.
New Mexico has the lowest one-time state filing fee in our comparison at $50, but the formation fee is only one part of the cost. Budget for a registered agent, recurring state charges, tax preparation, local registration and payment-provider costs. The IRS does not charge for an EIN application.
Table of Contents
- Why consider a US LLC?
- Eligibility and LLC basics
- Choosing the formation state
- True costs and charts
- Preparation and documents
- Bizee filing walkthrough
- Getting your EIN
- Banking and payments
- US income and information tax
- US–Philippines income tax treaty
- Philippinesn tax and currency rules
- BOI and privacy
- Compliance calendar
- DIY versus service
- Use cases and mistakes
- Launch checklist
- FAQs
- Final decision guide
Why a Founder in the Philippines Might Want a US LLC
A US LLC can give a Philippine entrepreneur a US contracting entity for software, consulting, design, e-commerce, digital products or other cross-border work. It can hold business contracts and intellectual property and may make some US customers or platforms more comfortable doing business. Whether that benefit is worth the additional filings depends on what customers actually require and whether they can already work with a Philippine business.
Do not assume a US entity guarantees access to a US bank, payment processor, marketplace or advertising account. Providers review beneficial owners, residence, business model and source of funds. Some accept foreign-owned LLCs; others restrict countries or activities. Ask your target provider about Philippine-resident owners before paying formation and registered-agent fees.
For a broader regional overview, see our Asia guide. Related guides cover Singapore, China, India and Australia. Their home-country tax and currency rules differ.
US LLC Basics and Eligibility for Philippinesn Owners
US LLCs are created under state law. A single person can own all membership interests, and that person can generally live in Philippines. Most state formation filings do not demand US citizenship, US residency or a Social Security number. Ownership alone does not grant a US visa or work authorization. If you plan to work physically in America, immigration must be analyzed separately. The US State Department’s Philippines reciprocity schedule currently lists no E-1 or E-2 treaty for Philippinesn nationals.
| Term | What it means | Why it matters from Philippines |
|---|---|---|
| Articles or certificate of organization | The state filing that legally creates the LLC. | Keep the approved copy for bank and tax use. |
| Registered agent | An in-state person or company that receives official and legal notices. | Your Manila address cannot replace the required state agent. |
| Operating agreement | Private rules for owners, management and distributions. | Useful even with one owner and often requested by banks. |
| EIN | Federal Employer Identification Number issued by the IRS. | Applying directly is free; most banks request it. |
| Disregarded entity | Default US federal income tax classification of a one-member LLC. | Income tax generally follows the owner, while special LLC information reporting can still apply. |
| Foreign qualification | Registration to do business in a US state other than the formation state. | May be needed if the company has real US operations elsewhere. |
If a Philippinesn company rather than an individual will own the LLC, prepare that company’s registration, directors, shareholders and ultimate-owner information. This can alter US tax forms, Philippines accounting and banking diligence. A US LLC and a Philippinesn company remain separate legal entities even if one owns the other.
Choose a State Based on Real Operations and Cost
If the LLC will have a US warehouse, employees, office or regular physical operations, examine that state first. Filing in a different low-fee state may add a second registration and tax calendar. For a genuinely remote services business run from Philippines with no US place of business, founders often compare New Mexico, Wyoming and Delaware.
| State | Formation filing | Routine state maintenance | Reason to choose it |
|---|---|---|---|
| New Mexico | $50 | No routine LLC annual report under current state rules. | Low stated government costs for a remote small business. |
| Wyoming | $100, plus any online payment charge. | Annual report and license tax of at least $60; more if Wyoming assets require it. | Founder comfortable with an annual report and its rules. |
| Delaware | $110 | $400 annual LLC tax due June 1; no annual Delaware LLC franchise-tax report. | Investors or counsel specifically require Delaware. |
See the Wyoming filing form, Wyoming annual guidance, New Mexico business portal, and Delaware’s fee schedule and annual tax page. Check the live state portal before filing. Service, agent, payment processing and any other-state fees are separate.
Column chart: one-time state filing fee
Government filing charges in USD, cited above. Excludes provider and agent fees.
Horizontal bar chart: minimum routine state charge per year
State charges only; registered agent and any other-state duties are additional.
New Mexico’s simple maintenance can appeal to a solo founder. Wyoming has an explicit annual report with a modest minimum charge. Delaware is useful when there is an investor, lawyer or commercial reason, not because every internet business needs it. Public owner-name differences between states do not make a company invisible to banks or authorities; read our LLC privacy guide for that distinction.
The Real First-Year and Ongoing Costs
Start with the government fee, then add the registered agent and any formation service. Check whether an advertised package includes an agent for a limited period and what it costs on renewal. Optional EIN help, operating agreement packages, mail service and tax consultations can change the checkout total. The IRS EIN is free when you apply directly. Keep a separate budget for US and Philippines tax work.
| Item | When paid | Budget treatment | Required? |
|---|---|---|---|
| State formation filing | Once | $50 NM, $100 WY, $110 DE in our comparison. | Yes. |
| Registered agent | Usually annually | Request the first-year and renewal price in writing. | Yes. |
| Formation-service package | At checkout | Price varies; review the live Bizee total. | No; direct filing is allowed. |
| EIN | Once | $0 if requested directly from the IRS. | Commonly needed for banking and filings. |
| State annual fee | After formation | Depends on state and possible operations elsewhere. | Where applicable. |
| US tax preparation | As required | Ask whether the quote includes Form 5472, any owner return and treaty analysis. | Facts determine forms; specialist help is often sensible. |
| Philippines tax and payment setup | At launch and yearly | Include BIR, bank and foreign-currency advice where relevant. | Depends on activity. |
Donut chart: illustrative $200 Wyoming setup budget
Illustration only, not a Bizee or registered-agent price quote. Taxes and professional fees excluded.
Line chart: three-year minimum state-only cost
Model adds one minimum state charge in each year after formation. Delaware’s actual tax assessment depends on the year formed. Other costs excluded.
Compare the live checkout before paying.
Review Bizee’s package, government filing fee, registered-agent term and optional services.
See Bizee LLC options →What to Prepare Before You File
Decide whether you or an existing Philippinesn company will own the LLC. That determines the operating agreement, bank ownership chain and tax analysis. Write down the real work location, customer countries, expected receipts and how you will pay suppliers. If you plan to sell physical goods, include inventory and shipping locations. A short plan will expose issues before they become expensive changes to state records.
- Current passport and residential-address evidence for each owner or manager.
- Two or three compliant LLC names, checked with the chosen state.
- Ownership percentages and the choice of member management or manager management.
- A truthful description of products, services, customers and payment flows.
- The registered agent’s legal name and physical in-state address.
- Reliable email and phone contact from Philippines.
- A plan for BIR registration, invoices, receipts and foreign-currency records.
State name availability does not mean a trademark is available. Search relevant brands, web domains and marketplaces separately. Use the same legal spelling on the state filing, IRS Form SS-4, operating agreement and bank application. Inconsistent ownership or address data can delay a financial provider’s review.
The registered agent is not your US office
An agent accepts lawsuits and official notices at a physical address in the formation state during business hours. Its address can satisfy that statutory requirement without becoming your operating address. If you work in Manila, tell banks and customers where you actually work. Ask the agent how it sends notices, what it scans, whether it forwards ordinary mail and what it charges after any introductory year.
Step by Step: Forming the US LLC Through Bizee
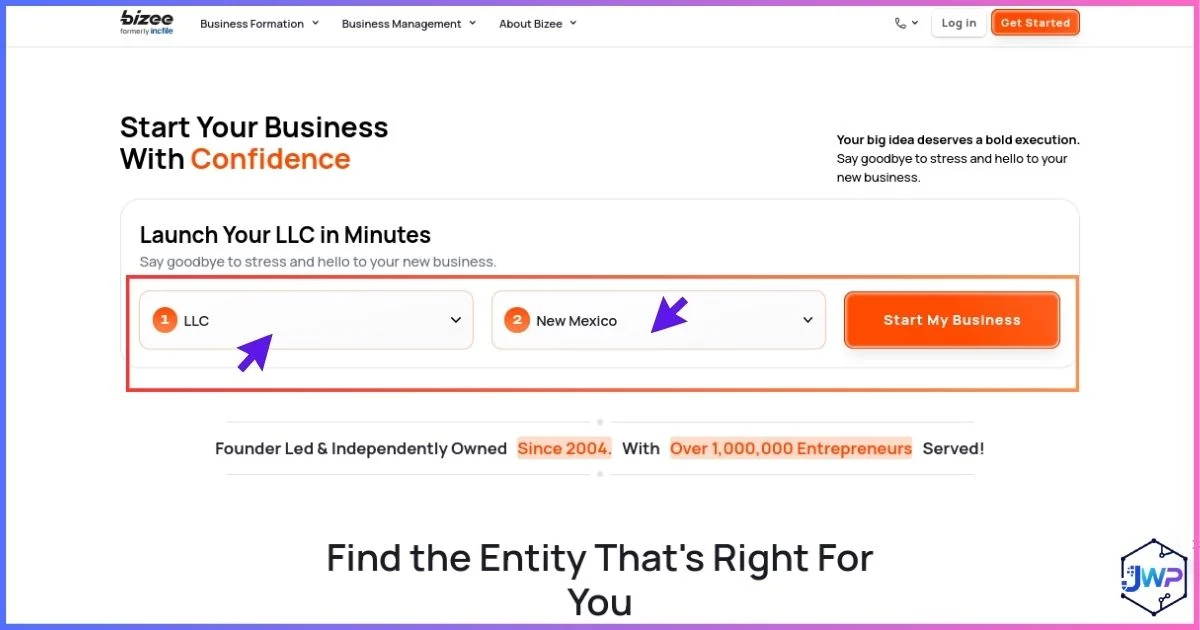
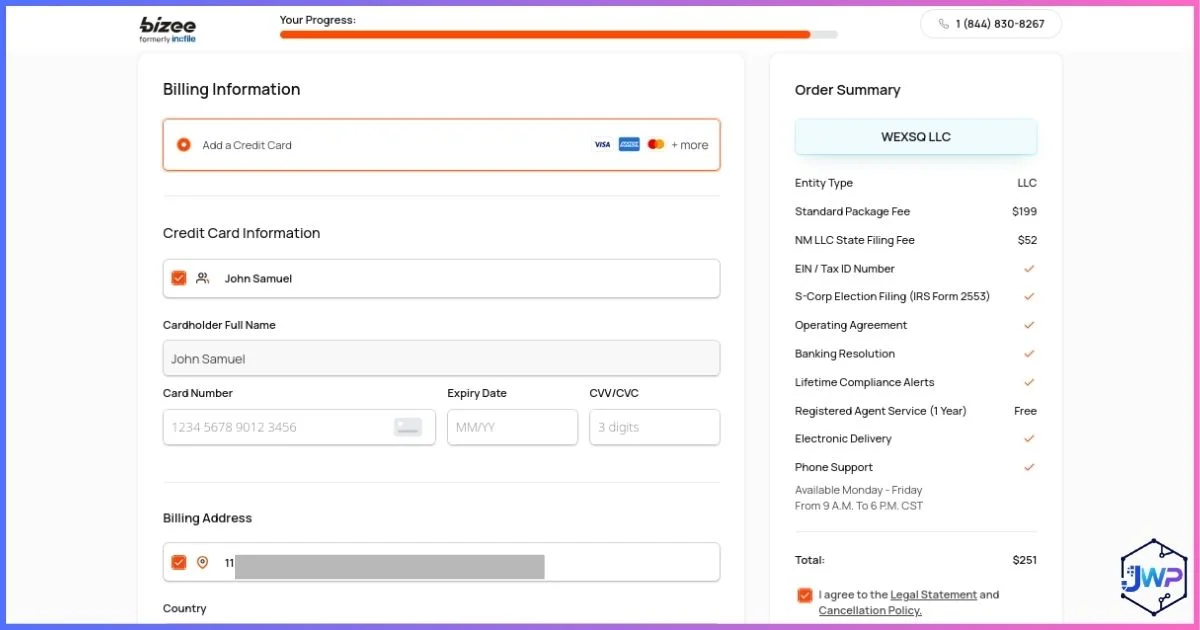
The supplied Bizee screenshots show a 14-step order flow. They are illustrations, not a price or availability guarantee. Screen wording, offers and government charges can change. Review every term in the live checkout. Filing directly with the state and hiring an agent separately is also possible.
Choose an LLC and formation state
Select LLC rather than a corporation, then choose the state based on real US operations, annual state charges and any investor requirements. A Wyoming filing will not remove a second state’s rules if the business actually operates there.
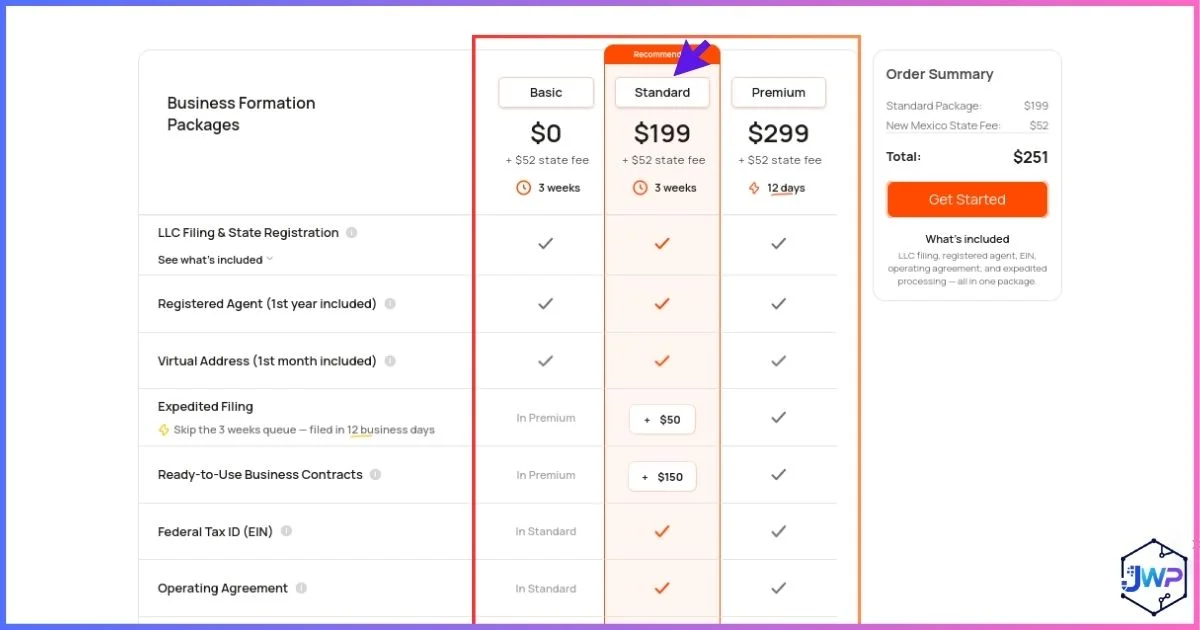
Compare packages
Read the complete package table. Identify the government filing fee, provider fee, registered-agent period and renewal price. Keep optional add-ons separate from what is legally needed to create the entity.
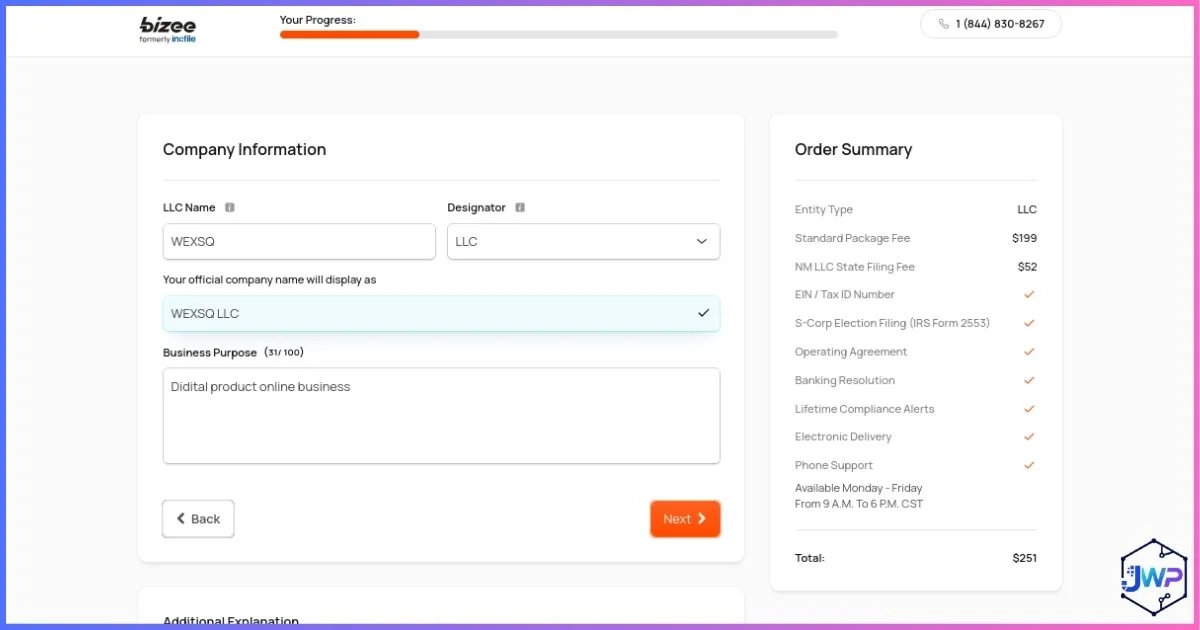
Enter company information
Use the exact LLC name checked with the state and a clear description of what the business sells. The bank may later compare this description with your website, contracts and invoices.
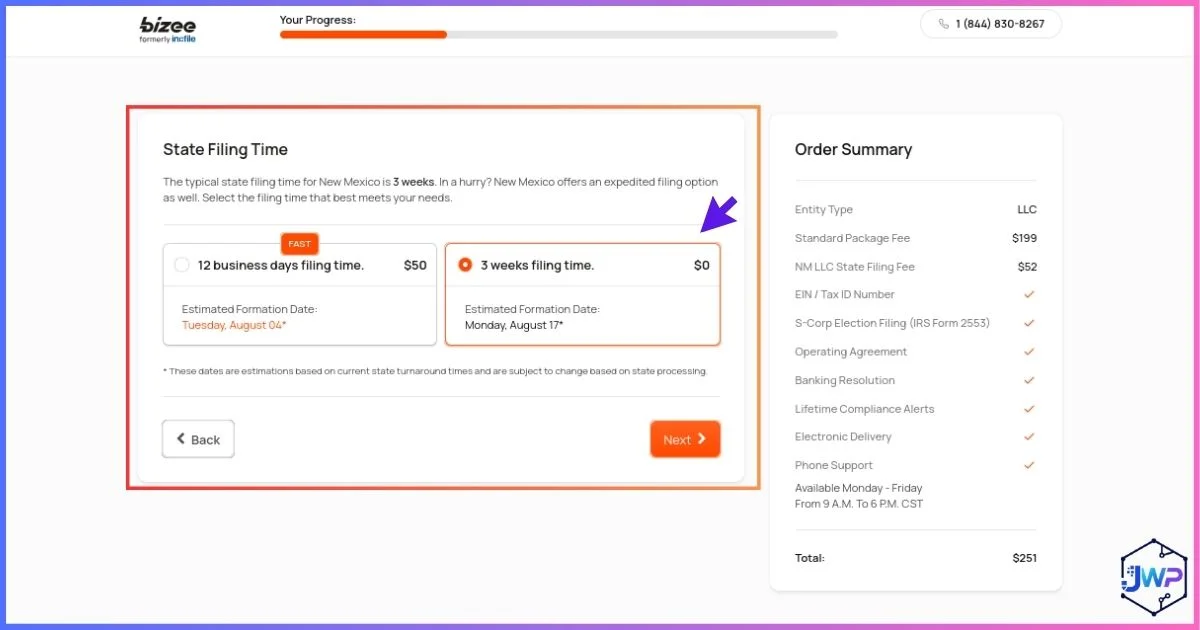
Choose state filing speed
Use standard processing unless a genuine commercial deadline justifies an expedite charge. Faster state approval does not speed the IRS EIN or guarantee a bank account.
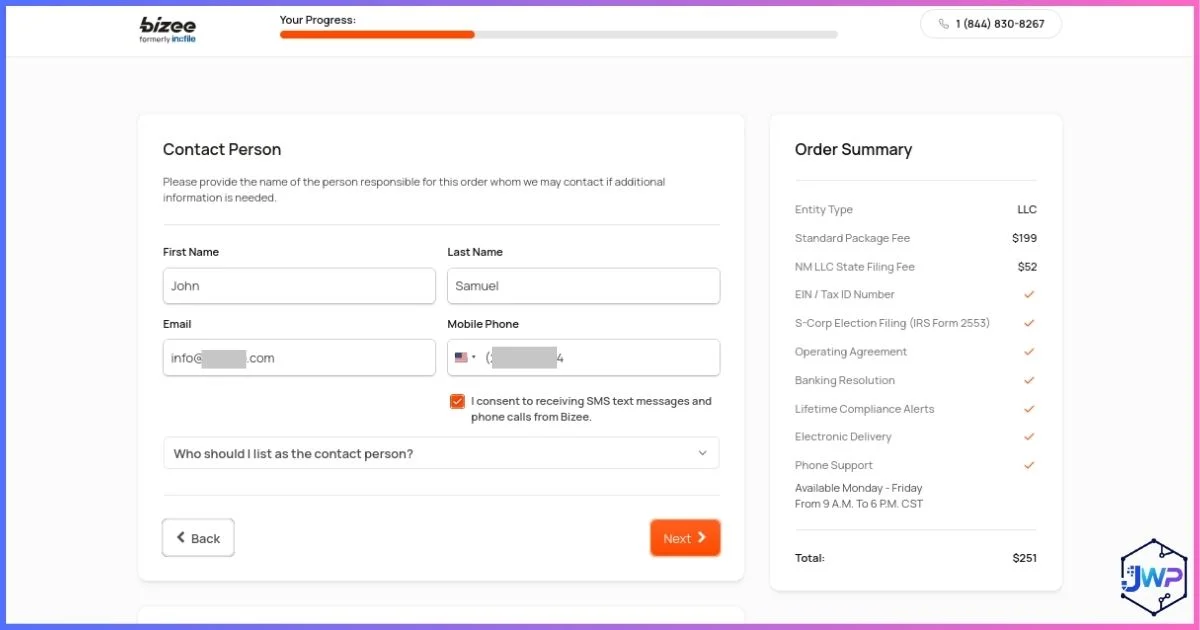
Provide a contact person
Use an email and telephone number that work reliably from Philippines. Formation services may need a quick answer if a name is unavailable or a state filing needs correction.
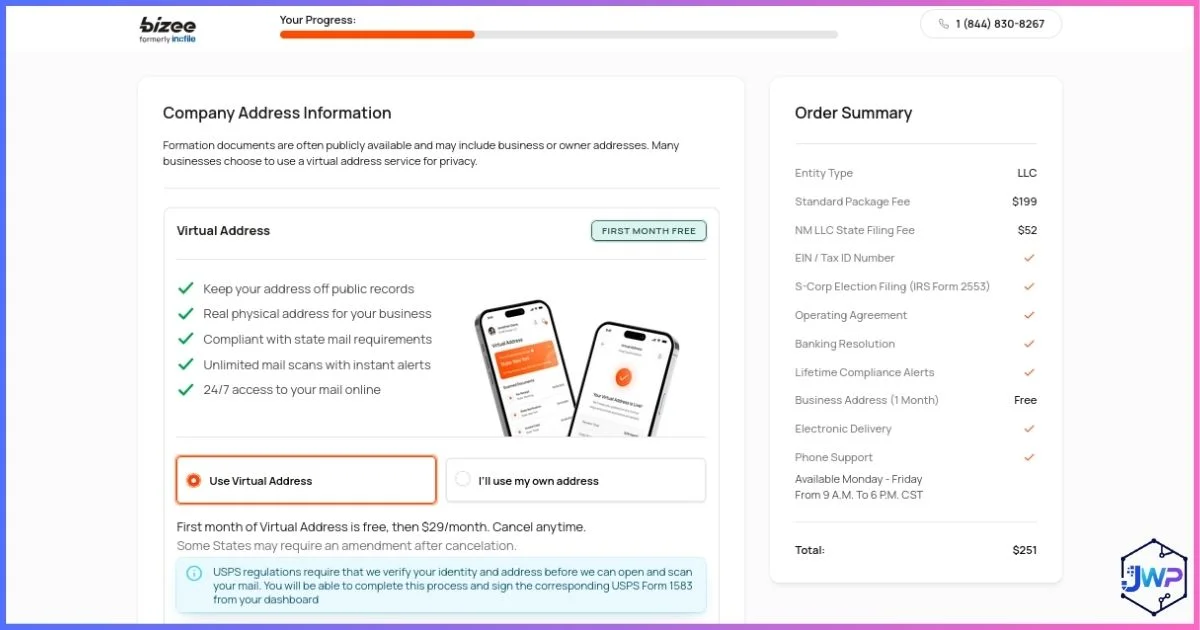
Give accurate address details
Distinguish your real Philippinesn operating address, mailing address and the registered-agent address. An agent office is not proof that your business has employees or premises in the United States.
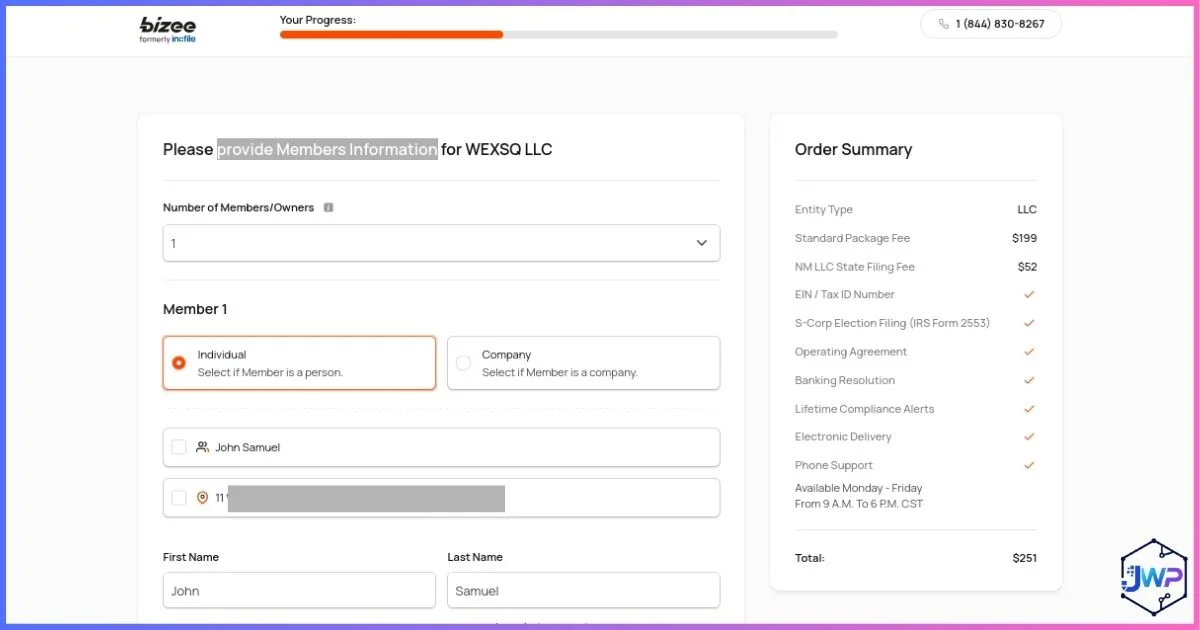
List members and managers
Enter the actual owner and ownership percentage. If a Philippinesn company owns the LLC, document that company and its ultimate owners rather than using a director as a stand-in personal owner.
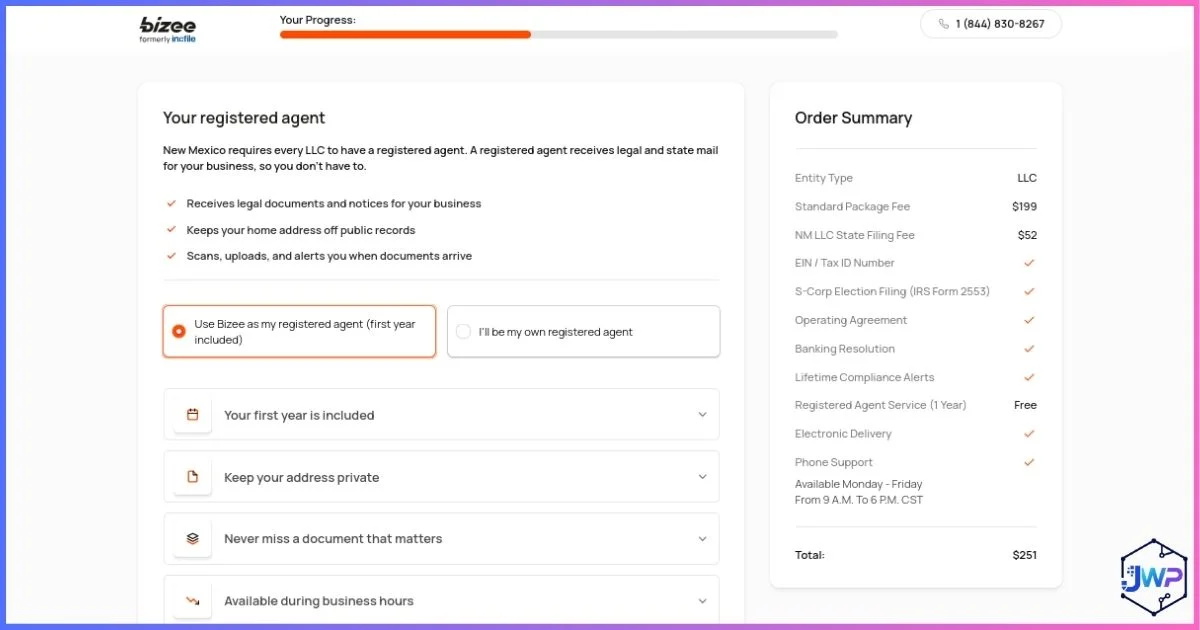
Confirm the registered agent
Choose Bizee’s agent service or another qualified in-state agent. Read the first-year term and renewal policy, and make sure you know where official notices will be sent.
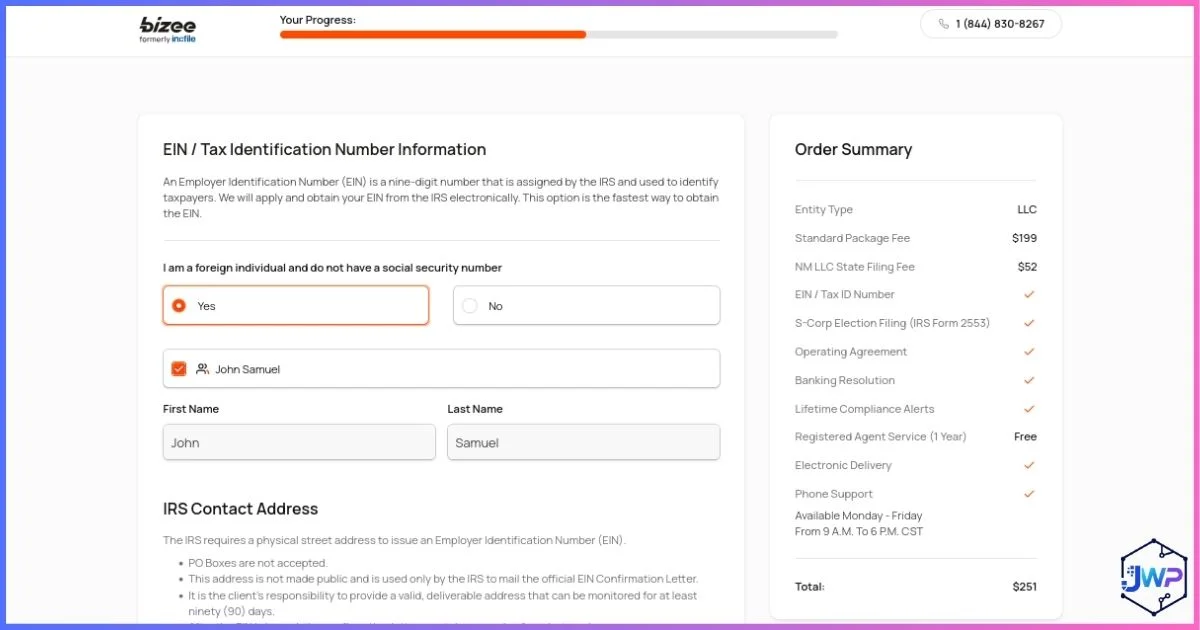
Decide on EIN assistance
The IRS issues an EIN for free. A provider may charge for preparing or transmitting Form SS-4. If you pay for help, confirm the responsible party and tax classification are correct.
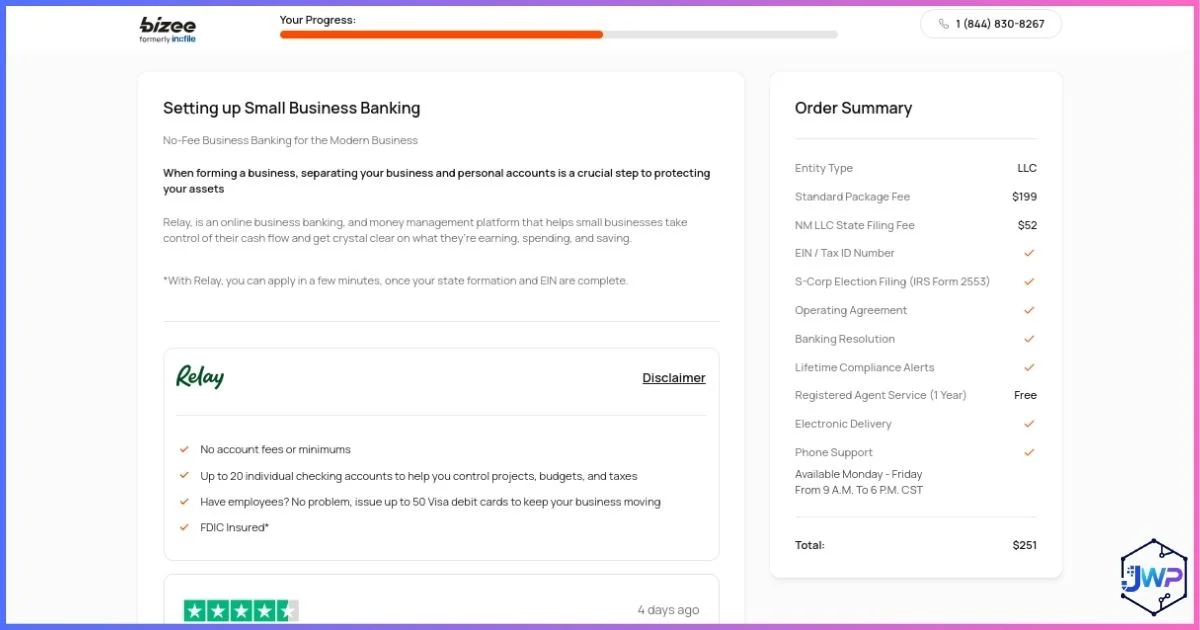
Consider banking later
A promoted account is only an offer to apply. Verify that the provider accepts beneficial owners resident in Philippines and supports your activity before treating it as your launch plan.
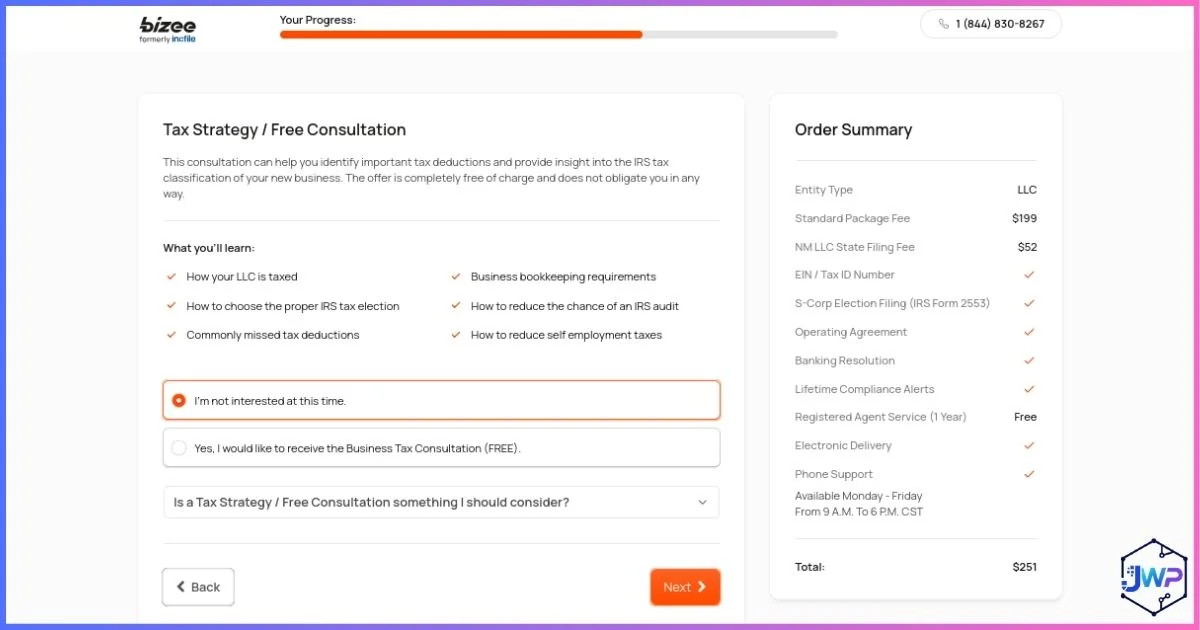
Assess tax strategy offers
Ask whether any consultation covers nonresident owners, foreign-owned disregarded entities, Form 5472, Philippinesn tax residence and the US–Philippines income tax treaty and its eligibility rules. A generic call may not answer those questions.
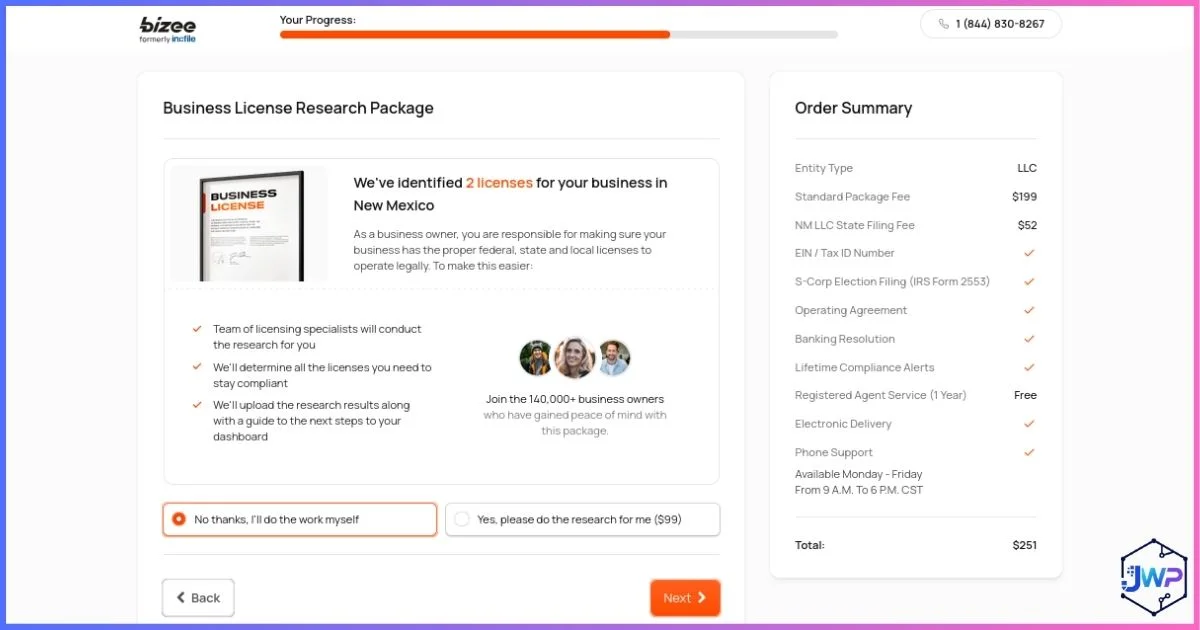
Assess license research
The LLC certificate is not a universal operating license. US sales tax, regulated activities and Philippinesn local obligations may each need separate analysis. Buy research only if its scope fits your business.
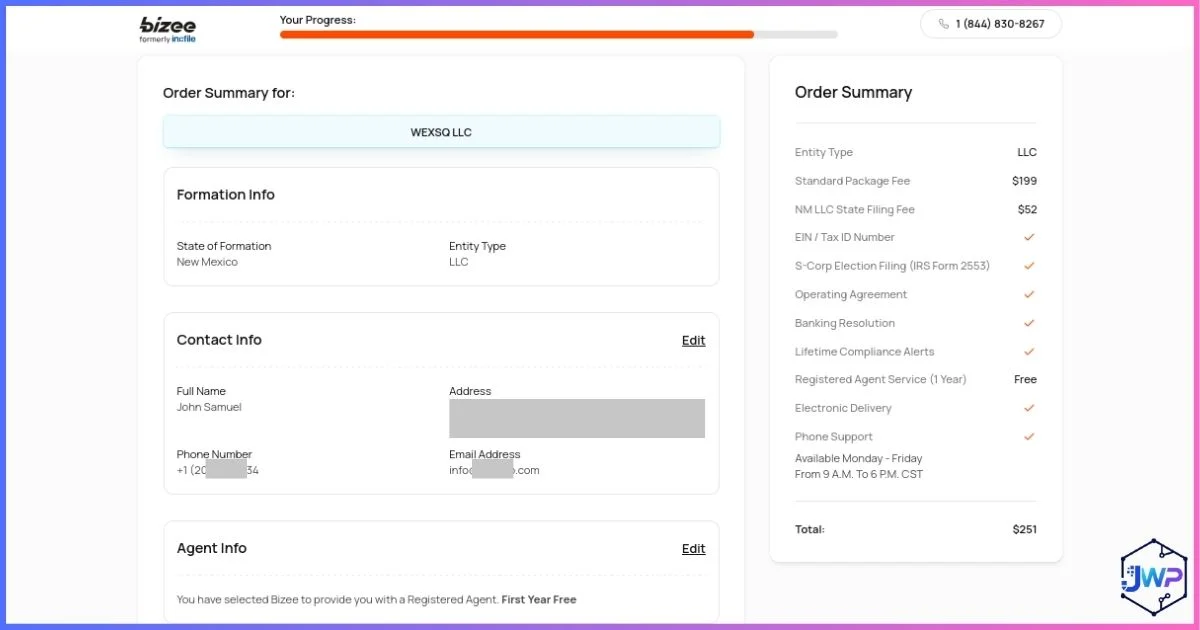
Audit the order summary
Check the company name, state, members, agent term, filing speed, optional services, subscriptions and total due. Save the summary and correct errors before payment.
Pay and save approved documents
Keep the receipt, then wait for state acceptance. After approval, download the stamped state document, agent details and operating agreement. Payment to a service does not itself create the LLC.
How to Obtain an EIN from Philippines
The EIN is the LLC’s federal tax identification number. It is commonly requested for banking and required for several filings. The IRS does not charge to issue one. Apply after the state approves the LLC so the legal name and formation date match the state document. International applicants who cannot use the online assistant can follow the IRS’s phone, fax or mail procedures. Check the live IRS EIN page for current eligibility, contacts and processing information.
- Complete Form SS-4 with the exact LLC name, responsible party, address and reason for applying.
- Use the actual individual who controls the entity as responsible party. A registered agent or formation-company employee should not be inserted merely to show a US person.
- If the responsible party does not have and is not eligible for an SSN or ITIN, follow the Form SS-4 instructions for line 7b. Do not invent a number.
- For a foreign-owned US disregarded entity requesting an EIN to file Form 5472, use the special line 9a description specified by the IRS.
- Save the completed application and IRS confirmation. If processing takes longer than the IRS’s stated interval, inquire about the existing application rather than sending repeated applications.
An EIN service can charge for preparing the form, but it does not own or sell the government number. The IRS number remains free. If the LLC has two members, an elected corporate classification or a company owner, its entries and eventual tax filings may differ from the solo-individual example. Resolve classification before sending the form.
Banking, USD Receipts and Payment Platforms
State approval and an EIN make a banking application possible, but account opening is the bank’s separate decision. The provider can review Philippinesn residence, identity, ownership, business model, countries of customers, expected payment amounts and source of funds. Some US fintechs accept foreign-owned LLCs, while others limit residence countries or industries. Policies change, so check eligibility before selecting an LLC simply to use a particular provider.
| Bank or platform request | What to supply | Avoid this mistake |
|---|---|---|
| Entity existence | Approved articles or certificate and EIN confirmation. | Submitting a Bizee order receipt as if it were state approval. |
| Ownership and authority | Signed operating agreement and full parent-company chain if relevant. | Listing a nominee instead of the real owner. |
| Identity and location | Valid passport and genuine residential and operating addresses. | Calling the registered-agent office your workplace. |
| Business evidence | Website, contracts, sample invoices and explanation of expected flows. | Using contradictory activity descriptions. |
| Source of funds | Records for initial capital and later owner transfers. | Mixing personal and company deposits without explanations. |
Maintain an alternative plan if your first provider declines. An account rejection does not necessarily mean the LLC filing failed. Ask what documents can resolve a factual issue, and apply elsewhere only if that provider serves your residence and activity. Never use someone else’s identity or a false address to bypass screening.
Where funds ultimately move matters. Keep a record when US clients pay the LLC, when the LLC pays a Philippinesn supplier, and when you draw profits personally. Philippines’s foreign-exchange regulation addresses foreign-currency accounts and capital-account transactions, and its foreign-currency directive explains permitted handling of receipts in covered situations. Ask an authorized Philippinesn bank how the current rules apply to your specific flows. Our Wise and Payoneer guides may help you compare payment tools, but their Philippines eligibility must be checked live.
US Taxes and Information Returns for Philippinesn Owners
US tax does not depend on the LLC certificate alone. It depends on owner identity, tax classification, income type and where business activity occurs. A one-member LLC usually defaults to disregarded status for federal income tax. A two-member LLC normally defaults to partnership status. An election to corporate treatment changes the tax return and possibly the owner-level results. If you are a US citizen or US tax resident who happens to live in Philippines, worldwide-income rules can apply to you; our US citizen LLC guide is a better starting point.
Services performed in Philippines
The IRS generally sources personal-service income where work is physically performed. A designer in Manila who completes a project there for a New York customer usually has foreign-source service income for US purposes even if the contract uses a US LLC and the money arrives in a US account. A week of billable work performed in New York may require an allocation. The source rule for services does not automatically cover royalties, digital licenses, advertising income, physical goods or US real estate. See the IRS services sourcing guidance.
A US office, employee, warehouse, or dependent agent can change the outcome. US-source income connected to a US trade or business may be taxed differently from passive US-source income. State income tax, sales tax, payroll and registrations can arise even when federal income tax is limited. Consult a US cross-border preparer for mixed activities and do not apply a “zero US tax” conclusion to the entire company merely because its owner lives in Philippines.
| Business example | Main tax question | Possible result to review |
|---|---|---|
| Philippinesn consultant works entirely in Manila for US clients. | Where were services performed, and is there any US business presence? | Foreign-source service income may be outside US federal income tax for a nonresident owner; Philippinesn tax still matters. |
| Founder performs paid work during a US trip. | How much of the fee relates to work physically in the US? | Potential US-source income, withholding and return filing. |
| Seller stores stock in a US warehouse. | Where is inventory sold and where are activities carried out? | Potential US trade, state registration and sales-tax nexus. |
| Creator licenses IP used in the US. | Is the payment a royalty, service fee or something else? | US-source royalty withholding can apply without a Philippines treaty rate. |
Form 5472: the filing many solo founders miss
For a wholly foreign-owned US disregarded LLC, the IRS treats the entity as separate for a limited information-reporting rule. It generally files Form 5472 attached to a pro forma Form 1120 when it has reportable transactions with a related party. Contributions to form or fund the LLC, owner distributions, loans and other transfers can be reportable. A company can therefore have no customers and still need the form. The IRS instructions also state an exception when there are no reportable transactions at all, so do not make an unconditional yearly filing claim.
The initial failure-to-file penalty is $25,000. A substantially incomplete form can be treated as a failure, and continued noncompliance after notice can produce more penalties. Foreign-owned disregarded entities have a specific filing address or fax procedure and extension instructions. Hire someone who actually handles these forms if you have owner advances, intercompany charges or a Philippinesn parent company. Save the documentation behind every related-party amount.
The US–Philippines Income Tax Treaty and E Visas
The United States and the Philippines have an income tax treaty. It can reduce or eliminate US tax on particular categories of income for a qualifying person, but it is not a blanket exemption for a US LLC. The treaty contains detailed rules for business profits, dividends, interest, royalties and personal services. Eligibility depends on residence, beneficial ownership, the kind of income and other conditions. IRS guidance says to consult the treaty text before claiming relief.
LLC classification is a key complication. A single-member US LLC is normally disregarded for US federal income tax unless it elects corporate treatment. Philippine tax law may classify the entity differently. Treaty benefits for income received through fiscally transparent entities depend on the treaty and applicable US rules. Do not put a treaty rate on Form W-8BEN or ask a payer to reduce withholding until a qualified cross-border tax professional confirms the beneficial owner, residence, treaty article and documentation.
The Philippines is also listed by the State Department as an E-1 treaty trader and E-2 treaty investor country. E visas require qualifying investment or substantial trade, an eligible enterprise, the required nationality and other conditions. An LLC certificate alone does not provide a visa, permission to work in the United States or a guarantee of approval. Consult a US immigration attorney if relocation or in-person work is part of your plan.
Pie chart: illustrative $100 US-source royalty and possible withholding
Illustration only: assumes a $100 US-source royalty paid to a foreign beneficial owner, no exemption or treaty claim applied at payment, and no other tax. A valid treaty claim may change the result. Service fees are not automatically royalties.
The US treaty does not replace Philippine tax rules. A Philippine resident citizen may owe Philippine tax on worldwide income, subject to applicable credits and other provisions. Keep US withholding certificates, 1042-S forms and payment records, and ask a Philippine tax adviser whether and how foreign tax credits apply to your specific income.
Philippine Tax, Currency and Business Registration Considerations
A US LLC does not determine your Philippine tax result by itself. The National Internal Revenue Code distinguishes resident citizens, nonresident citizens, overseas contract workers, resident aliens and foreign corporations. In broad terms, a Filipino citizen residing in the Philippines is generally taxed on income from sources within and outside the country. Nonresident citizens and aliens are generally taxed on Philippine-source income, subject to statutory rules and exceptions. Residence status and the LLC’s Philippine classification matter; do not assume a US entity makes receipts foreign-source or tax-free.
Where the work is performed matters
The BIR applies source-of-income rules. For personal services, the place where the work is physically performed is generally central to sourcing: payment by a US client or in US dollars does not by itself make services performed in the Philippines US-source income. A Philippine resident citizen may still have Philippine tax exposure on foreign-source income under the worldwide-income rule. Keep contracts, work records, invoices and customer details so the source and character of income can be established.
Local tax registration and VAT
If you operate from the Philippines, ask the BIR and a qualified local adviser whether you, a domestic company, a branch or another structure must register, issue compliant invoices, keep books, file returns or account for VAT. A foreign LLC may raise separate questions about local business registration and how its income is classified. The answer can depend on management, personnel, services, contracts and other facts—not only on the state where the LLC was formed.
VAT treatment depends on the transaction. BIR rules include conditions for zero-rating certain exported services; being paid from abroad or issuing a US invoice does not automatically prove that every service qualifies. Confirm current statutory conditions and documentation before treating a receipt as zero-rated or outside the VAT system.
Foreign currency and cross-border transfers
The Bangko Sentral ng Pilipinas publishes the Manual of Regulations on Foreign Exchange Transactions and related circulars. Philippine banks and regulated providers may require purpose details and documents for cross-border payments. Ask your bank what it needs for formation costs, capital contributions, service receipts, distributions, loans and tax payments. Use traceable business transfers, and retain statements, contracts, invoices and conversion records. Do not assume a particular payment platform or account is available to every resident or activity.
- How are you classified based on citizenship, residence and work location?
- How will the LLC be treated under Philippine law, and can the US treaty apply to a specific income item?
- Which BIR registration, invoicing, bookkeeping, income-tax and VAT duties apply?
- What documents and declared purposes are needed for inward and outward transfers?
- How should capital, withdrawals, reimbursements, loans and distributions be recorded?
- Can US tax paid be credited in the Philippines, and what proof is required?
Maintain separate books for the LLC and your personal or Philippine business finances. Reconcile USD statements to PHP records using a consistent method agreed with your accountant. Keep the exchange-rate source and date for each conversion used in local reporting.
BOI Reporting, Public Privacy and Ownership Records
As of September 2026, FinCEN says entities created in the United States are exempt from federal Corporate Transparency Act beneficial ownership information (BOI) reporting under its August 2026 final rule. This includes a domestic US LLC owned by a Philippinesn person. A Philippinesn company registering to do business in a US state is a foreign entity for this purpose and may need separate BOI analysis. Review FinCEN’s current guidance at the time of action because these rules have changed.
BOI exemption is not anonymity. The registered agent, state, IRS, banks and payment processors may require real owner details under their own rules. Keep the signed operating agreement, beneficial-owner chain, passport records and change history in a secure company folder. Update relevant state filings, bank records and IRS responsible-party information when control changes.
A First-Year and Annual Compliance Calendar
Put dates into a calendar as soon as the state accepts the LLC. Tax deadlines depend on classification, owner status and tax year, so ask a US preparer for the specific federal schedule. Separately identify the BIR obligations of the individual, any local company and any locally conducted activity. Registered-agent invoices and state notices should go to an email that is checked regularly.
| When | Action | Why it matters |
|---|---|---|
| At formation | Save state approval, agent details, operating agreement and owner information. | Needed for banking and later filing. |
| Before taking revenue | Confirm Philippines business and tax registration, banking route and VAT status. | US formation does not complete local compliance. |
| Monthly | Reconcile sales, expenses, owner capital, distributions and related-party transfers. | Supports US Form 5472 and BIR records. |
| By applicable US return deadline | Determine Form 5472/pro forma 1120 and any owner, partnership or corporate returns. | Forms vary by entity classification and transactions. |
| By the applicable BIR deadline | File the individual or entity income-tax return and other required declarations. | Deadlines depend on the taxpayer, tax year and filing type; confirm the current BIR calendar. |
| Wyoming anniversary month, if formed there | Submit annual report and license tax. | Maintains state good standing. |
| June 1 for a Delaware LLC | Pay Delaware’s annual $400 tax. | No Delaware LLC annual tax report is required, but payment is. |
| Every year | Renew agent; revisit banking, VAT, US state nexus and foreign-currency rules. | Business facts and official policies can change. |
If the business ends, formally dissolve the LLC with its state, close accounts and settle final filings and taxes. Simply ceasing to sell does not necessarily end state fees or registered-agent costs. Ask how liquidation proceeds should be recorded for Philippines tax and bank purposes.
File Directly or Use a Formation Service?
Direct state filing can be economical for a simple one-owner LLC if you are comfortable with state forms and have separately hired an agent. A formation service can organize submission and document delivery. It cannot guarantee a bank account, tax exemption, EIN processing time or Philippinesn compliance. Compare the provider’s current deliverables with what you would otherwise do yourself.
Direct filing may fit if
- The ownership is simple and fully documented.
- You understand the chosen state’s filing questions.
- You can appoint and monitor an agent.
- You will maintain your own records and deadlines.
Get specialist advice if
- A Philippinesn company owns the LLC.
- You hold US inventory or hire US staff.
- Royalties, investors or multiple owners are involved.
- Philippines classification or foreign-currency handling is uncertain.
Formation assistance and cross-border tax advice solve different tasks. A lower-priced package can be enough for a routine filing, while a tax specialist may still be necessary for the LLC’s first year. Ask any adviser exactly which forms, jurisdictions and follow-up questions their fee covers.
Use Cases and Mistakes to Avoid
- Forming before checking banking: a valid LLC may still be declined by a preferred provider. Check its Philippines eligibility and activity rules first.
- Calling all income tax free: BIR generally taxes resident individuals on domestic and foreign sources. US tax depends on income type and activity.
- Claiming a nonexistent treaty rate: the IRS does not list a US–Philippines income tax treaty.
- Ignoring owner transfers: initial funding or distributions may make Form 5472 relevant even before customer sales.
- Using the agent’s address as a false operating location: statutory contact is different from where the business actually works.
- Assuming exported services automatically qualify for zero-rated VAT: document and test the specific transaction against BIR rules.
- Choosing Delaware by default: its $400 annual tax should be justified by an actual business reason.
- Mixing company and personal spending: it weakens accounting and makes ownership transfers harder to explain.
For payout planning, our guide to paying yourself from an LLC explains US classifications. Ask a Philippinesn adviser how the chosen payment is treated locally.
Compare the live formation order.
Check every government charge, package feature, agent renewal and optional add-on against your actual needs.
Review Bizee LLC packages →Philippines-to-US LLC Master Checklist
- Describe the business, customer locations, owner residence and where work, staff and stock will be.
- Confirm a real commercial reason for a US entity and check provider eligibility for Philippines.
- Discuss BIR tax, registration, VAT and currency handling with qualified local advisers or a bank.
- Compare state filing and recurring costs, including any state with actual US activity.
- Check the company name and choose a registered agent.
- File directly or review the complete Bizee order before paying.
- Save state approval and sign an accurate operating agreement.
- Apply directly to the IRS for the free EIN or knowingly buy preparation help.
- Apply for banking using genuine identity and operating-address documents.
- Record customer receipts, expenses, owner funding and distributions from day one.
- Have a US preparer identify federal and state returns and a Philippines adviser identify local declarations.
- Calendar annual state, agent, IRS and BIR obligations.
Frequently Asked Questions
Can a Filipino citizen own 100% of a US LLC?
Do I need to travel to the United States or have a visa to form an LLC?
Can a Filipino LLC owner apply for an E-2 visa?
Does the United States have an income tax treaty with the Philippines?
Do I need an SSN or ITIN to obtain an EIN?
Which state should I choose if all work is in the Philippines?
Will a US LLC eliminate Philippine income tax?
If a US client pays me, is the income automatically US-source?
Does every US-source payment receive a treaty reduction?
Must my foreign-owned single-member LLC file Form 5472 if it has no profit?
Can I open a US business account from the Philippines?
Are services exported from the Philippines automatically zero-rated for VAT?
Do I need a federal BOI report for a US LLC?
What if I stop trading?
Final Decision Guide
A US LLC can help a Philippine founder when customers, contracts or partners have a clear reason to use a US entity. The formation steps are manageable: choose a state, appoint an agent, file accurate papers, sign an operating agreement, request the EIN and apply for banking with truthful ownership and operating information. The ongoing work is meeting tax and recordkeeping obligations in both countries.
Before filing, confirm your preferred financial provider supports your residence and business category; ask a Philippine tax professional about residence, LLC classification, income tax, VAT and registration; and ask a US cross-border preparer whether treaty relief applies to specific income. If relocating to the US is part of the plan, consult immigration counsel about E-1/E-2 eligibility and separate visa requirements.
Review the current formation terms.
Check Bizee’s live state fee, package contents, registered-agent renewal and optional services before ordering.
Explore Bizee LLC formation →Sources & Research Notes
Updated September 26, 2026. State-cost charts use published government figures. The budget donut and withholding pie are labeled illustrations, not provider quotes or predictions. Philippine tax, foreign-exchange, US treaty, immigration and FinCEN rules can change; verify current rules before acting.
- Wyoming Secretary of State: LLC filing form and annual report guidance.
- New Mexico Secretary of State: business portal.
- Delaware Division of Corporations: filing fees and annual LLC tax instructions.
- IRS: EIN for international applicants, Form SS-4 instructions and Form 5472 instructions.
- IRS: source of personal-service income, US income tax treaties, US–Philippines income tax treaty and IRS treaty tables.
- Philippine National Internal Revenue Code, Section 23 and BIR: taxation of foreign-source income.
- BIR ruling on source of service income and BIR tax guide.
- Bangko Sentral ng Pilipinas: foreign-exchange regulations and Foreign Exchange Transactions manual.
- US State Department: E-1 and E-2 treaty countries and E visa requirements.
- FinCEN: current beneficial ownership information guidance.
- Related guides: US LLC from Asia, Singapore, China, India, formation service comparison, Bizee walkthrough, LLC privacy and paying yourself from an LLC.