How to Form a US LLC from Rwanda
You can create a US limited liability company while living in Kigali, Huye, Musanze or elsewhere in Rwanda. The state filing is usually the simple part. The important choices are whether the entity fits your business, how Rwandan tax and foreign-currency rules apply, whether a bank accepts your residence and activity, and what the IRS expects each year. This guide walks through those questions and the full Bizee order flow.
Quick Answer: How to Form a US LLC from Rwanda
A Rwandan citizen or resident may generally own 100% of a US LLC without a US partner, visa, Social Security number or trip to America. Choose a state based on actual operations and ongoing charges; select an in-state registered agent; file the LLC’s formation document; sign an operating agreement; obtain a free EIN from the IRS; then apply to a bank or payment provider that supports your real residence and business.
Plan both sides of the border: Rwanda Revenue Authority (RRA) says resident individuals are generally liable for income tax on domestic- and foreign-source income. A US LLC therefore does not remove Rwanda tax merely because US customers pay it in dollars. Rwanda has no US income tax treaty on the IRS list, so a Rwandan tax resident cannot claim a bilateral treaty reduction on applicable US-source withholding. Record transfers between you and a wholly foreign-owned single-member LLC: Form 5472 can be required even when US income tax is zero.
The cheapest government formation fee in our three-state comparison is New Mexico’s $50. That is not the complete first-year cost: a registered agent, optional provider services, tax advice, bank charges and any state obligations where you actually operate must be budgeted separately.
Table of Contents
- Why consider a US LLC?
- Eligibility and LLC basics
- Choosing the formation state
- True costs and charts
- Preparation and documents
- Bizee filing walkthrough
- Getting your EIN
- Banking and payments
- US income and information tax
- No US–Rwanda tax treaty
- Rwandan tax and currency rules
- BOI and privacy
- Compliance calendar
- DIY versus service
- Use cases and mistakes
- Launch checklist
- FAQs
- Final decision guide
Why a Founder in Rwanda Might Want a US LLC
A US LLC is a state-created legal entity that can sign customer contracts, hold a business account if approved, and keep company obligations distinct from the owner’s personal transactions. For a Rwandan agency selling services to US clients, it may make procurement and invoicing easier. For a software founder, it may give a clear owner of contracts or intellectual property. An online seller may need a US legal entity for a particular marketplace. These are business reasons, not promises of lower tax.
Ask the customer or platform what it actually requires. A US company number alone may not satisfy a provider that also wants a US operating address, a supported residence country, or a particular owner profile. Confirm those requirements before choosing a state or paying for a package. If all your customers already contract comfortably with a Rwandan business, the extra US annual duties may bring little benefit.
Our Africa overview explains the regional starting point. Compare the Uganda, Kenya and Tanzania guides only for each country’s own home-side rules; none substitutes for a Rwanda analysis.
US LLC Basics and Eligibility for Rwandan Owners
US LLCs are created under state law. A single person can own all membership interests, and that person can generally live in Rwanda. Most state formation filings do not demand US citizenship, US residency or a Social Security number. Ownership alone does not grant a US visa or work authorization. If you plan to work physically in America, immigration must be analyzed separately. The US State Department’s Rwanda reciprocity schedule currently lists no E-1 or E-2 treaty for Rwandan nationals.
| Term | What it means | Why it matters from Rwanda |
|---|---|---|
| Articles or certificate of organization | The state filing that legally creates the LLC. | Keep the approved copy for bank and tax use. |
| Registered agent | An in-state person or company that receives official and legal notices. | Your Kigali address cannot replace the required state agent. |
| Operating agreement | Private rules for owners, management and distributions. | Useful even with one owner and often requested by banks. |
| EIN | Federal Employer Identification Number issued by the IRS. | Applying directly is free; most banks request it. |
| Disregarded entity | Default US federal income tax classification of a one-member LLC. | Income tax generally follows the owner, while special LLC information reporting can still apply. |
| Foreign qualification | Registration to do business in a US state other than the formation state. | May be needed if the company has real US operations elsewhere. |
If a Rwandan company rather than an individual will own the LLC, prepare that company’s registration, directors, shareholders and ultimate-owner information. This can alter US tax forms, Rwanda accounting and banking diligence. A US LLC and a Rwandan company remain separate legal entities even if one owns the other.
Choose a State Based on Real Operations and Cost
If the LLC will have a US warehouse, employees, office or regular physical operations, examine that state first. Filing in a different low-fee state may add a second registration and tax calendar. For a genuinely remote services business run from Rwanda with no US place of business, founders often compare New Mexico, Wyoming and Delaware.
| State | Formation filing | Routine state maintenance | Reason to choose it |
|---|---|---|---|
| New Mexico | $50 | No routine LLC annual report under current state rules. | Low stated government costs for a remote small business. |
| Wyoming | $100, plus any online payment charge. | Annual report and license tax of at least $60; more if Wyoming assets require it. | Founder comfortable with an annual report and its rules. |
| Delaware | $110 | $400 annual LLC tax due June 1; no annual Delaware LLC franchise-tax report. | Investors or counsel specifically require Delaware. |
See the Wyoming filing form, Wyoming annual guidance, New Mexico business portal, and Delaware’s fee schedule and annual tax page. Check the live state portal before filing. Service, agent, payment processing and any other-state fees are separate.
Column chart: one-time state filing fee
Government filing charges in USD, cited above. Excludes provider and agent fees.
Horizontal bar chart: minimum routine state charge per year
State charges only; registered agent and any other-state duties are additional.
New Mexico’s simple maintenance can appeal to a solo founder. Wyoming has an explicit annual report with a modest minimum charge. Delaware is useful when there is an investor, lawyer or commercial reason, not because every internet business needs it. Public owner-name differences between states do not make a company invisible to banks or authorities; read our LLC privacy guide for that distinction.
The Real First-Year and Ongoing Costs
Start with the government fee, then add the registered agent and any formation service. Check whether an advertised package includes an agent for a limited period and what it costs on renewal. Optional EIN help, operating agreement packages, mail service and tax consultations can change the checkout total. The IRS EIN is free when you apply directly. Keep a separate budget for US and Rwanda tax work.
| Item | When paid | Budget treatment | Required? |
|---|---|---|---|
| State formation filing | Once | $50 NM, $100 WY, $110 DE in our comparison. | Yes. |
| Registered agent | Usually annually | Request the first-year and renewal price in writing. | Yes. |
| Formation-service package | At checkout | Price varies; review the live Bizee total. | No; direct filing is allowed. |
| EIN | Once | $0 if requested directly from the IRS. | Commonly needed for banking and filings. |
| State annual fee | After formation | Depends on state and possible operations elsewhere. | Where applicable. |
| US tax preparation | As required | Ask whether the quote includes Form 5472 and any owner return. | Facts determine forms; specialist help is often sensible. |
| Rwanda tax and payment setup | At launch and yearly | Include RRA, bank and foreign-currency advice where relevant. | Depends on activity. |
Donut chart: illustrative $200 Wyoming setup budget
Illustration only, not a Bizee or registered-agent price quote. Taxes and professional fees excluded.
Line chart: three-year minimum state-only cost
Model adds one minimum state charge in each year after formation. Delaware’s actual tax assessment depends on the year formed. Other costs excluded.
Compare the live checkout before paying.
Review Bizee’s package, government filing fee, registered-agent term and optional services.
See Bizee LLC options →What to Prepare Before You File
Decide whether you or an existing Rwandan company will own the LLC. That determines the operating agreement, bank ownership chain and tax analysis. Write down the real work location, customer countries, expected receipts and how you will pay suppliers. If you plan to sell physical goods, include inventory and shipping locations. A short plan will expose issues before they become expensive changes to state records.
- Current passport and residential-address evidence for each owner or manager.
- Two or three compliant LLC names, checked with the chosen state.
- Ownership percentages and the choice of member management or manager management.
- A truthful description of products, services, customers and payment flows.
- The registered agent’s legal name and physical in-state address.
- Reliable email and phone contact from Rwanda.
- A plan for RRA registration, invoices, receipts and foreign-currency records.
State name availability does not mean a trademark is available. Search relevant brands, web domains and marketplaces separately. Use the same legal spelling on the state filing, IRS Form SS-4, operating agreement and bank application. Inconsistent ownership or address data can delay a financial provider’s review.
The registered agent is not your US office
An agent accepts lawsuits and official notices at a physical address in the formation state during business hours. Its address can satisfy that statutory requirement without becoming your operating address. If you work in Kigali, tell banks and customers where you actually work. Ask the agent how it sends notices, what it scans, whether it forwards ordinary mail and what it charges after any introductory year.
Step by Step: Forming the US LLC Through Bizee
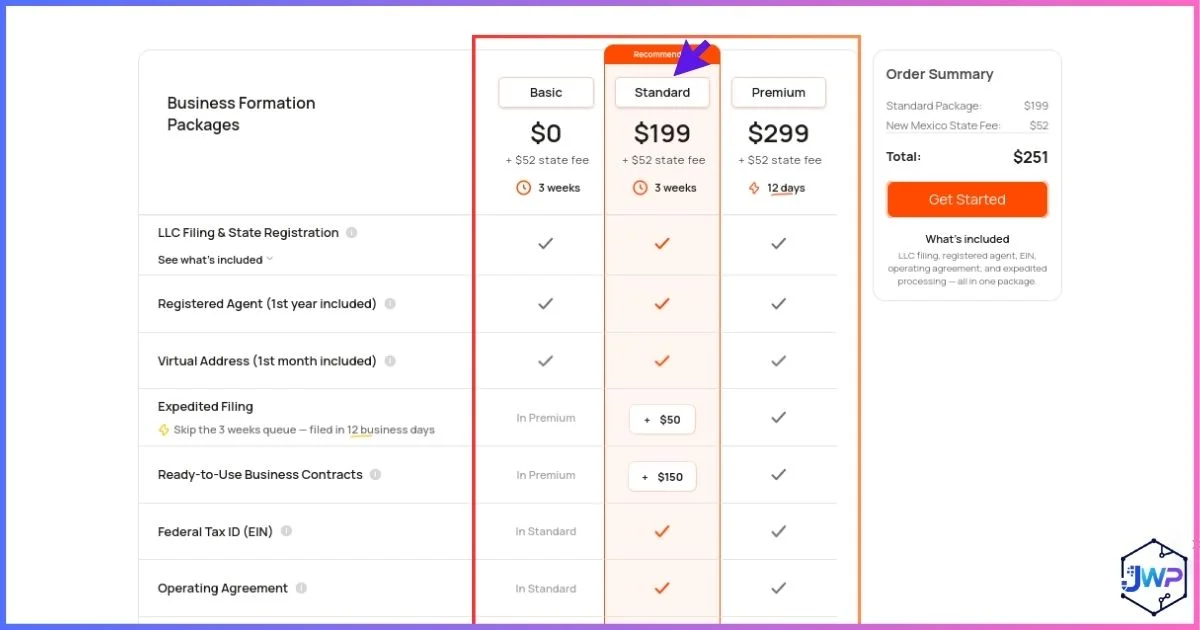
The supplied Bizee screenshots show a 14-step order flow. They are illustrations, not a price or availability guarantee. Screen wording, offers and government charges can change. Review every term in the live checkout. Filing directly with the state and hiring an agent separately is also possible.
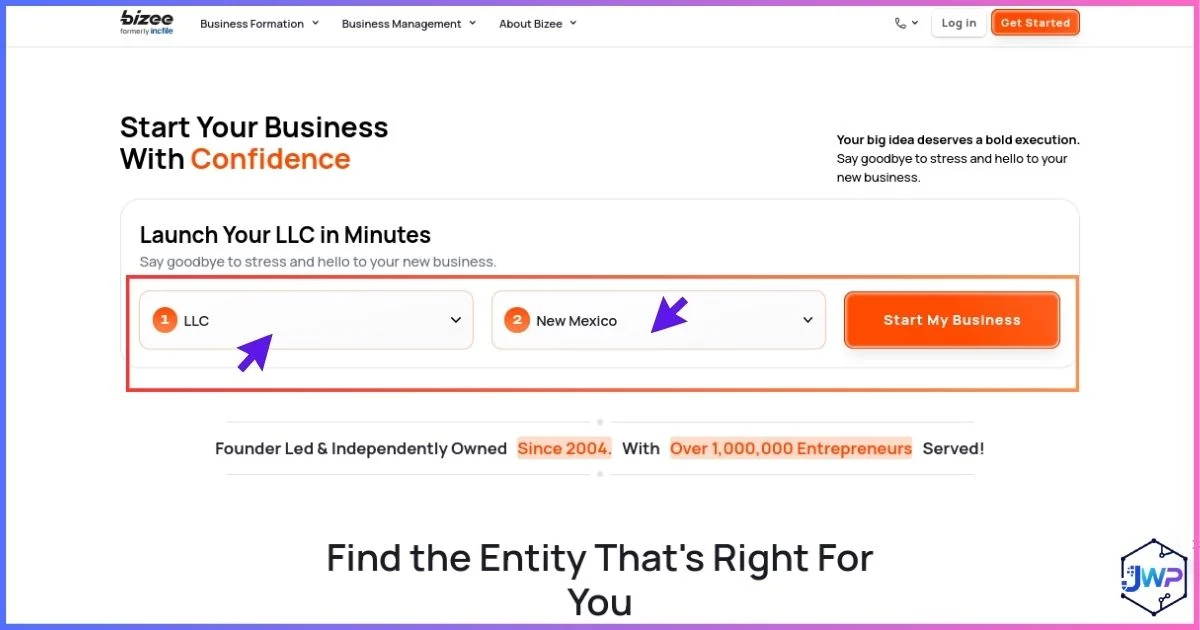
Choose an LLC and formation state
Select LLC rather than a corporation, then choose the state based on real US operations, annual state charges and any investor requirements. A Wyoming filing will not remove a second state’s rules if the business actually operates there.
Compare packages
Read the complete package table. Identify the government filing fee, provider fee, registered-agent period and renewal price. Keep optional add-ons separate from what is legally needed to create the entity.
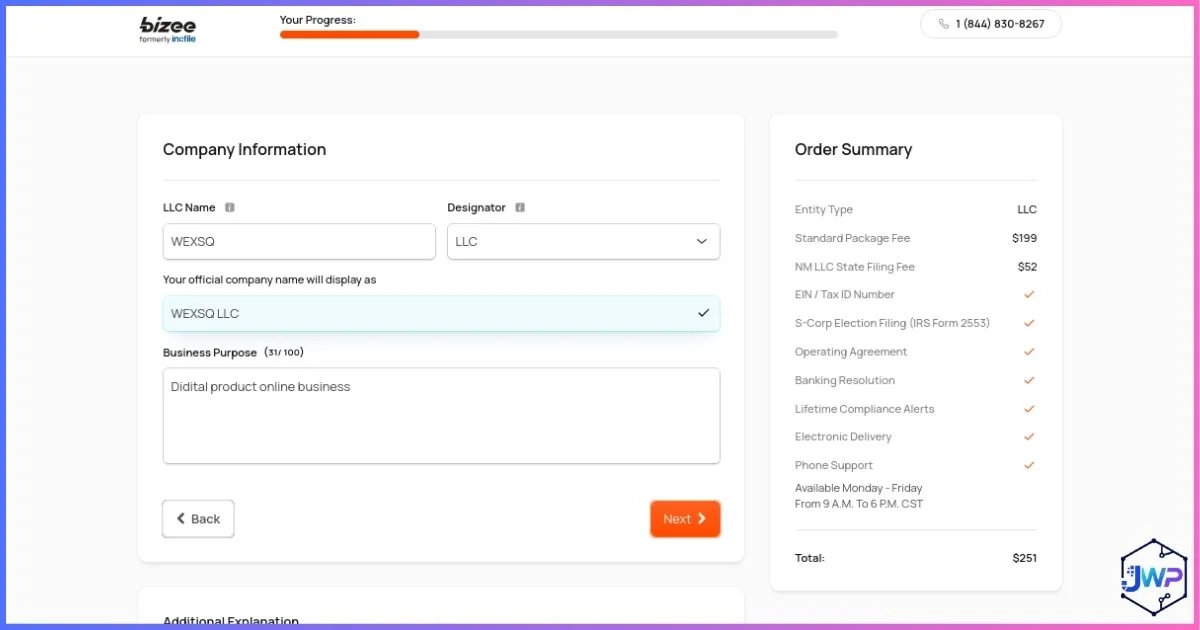
Enter company information
Use the exact LLC name checked with the state and a clear description of what the business sells. The bank may later compare this description with your website, contracts and invoices.
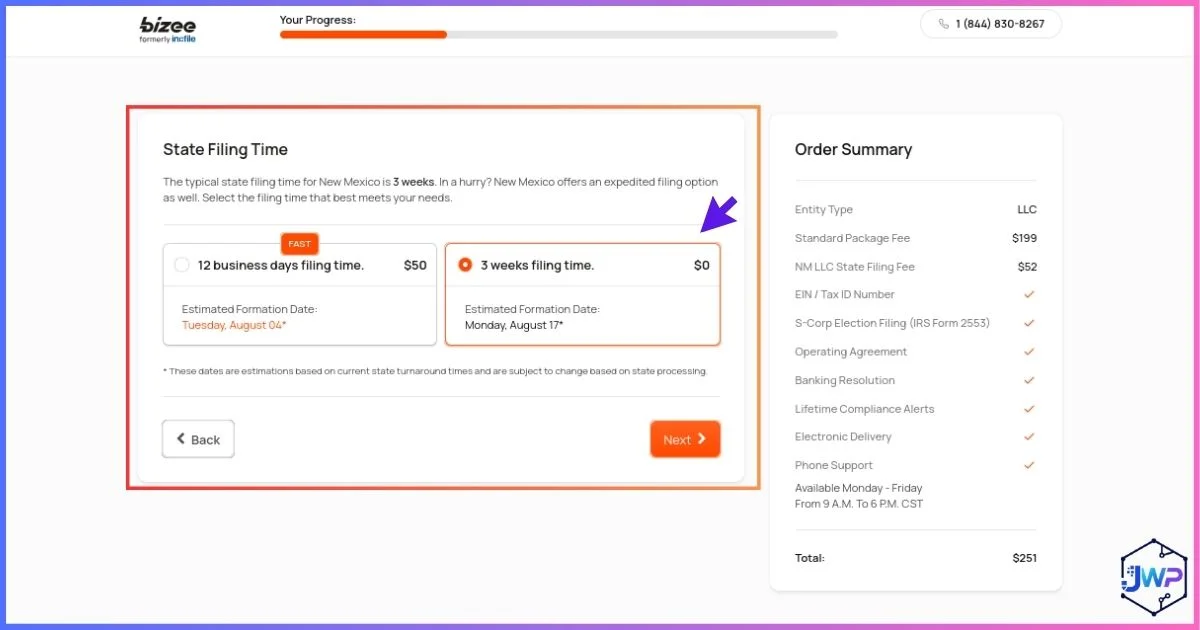
Choose state filing speed
Use standard processing unless a genuine commercial deadline justifies an expedite charge. Faster state approval does not speed the IRS EIN or guarantee a bank account.
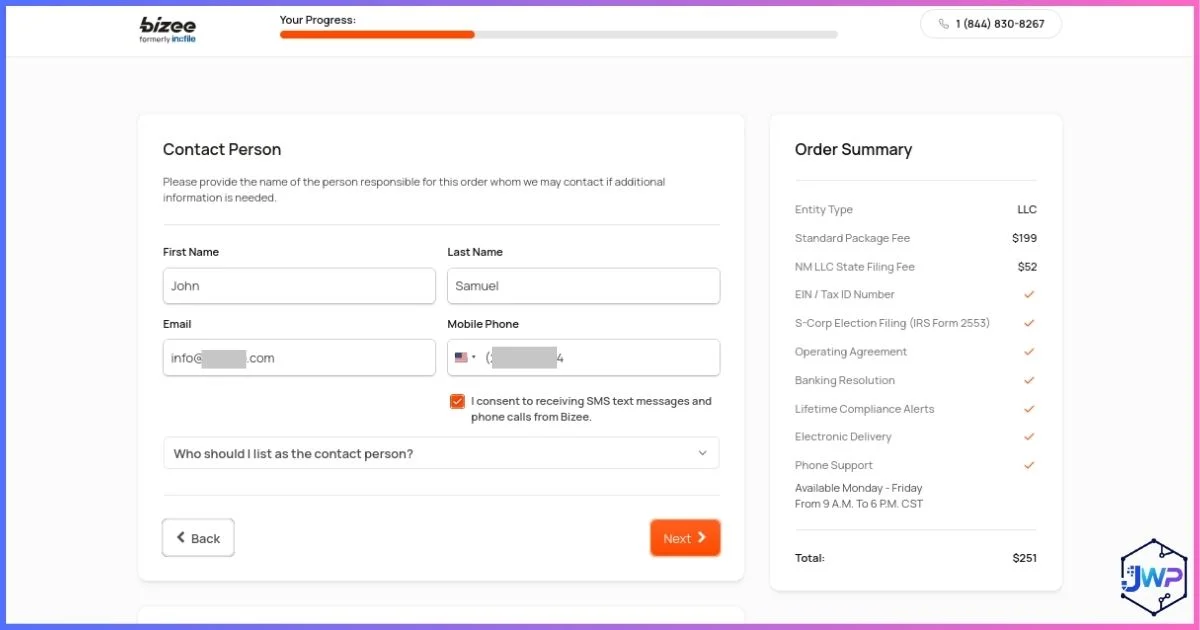
Provide a contact person
Use an email and telephone number that work reliably from Rwanda. Formation services may need a quick answer if a name is unavailable or a state filing needs correction.
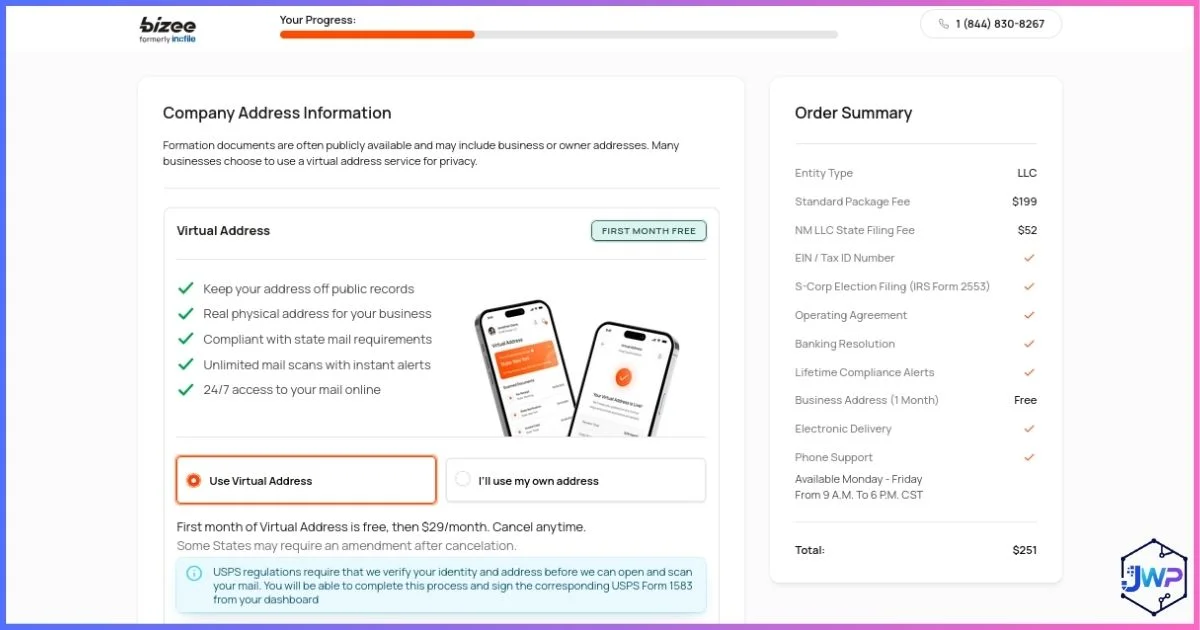
Give accurate address details
Distinguish your real Rwandan operating address, mailing address and the registered-agent address. An agent office is not proof that your business has employees or premises in the United States.
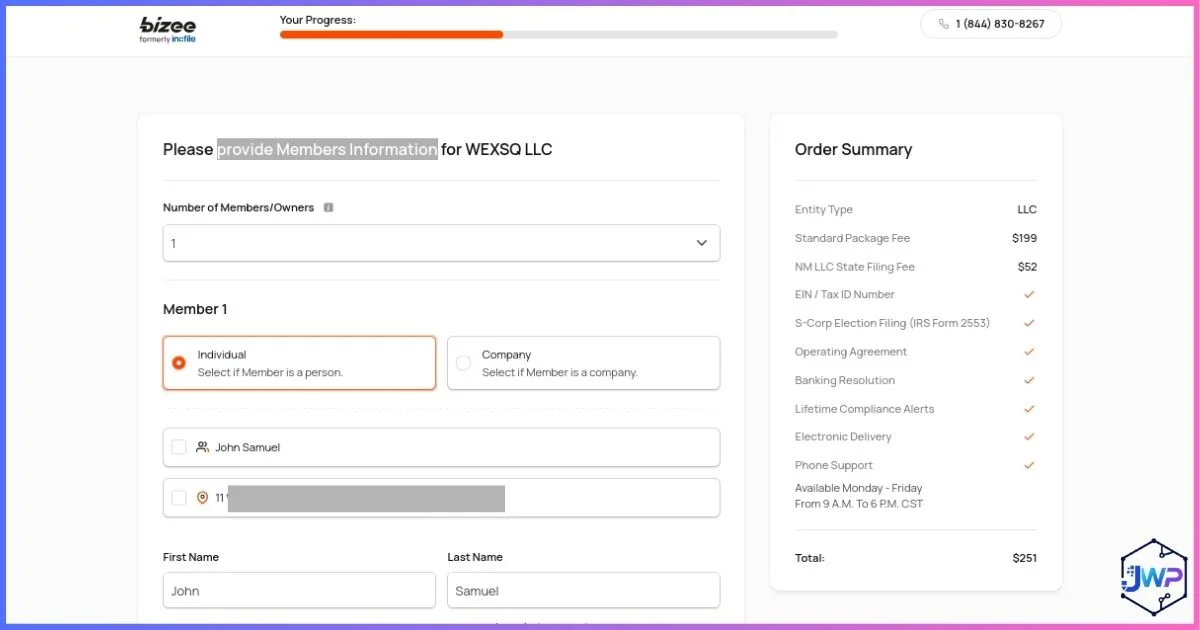
List members and managers
Enter the actual owner and ownership percentage. If a Rwandan company owns the LLC, document that company and its ultimate owners rather than using a director as a stand-in personal owner.
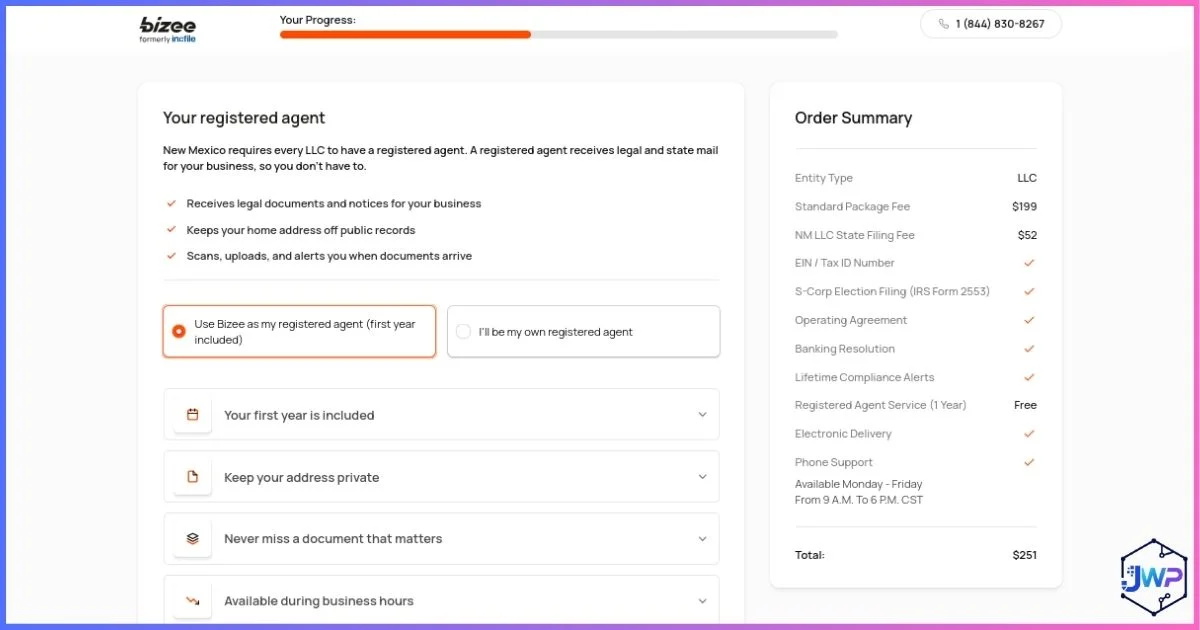
Confirm the registered agent
Choose Bizee’s agent service or another qualified in-state agent. Read the first-year term and renewal policy, and make sure you know where official notices will be sent.
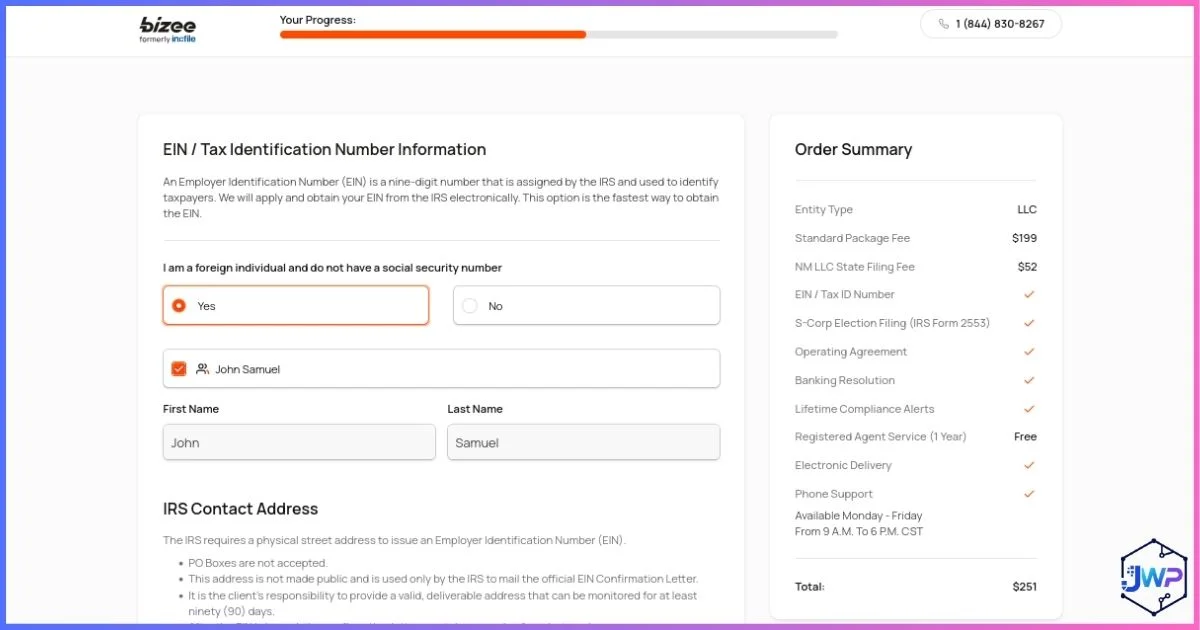
Decide on EIN assistance
The IRS issues an EIN for free. A provider may charge for preparing or transmitting Form SS-4. If you pay for help, confirm the responsible party and tax classification are correct.
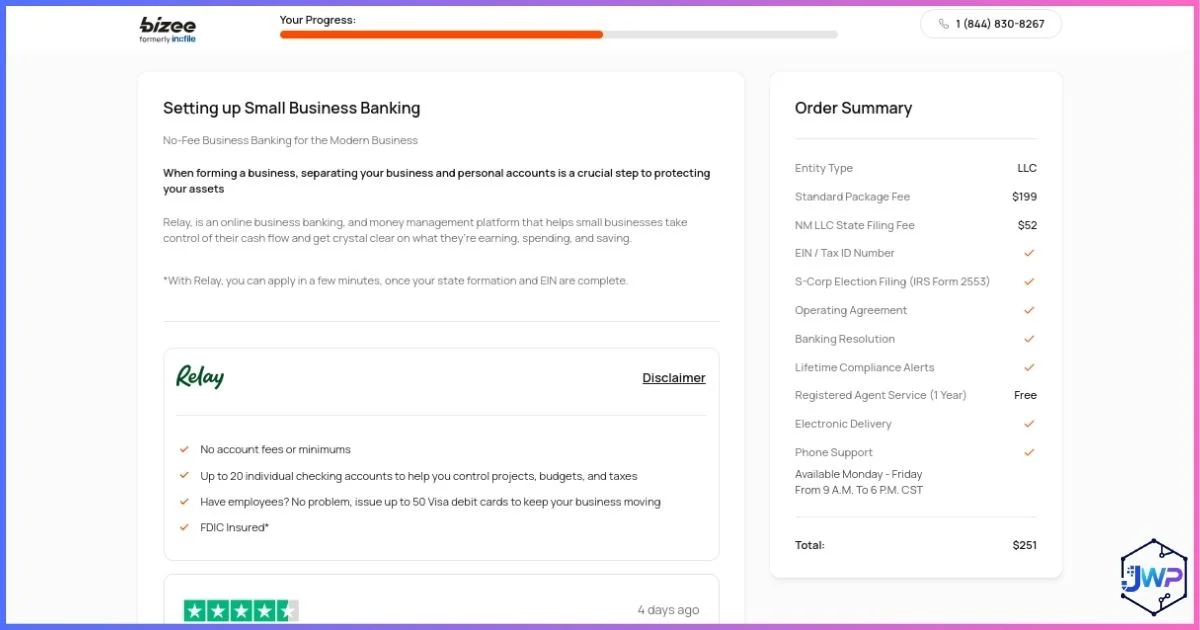
Consider banking later
A promoted account is only an offer to apply. Verify that the provider accepts beneficial owners resident in Rwanda and supports your activity before treating it as your launch plan.
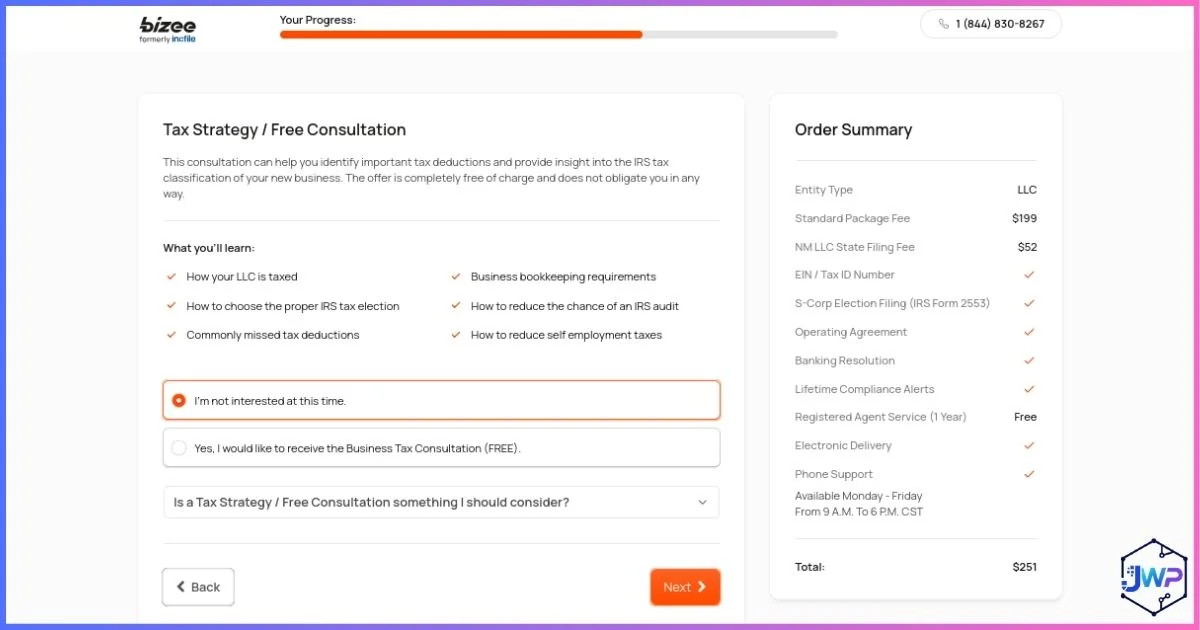
Assess tax strategy offers
Ask whether any consultation covers nonresident owners, foreign-owned disregarded entities, Form 5472, Rwandan tax residence and the absence of a US–Rwanda treaty. A generic call may not answer those questions.
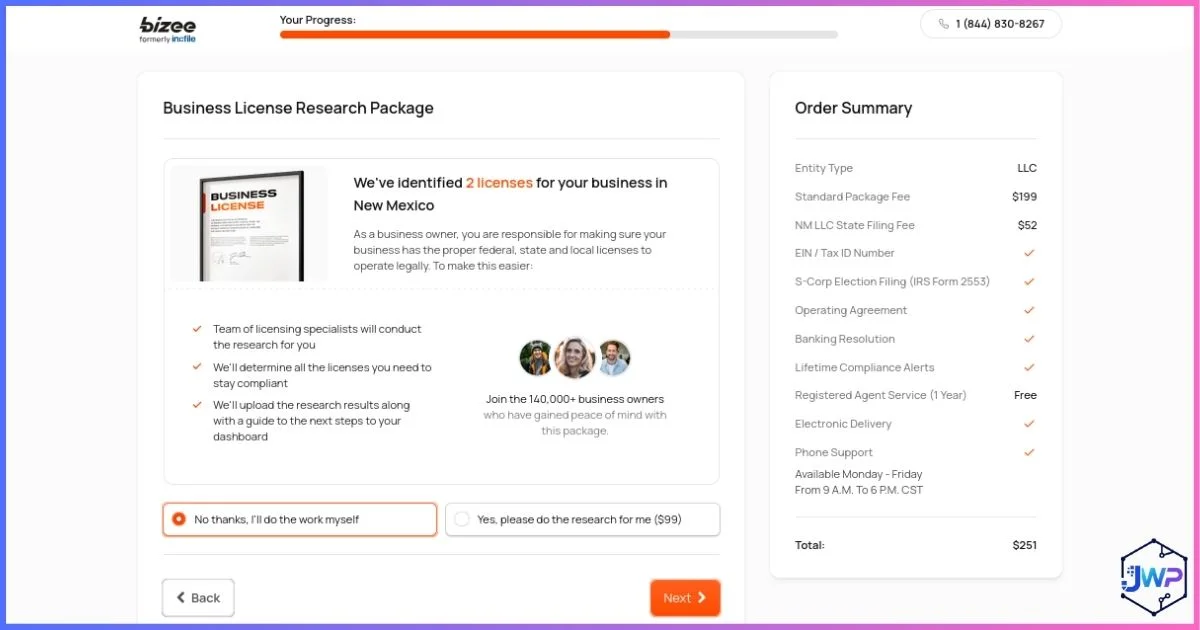
Assess license research
The LLC certificate is not a universal operating license. US sales tax, regulated activities and Rwandan local obligations may each need separate analysis. Buy research only if its scope fits your business.
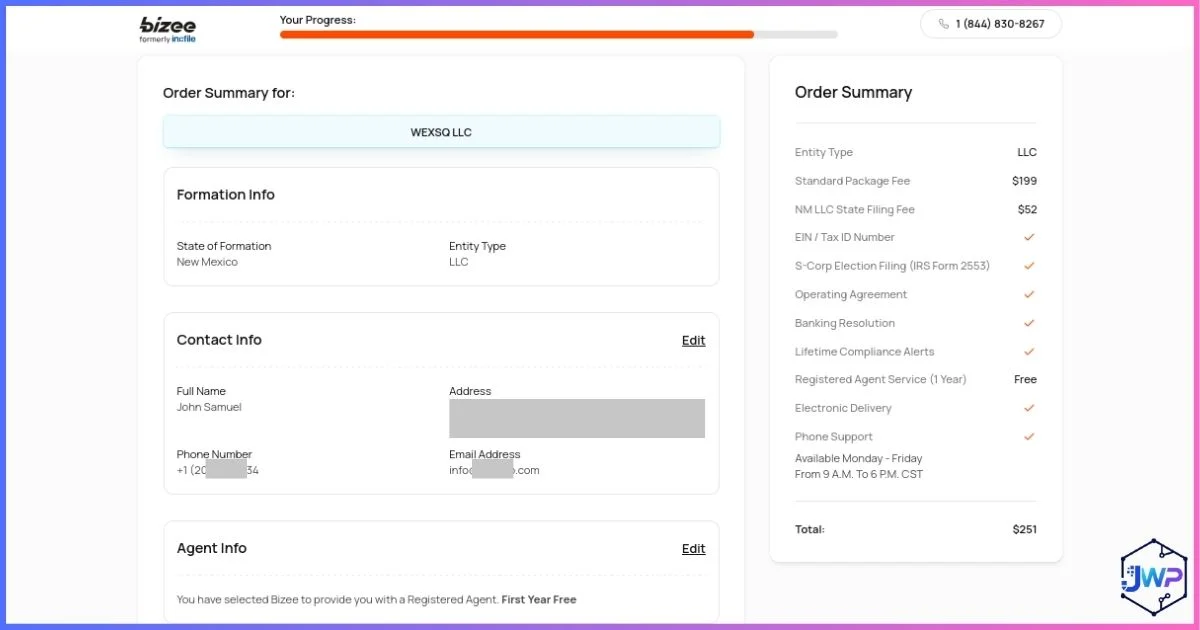
Audit the order summary
Check the company name, state, members, agent term, filing speed, optional services, subscriptions and total due. Save the summary and correct errors before payment.
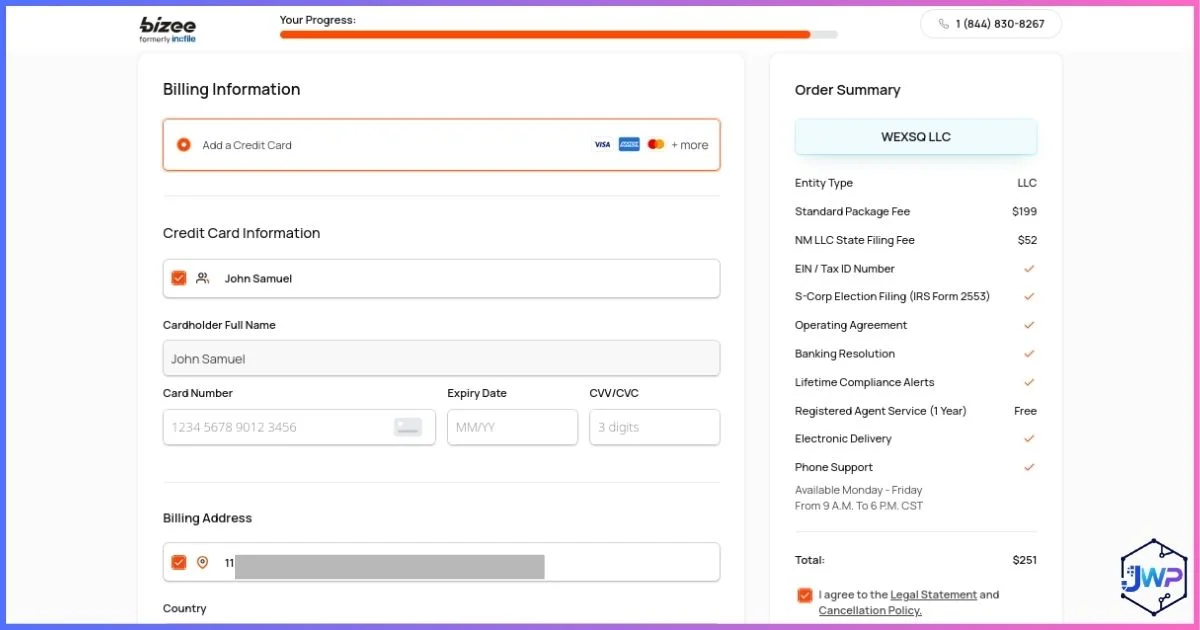
Pay and save approved documents
Keep the receipt, then wait for state acceptance. After approval, download the stamped state document, agent details and operating agreement. Payment to a service does not itself create the LLC.
How to Obtain an EIN from Rwanda
The EIN is the LLC’s federal tax identification number. It is commonly requested for banking and required for several filings. The IRS does not charge to issue one. Apply after the state approves the LLC so the legal name and formation date match the state document. International applicants who cannot use the online assistant can follow the IRS’s phone, fax or mail procedures. Check the live IRS EIN page for current eligibility, contacts and processing information.
- Complete Form SS-4 with the exact LLC name, responsible party, address and reason for applying.
- Use the actual individual who controls the entity as responsible party. A registered agent or formation-company employee should not be inserted merely to show a US person.
- If the responsible party does not have and is not eligible for an SSN or ITIN, follow the Form SS-4 instructions for line 7b. Do not invent a number.
- For a foreign-owned US disregarded entity requesting an EIN to file Form 5472, use the special line 9a description specified by the IRS.
- Save the completed application and IRS confirmation. If processing takes longer than the IRS’s stated interval, inquire about the existing application rather than sending repeated applications.
An EIN service can charge for preparing the form, but it does not own or sell the government number. The IRS number remains free. If the LLC has two members, an elected corporate classification or a company owner, its entries and eventual tax filings may differ from the solo-individual example. Resolve classification before sending the form.
Banking, USD Receipts and Payment Platforms
State approval and an EIN make a banking application possible, but account opening is the bank’s separate decision. The provider can review Rwandan residence, identity, ownership, business model, countries of customers, expected payment amounts and source of funds. Some US fintechs accept foreign-owned LLCs, while others limit residence countries or industries. Policies change, so check eligibility before selecting an LLC simply to use a particular provider.
| Bank or platform request | What to supply | Avoid this mistake |
|---|---|---|
| Entity existence | Approved articles or certificate and EIN confirmation. | Submitting a Bizee order receipt as if it were state approval. |
| Ownership and authority | Signed operating agreement and full parent-company chain if relevant. | Listing a nominee instead of the real owner. |
| Identity and location | Valid passport and genuine residential and operating addresses. | Calling the registered-agent office your workplace. |
| Business evidence | Website, contracts, sample invoices and explanation of expected flows. | Using contradictory activity descriptions. |
| Source of funds | Records for initial capital and later owner transfers. | Mixing personal and company deposits without explanations. |
Maintain an alternative plan if your first provider declines. An account rejection does not necessarily mean the LLC filing failed. Ask what documents can resolve a factual issue, and apply elsewhere only if that provider serves your residence and activity. Never use someone else’s identity or a false address to bypass screening.
Where funds ultimately move matters. Keep a record when US clients pay the LLC, when the LLC pays a Rwandan supplier, and when you draw profits personally. Rwanda’s foreign-exchange regulation addresses foreign-currency accounts and capital-account transactions, and its foreign-currency directive explains permitted handling of receipts in covered situations. Ask an authorized Rwandan bank how the current rules apply to your specific flows. Our Wise and Payoneer guides may help you compare payment tools, but their Rwanda eligibility must be checked live.
US Taxes and Information Returns for Rwandan Owners
US tax does not depend on the LLC certificate alone. It depends on owner identity, tax classification, income type and where business activity occurs. A one-member LLC usually defaults to disregarded status for federal income tax. A two-member LLC normally defaults to partnership status. An election to corporate treatment changes the tax return and possibly the owner-level results. If you are a US citizen or US tax resident who happens to live in Rwanda, worldwide-income rules can apply to you; our US citizen LLC guide is a better starting point.
Services performed in Rwanda
The IRS generally sources personal-service income where work is physically performed. A designer in Kigali who completes a project there for a New York customer usually has foreign-source service income for US purposes even if the contract uses a US LLC and the money arrives in a US account. A week of billable work performed in New York may require an allocation. The source rule for services does not automatically cover royalties, digital licenses, advertising income, physical goods or US real estate. See the IRS services sourcing guidance.
A US office, employee, warehouse, or dependent agent can change the outcome. US-source income connected to a US trade or business may be taxed differently from passive US-source income. State income tax, sales tax, payroll and registrations can arise even when federal income tax is limited. Consult a US cross-border preparer for mixed activities and do not apply a “zero US tax” conclusion to the entire company merely because its owner lives in Rwanda.
| Business example | Main tax question | Possible result to review |
|---|---|---|
| Rwandan consultant works entirely in Kigali for US clients. | Where were services performed, and is there any US business presence? | Foreign-source service income may be outside US federal income tax for a nonresident owner; Rwandan tax still matters. |
| Founder performs paid work during a US trip. | How much of the fee relates to work physically in the US? | Potential US-source income, withholding and return filing. |
| Seller stores stock in a US warehouse. | Where is inventory sold and where are activities carried out? | Potential US trade, state registration and sales-tax nexus. |
| Creator licenses IP used in the US. | Is the payment a royalty, service fee or something else? | US-source royalty withholding can apply without a Rwanda treaty rate. |
Form 5472: the filing many solo founders miss
For a wholly foreign-owned US disregarded LLC, the IRS treats the entity as separate for a limited information-reporting rule. It generally files Form 5472 attached to a pro forma Form 1120 when it has reportable transactions with a related party. Contributions to form or fund the LLC, owner distributions, loans and other transfers can be reportable. A company can therefore have no customers and still need the form. The IRS instructions also state an exception when there are no reportable transactions at all, so do not make an unconditional yearly filing claim.
The initial failure-to-file penalty is $25,000. A substantially incomplete form can be treated as a failure, and continued noncompliance after notice can produce more penalties. Foreign-owned disregarded entities have a specific filing address or fax procedure and extension instructions. Hire someone who actually handles these forms if you have owner advances, intercompany charges or a Rwandan parent company. Save the documentation behind every related-party amount.
No US–Rwanda Income Tax Treaty: What That Means
Rwanda is absent from the IRS’s list of countries with a US income tax treaty in force. A Rwandan tax resident cannot claim a US–Rwanda treaty rate on Form W-8BEN or W-8BEN-E. Some US-source fixed or determinable annual or periodical income paid to a foreign beneficial owner, such as certain dividends or royalties, can be subject to the standard 30% gross withholding unless a separate Internal Revenue Code exception applies. See the IRS treaty list and its FDAP income guidance.
This does not mean 30% of every US customer invoice must be withheld. A service performed entirely in Rwanda has a different source rule. An LLC distribution is not automatically a corporate dividend, especially when the LLC is disregarded. Interest may have domestic-law exemptions. Identify the exact beneficial owner and payment category before giving a withholding form to a payer. A W-9 is not automatically correct simply because an LLC was formed in a US state.
Pie chart: illustrative $100 US-source royalty subject to 30% withholding
Example assumes the payment is a US-source royalty to a nonresident beneficial owner and no domestic-law exemption applies. It is not a tax calculation for all LLC receipts.
Rwanda may still tax the owner’s income. Double taxation relief, if any, must be examined under applicable Rwandan domestic rules and supported with withholding records. Do not assume a US payer’s withholding certificate alone proves the total tax due in either country.
Rwanda-Side Tax, Registration and Foreign-Currency Questions
The Rwanda Revenue Authority says a resident individual is liable for income tax on domestic- and foreign-source income. It also says a nonresident is generally liable on Rwanda-source income. Therefore, the foreign address of a customer or the US registration of an LLC does not by itself remove an individual owner’s Rwandan tax duty. The exact treatment depends on whether the income is business, employment or investment income; who owns the LLC; where activities occur; and how Rwanda classifies the foreign entity. Read the RRA personal income tax guidance and obtain advice for your structure.
If a Rwandan company owns the LLC, its own corporate reporting and related-party records need attention. RRA currently lists a 28% standard corporate income tax rate from 2024, but that is not a blanket rate on every US LLC invoice. An individual owner, local parent company, and a foreign entity operating in Rwanda can be treated differently. Do not use US disregarded classification as proof that RRA ignores the business or that Rwanda’s corporate rate applies automatically.
Registration and annual declarations
RRA states that taxable activity should be registered for income tax and that Rwandan business registration through the Rwanda Development Board normally triggers income-tax registration. Its income tax declaration page gives a general annual deadline of March 31 following the tax period, unless a different legal rule applies. Confirm whether your work from Rwanda requires local business registration and which person or entity must declare the income. The US certificate is not a Rwandan operating license.
RRA’s VAT registration guidance states a threshold of more than RWF 20 million in the previous fiscal year or RWF 5 million in the preceding quarter for taxable activity, subject to the law’s details. Its 2025 VAT guidance lists exported goods and services as zero-rated, but whether a specific digital service qualifies depends on its facts and documentation. A US customer address alone is not sufficient proof of zero rating. Check invoices, place of supply and RRA requirements before treating all export receipts the same way.
Foreign-currency accounts and outward payments
The National Bank of Rwanda’s foreign-exchange regulation covers current and capital transactions. Its directive describes conditions for certain non-licensed persons receiving foreign currency and options such as a dedicated foreign-currency account, sale to a licensed intermediary or settlement of external obligations through authorized institutions. Those documents do not mean every founder has the same account privileges or that every payment abroad is unrestricted. Ask your Rwandan bank which documents it needs to fund the LLC, receive customer proceeds or bring owner income home.
- Can I or my Rwandan company pay the US state, agent and initial LLC capital from this account?
- What purpose codes or supporting contracts are required for outward and inward transfers?
- Where should export revenue be received, and how may it be used or converted?
- How should an LLC distribution, loan repayment, salary or supplier payment be documented?
- What records will RRA need to recognize any foreign tax paid?
Keep foreign-currency conversion records and receipts. If the Rwandan franc value of a transaction is needed for local accounts, agree with your adviser on a consistent, documented conversion method. A single business can have US dollar records for the LLC and RWF reporting needs in Rwanda; reconcile both rather than estimating from bank balances.
BOI Reporting, Public Privacy and Ownership Records
As of September 2026, FinCEN says entities created in the United States are exempt from federal Corporate Transparency Act beneficial ownership information (BOI) reporting under its August 2026 final rule. This includes a domestic US LLC owned by a Rwandan person. A Rwandan company registering to do business in a US state is a foreign entity for this purpose and may need separate BOI analysis. Review FinCEN’s current guidance at the time of action because these rules have changed.
BOI exemption is not anonymity. The registered agent, state, IRS, banks and payment processors may require real owner details under their own rules. Keep the signed operating agreement, beneficial-owner chain, passport records and change history in a secure company folder. Update relevant state filings, bank records and IRS responsible-party information when control changes.
A First-Year and Annual Compliance Calendar
Put dates into a calendar as soon as the state accepts the LLC. Tax deadlines depend on classification, owner status and tax year, so ask a US preparer for the specific federal schedule. Separately identify the RRA obligations of the individual, any local company and any locally conducted activity. Registered-agent invoices and state notices should go to an email that is checked regularly.
| When | Action | Why it matters |
|---|---|---|
| At formation | Save state approval, agent details, operating agreement and owner information. | Needed for banking and later filing. |
| Before taking revenue | Confirm Rwanda business and tax registration, banking route and VAT status. | US formation does not complete local compliance. |
| Monthly | Reconcile sales, expenses, owner capital, distributions and related-party transfers. | Supports US Form 5472 and RRA records. |
| By applicable US return deadline | Determine Form 5472/pro forma 1120 and any owner, partnership or corporate returns. | Forms vary by entity classification and transactions. |
| March 31 after a Rwanda tax period, where applicable | File the relevant RRA annual income-tax declaration. | RRA states this general deadline, subject to legal exceptions. |
| Wyoming anniversary month, if formed there | Submit annual report and license tax. | Maintains state good standing. |
| June 1 for a Delaware LLC | Pay Delaware’s annual $400 tax. | No Delaware LLC annual tax report is required, but payment is. |
| Every year | Renew agent; revisit banking, VAT, US state nexus and foreign-currency rules. | Business facts and official policies can change. |
If the business ends, formally dissolve the LLC with its state, close accounts and settle final filings and taxes. Simply ceasing to sell does not necessarily end state fees or registered-agent costs. Ask how liquidation proceeds should be recorded for Rwanda tax and bank purposes.
File Directly or Use a Formation Service?
Direct state filing can be economical for a simple one-owner LLC if you are comfortable with state forms and have separately hired an agent. A formation service can organize submission and document delivery. It cannot guarantee a bank account, tax exemption, EIN processing time or Rwandan compliance. Compare the provider’s current deliverables with what you would otherwise do yourself.
Direct filing may fit if
- The ownership is simple and fully documented.
- You understand the chosen state’s filing questions.
- You can appoint and monitor an agent.
- You will maintain your own records and deadlines.
Get specialist advice if
- A Rwandan company owns the LLC.
- You hold US inventory or hire US staff.
- Royalties, investors or multiple owners are involved.
- Rwanda classification or foreign-currency handling is uncertain.
Formation assistance and cross-border tax advice solve different tasks. A lower-priced package can be enough for a routine filing, while a tax specialist may still be necessary for the LLC’s first year. Ask any adviser exactly which forms, jurisdictions and follow-up questions their fee covers.
Use Cases and Mistakes to Avoid
- Forming before checking banking: a valid LLC may still be declined by a preferred provider. Check its Rwanda eligibility and activity rules first.
- Calling all income tax free: RRA generally taxes resident individuals on domestic and foreign sources. US tax depends on income type and activity.
- Claiming a nonexistent treaty rate: the IRS does not list a US–Rwanda income tax treaty.
- Ignoring owner transfers: initial funding or distributions may make Form 5472 relevant even before customer sales.
- Using the agent’s address as a false operating location: statutory contact is different from where the business actually works.
- Assuming exported services automatically qualify for zero-rated VAT: document and test the specific transaction against RRA rules.
- Choosing Delaware by default: its $400 annual tax should be justified by an actual business reason.
- Mixing company and personal spending: it weakens accounting and makes ownership transfers harder to explain.
For payout planning, our guide to paying yourself from an LLC explains US classifications. Ask a Rwandan adviser how the chosen payment is treated locally.
Compare the live formation order.
Check every government charge, package feature, agent renewal and optional add-on against your actual needs.
Review Bizee LLC packages →Rwanda-to-US LLC Master Checklist
- Describe the business, customer locations, owner residence and where work, staff and stock will be.
- Confirm a real commercial reason for a US entity and check provider eligibility for Rwanda.
- Discuss RRA tax, registration, VAT and currency handling with qualified local advisers or a bank.
- Compare state filing and recurring costs, including any state with actual US activity.
- Check the company name and choose a registered agent.
- File directly or review the complete Bizee order before paying.
- Save state approval and sign an accurate operating agreement.
- Apply directly to the IRS for the free EIN or knowingly buy preparation help.
- Apply for banking using genuine identity and operating-address documents.
- Record customer receipts, expenses, owner funding and distributions from day one.
- Have a US preparer identify federal and state returns and a Rwanda adviser identify local declarations.
- Calendar annual state, agent, IRS and RRA obligations.
Frequently Asked Questions
Can a Rwandan citizen own 100% of a US LLC?
Must I travel to the United States or have a visa?
Does forming an LLC qualify me for an E-2 investor visa?
Do I need an SSN or ITIN to obtain the LLC’s EIN?
Which state should I choose if all work stays in Rwanda?
Is New Mexico really free every year?
Will a US LLC eliminate Rwandan income tax?
Are fees from US customers automatically subject to 30% US withholding?
Does Rwanda have a US income tax treaty?
Must my foreign-owned LLC file Form 5472 if it has no profit?
Can I open a US business bank account from Kigali?
Does a US LLC make exported services zero-rated for Rwanda VAT?
Do I have to file a federal BOI report for a new US LLC?
What if I stop trading?
Final Decision Guide
A US LLC can be a useful legal and contracting base for a Rwanda-based founder when customers, platforms or partners genuinely need one. The formation sequence is manageable: choose a suitable state, appoint an agent, file accurate documents, obtain the free EIN and apply for banking with truthful owner and business information. The ongoing work is keeping clear records and meeting the requirements of both countries.
Before paying for formation, settle three questions: whether your preferred financial provider supports Rwandan-resident owners, how RRA will tax the activity and how money will move through authorized accounts. Then budget annual agent, state and professional costs. If a Rwandan company owns the LLC, or the business has US employees, inventory, royalties or multiple owners, seek tailored advice before filing.
See the current formation terms.
Review Bizee’s live state fee, package contents, registered-agent renewal and optional services before ordering.
Explore Bizee LLC formation →Sources & Research Notes
Updated September 26, 2026. State charges, IRS rules, RRA guidance, foreign-exchange procedures and provider policies can change. The state-cost charts use published government figures. The budget donut and withholding pie are labeled illustrations, not surveys or provider quotes.
- Wyoming Secretary of State: LLC filing form and annual report guidance.
- New Mexico Secretary of State: business portal.
- Delaware Division of Corporations: filing fee schedule and annual LLC tax instructions.
- IRS: EIN for international applicants and Form SS-4 instructions.
- IRS: Form 5472 filing requirements and penalties.
- IRS: source of personal-service income, FDAP income, and income tax treaty list.
- RRA: personal income tax and foreign-source income, corporate income tax, and annual declarations.
- RRA: VAT registration and 2025 VAT guidance.
- National Bank of Rwanda: foreign exchange regulation and foreign-currency directive.
- FinCEN: BOI reporting and August 2026 final rule; US State Department: Rwanda E-visa reciprocity.