How to Form a US LLC from Uganda
Yes — Ugandan citizens can legally form a US LLC without a visa, without an SSN, and without ever boarding a plane. This guide walks you through state selection, real costs, the exact Northwest Registered Agent ordering flow (7 screenshots), EIN acquisition for foreign founders, USD banking from Kampala or the diaspora, and the IRS filings most Ugandan owners never see coming. Uganda has no US income tax treaty, the Shilling (UGX) floats freely, and PayPal accounts in Uganda famously cannot receive money — all of which shape your formation and payment strategy in ways that make a US LLC almost essential for serious online business.
Quick Answer: How to Form a US LLC from Uganda
Ugandan citizens can fully own a US LLC with no US visa, no SSN and no physical presence. The process has six moving parts: (1) pick a formation state — Wyoming is the default recommendation for non-residents, Delaware if you plan to raise investment, New Mexico for the lowest ongoing cost; (2) hire a registered agent in that state (required by law); (3) file the Articles of Organization through a formation service like Northwest Registered Agent ($39 + state fee) or directly with the state; (4) obtain an EIN from the IRS using Form SS-4 by fax or mail — no SSN/ITIN needed for foreign owners; (5) open a US business bank account remotely (Mercury, Relay, Wise Business); and (6) stay compliant: state annual reports, registered-agent renewal, and — critically — the annual Form 5472 + pro-forma Form 1120 information return that every foreign-owned single-member LLC must file even when it owes $0 of US tax.
Uganda-specific note: Uganda has no bilateral income tax treaty with the United States, so US-source FDAP income (dividends, royalties, certain rents) paid to you as the disregarded owner is subject to the standard 30% withholding — there is no treaty rate to claim on W-8BEN. The Ugandan Shilling (UGX) floats freely under a liberal Bank of Uganda framework, and inbound remittances of roughly $1.5 billion per year (World Bank data) already move through MTN Mobile Money and Airtel Money corridors. Uganda is not subject to any US sanctions program and is not on the FATF blacklist, so standard screening is typically quick. The defining constraint is PayPal: Ugandan PayPal accounts can send money but cannot receive it — which is precisely the gap a US LLC plus US fintech banking closes.
Total realistic first-year cost: roughly $139–$500 depending on state and add-ons. Total realistic timeline: 1–3 days for the LLC, 3–8 weeks for the EIN (the IRS bottleneck for foreign applicants), then a few days for banking once your documents are complete.
Table of Contents
- Why Ugandan founders choose a US LLC
- US LLC basics in 90 seconds
- Legality: ownership, visas & compliance
- Choosing your state (with charts)
- True cost: year 1 and beyond
- Registered agent explained
- Step-by-step: Northwest walkthrough
- After formation: EIN, bank, payments
- US taxes for Ugandan owners
- No US–Uganda treaty: what that means
- Uganda-side taxes, the Shilling & Bank of Uganda
- Compliance calendar
- DIY vs formation services
- Common mistakes to avoid
- Use cases for Ugandan founders
- Master checklist
- FAQs
- Final thoughts
Why Ugandan Founders Are Forming US LLCs
Uganda is one of Africa’s youngest and most entrepreneurial economies — a median age under 17, one of the world’s highest mobile-money adoption rates, a Kampala tech scene that produces engineers and creators for global clients, and a diaspora sending home over a billion dollars a year. Yet the country’s freelancers and online businesses hit a well-known wall: PayPal accounts registered in Uganda can send payments but cannot receive them, marketplace payouts are slow or unsupported, and international card processing for local entities is limited. For Ugandan entrepreneurs — whether operating from Kampala, Entebbe, Jinja, Mbarara or the diaspora — a US LLC has become the standard instrument for reaching US and global clients directly.
- Payment rails: US clients, ad networks and marketplaces pay US entities with far fewer holds. A US LLC unlocks USD business accounts (Mercury, Relay, Wise Business) that plug into the mobile-money economy at the repatriation stage rather than depending on it for collections.
- The PayPal gap: Uganda’s most-cited freelancer complaint is real — PayPal restricts receiving in Uganda. A US LLC with US banking gives you receiving accounts that work with marketplaces, Stripe-style processors and direct client wires.
- Diaspora entrepreneurship: a large share of Ugandan-owned LLCs are formed by diaspora founders in the US, UK, Canada and the Gulf. The LLC formalises a US-facing business identity that matches where their clients actually are.
- Remittance economics: Uganda receives roughly $1.5 billion in remittances per year (World Bank data), much of it landing directly in MTN and Airtel mobile-money wallets. A US LLC professionalises business flows on top of that existing corridor.
- Remote services: Ugandan engineers, writers, translators (English, Swahili, Luganda, Runyankole) and virtual assistants serving international clients need a US entity to invoice and receive payment cleanly.
- Entity momentum: US business formation has been running above 5 million applications per year since 2021 (US Census Bureau, Business Formation Statistics) — a share of it from founders in East Africa’s digital economy.
- Liability shield: an LLC separates your personal assets from business liabilities — particularly important when operating across jurisdictions with different legal regimes.
US LLC Basics in 90 Seconds
A US Limited Liability Company (LLC) is a state-created business entity that blends corporate liability protection with partnership-style tax flexibility. It is not a corporation, and it does not require US citizenship, residency, or a US bank account to form.
| Term | Plain-English meaning | What it means for you in Uganda |
|---|---|---|
| Articles of Organization | The one-page certificate filed with the state that creates the LLC | Filed online by you or your formation service; approval = your LLC exists |
| Registered agent | A person/company with a physical address in the state to receive legal mail | Must be hired; you cannot act as your own agent from Kampala, Jinja or Mbarara |
| EIN | Employer Identification Number — the LLC’s tax ID from the IRS | Free; foreign owners apply by fax/mail (Form SS-4), no SSN needed |
| Operating agreement | Internal rulebook: ownership, voting, profit splits | Not filed publicly; banks and marketplaces often request it |
| Single-member LLC (SMLLC) | One owner; “disregarded entity” for US tax | The default structure for solo Ugandan founders |
| Member-managed vs manager-managed | Owners run it vs appointed managers run it | Member-managed is simplest for solo founders |
| Franchise tax / annual report | Yearly state fee to keep the LLC in good standing | Ranges from $0 (NM) to $800+ (CA) — see state chart below |
| Form 5472 | IRS information return for foreign-owned US disregarded entities | Mandatory annual filing even with $0 US tax; $25,000 penalty for skipping |
Legality: Can a Ugandan Citizen Own a US LLC?
Yes — with a clean, standard compliance profile. All 50 US states permit foreign individuals and foreign companies to own LLCs. There is no citizenship test, no residency test, and no requirement to ever visit the United States. Uganda is not subject to comprehensive or sectoral US sanctions, is not on the FATF list of high-risk jurisdictions, and Ugandan passports are routinely accepted by US fintechs during onboarding with standard identity screening.
Sanctions and screening checks (standard, and quick here)
Even with Uganda’s clean profile, you should run the standard checks every foreign founder should run:
- Check the OFAC Sanctions Search tool to confirm neither you, your co-founders, your major clients nor your counterparties appear on the SDN list.
- US banks and fintechs (Mercury, Relay, Wise) screen all foreign-owned entities as standard practice — expect identity-verification steps and occasional questions about your business model and fund sources.
- Sanctions lists change — monitor OFAC updates periodically throughout the life of your LLC.
Three legal myths, cleared
- “I need a visa.” No. Owning and remotely managing a US LLC from Uganda (or from the diaspora) requires no US visa. (Physically working inside the US is a different question — ownership alone does not grant work authorization. If relocation is the goal, speak to an immigration attorney; Uganda is not currently an E-2 treaty country.)
- “I need an SSN or ITIN.” No. The IRS issues EINs to foreign-owned LLCs via Form SS-4 filed by fax or mail, with the “foreign” box ticked and no SSN/ITIN on line 7b.
- “I need a US address.” Not yours personally. Your registered agent’s in-state address satisfies the state’s contact requirement, and formation services bundle mail forwarding if you want a business mailing address.
Choosing Your State: Wyoming, Delaware, New Mexico & the Rest
Your LLC can form in any state, but for a Uganda-based or diaspora-based owner with no US physical operations, the decision is almost purely about cost, privacy and future plans. Here is the shortlist that matters:
| State | One-time filing fee | Annual state cost | Privacy | Best for |
|---|---|---|---|---|
| Wyoming ⭐ | $100 | $60 min. annual report licence tax | Owners off public record | Default pick for non-residents: cheap, private, no state income tax |
| Delaware | $90 | $300 franchise tax (due June 1) | Members not listed on formation doc | Startups planning VC investment; court precedent (Court of Chancery) |
| New Mexico | $50 | $0 — no annual report, no franchise tax | Owners off public record | Lowest lifetime cost; set-and-forget freelancers |
| Florida | $125 | $138.75 annual report | Names public | Founders with genuine FL ties or LATAM-facing businesses |
| Texas | $300 | Franchise tax report (no tax due under ~$2.47M revenue) | Names public | Founders with real TX operations |
| Nevada | $425 initial | ~$350/yr (list + licence) | Partial | Rarely worth the cost for non-residents |
| California | $70 | $800/yr minimum franchise tax + $20 biennial statement | Names public | Only if you actually operate in CA |
Fees verified against Secretary of State fee schedules, September 2026. Confirm live before filing — states adjust fees periodically.
One-time state filing fee for LLC Articles of Organization (USD)
Source: state Secretary of State / Division of Corporations fee schedules (Sept 2026). Nevada total includes initial list of managers ($150) and state business licence ($200).
Recurring annual state cost to keep the LLC in good standing (USD)
Excludes registered-agent renewal (needed in every state, ~$125/yr with Northwest). California = $800 minimum franchise tax + $20 biennial statement of information amortised.
Our recommendation for Ugandan founders
- Wyoming (default): low entry ($100), low renewal ($60), no state income tax, owner privacy, and the most non-resident-friendly banking track record.
- Delaware (if fundraising): investors and accelerators expect Delaware; home to roughly two-thirds of the Fortune 500 and over 1.8 million registered entities (Delaware Division of Corporations). You pay for that prestige with a $300/year franchise tax.
- New Mexico (if minimizing): $50 in, $0/year forever after, no annual report to forget. The trade-off is slightly less name recognition with some banks.
The True Cost of Forming a US LLC from Uganda
Two cost layers: one-time (state fee + formation service + optional add-ons) and recurring (registered agent, state annual report/franchise tax, US tax filing help, accounting).
| Item | Typical cost | Frequency | Notes |
|---|---|---|---|
| State filing fee (WY example) | $100 | Once | $50 NM / $90 DE / $125 FL etc. |
| Northwest formation service | $39 | Once | Includes registered agent first year in current bundles — confirm at checkout |
| EIN (DIY via IRS fax/mail) | $0 | Once | Or paid add-on via formation service if you prefer hands-off |
| Operating agreement | $0–$100 | Once | Template included by many services; lawyer-drafted costs more |
| Registered agent renewal | ~$125/yr | Annual | Legally required every year |
| State annual report / franchise tax | $0–$800/yr | Annual | State-dependent (see chart above) |
| US tax return prep (Form 5472 package) | ~$250–$600/yr | Annual | DIY possible but penalty risk makes pros worth it |
| US business bank account | $0 | — | Mercury / Relay / Wise Business have no opening fee |
What you pay at checkout — Wyoming example (USD)
Based on Northwest’s published $39 + state fee pricing and Wyoming SOS fee schedule, Sept 2026.
3-year cumulative cost of ownership: Wyoming vs Delaware vs California (USD)
Illustrative model: state filing fee + $39 service in year 1, then annual state fee + $125 registered-agent renewal. Excludes tax-prep fees and one-off add-ons. California includes the $800 minimum franchise tax each year.
Ready to start? Northwest Registered Agent is our recommended formation service for non-US residents: flat $39 + state fee, in-house registered agent service, and a track record with foreign-owned LLCs.
Start Formation at Northwest →Registered Agent: The Requirement You Cannot Skip
Every US state requires your LLC to maintain a registered agent — a person or company with a physical street address in the formation state, available during business hours to accept service of process (lawsuits) and official state mail. From Uganda, you cannot fulfil this yourself.
- Cost: typically $100–$300/year market-wide; Northwest charges $125/year and bundles the first year with most formation orders.
- Privacy bonus: the agent’s address — not yours — appears on public filings as the official contact point.
- Compliance risk: letting the agent lapse triggers “administrative dissolution” in most states — your LLC loses good standing, and banks/payment processors freeze accounts until it is reinstated (with penalties).
We maintain a full independent write-up in our Northwest Registered Agent review, including how their mail-scanning dashboard behaves for overseas clients.
Step-by-Step: Form Your US LLC from Uganda with Northwest (7 Screenshots)
Below is the exact ordering flow we ran for a Ugandan-owned Wyoming LLC. The whole form takes 10–15 minutes; state approval then typically lands within 1–3 business days for Wyoming, Delaware and New Mexico online filings.
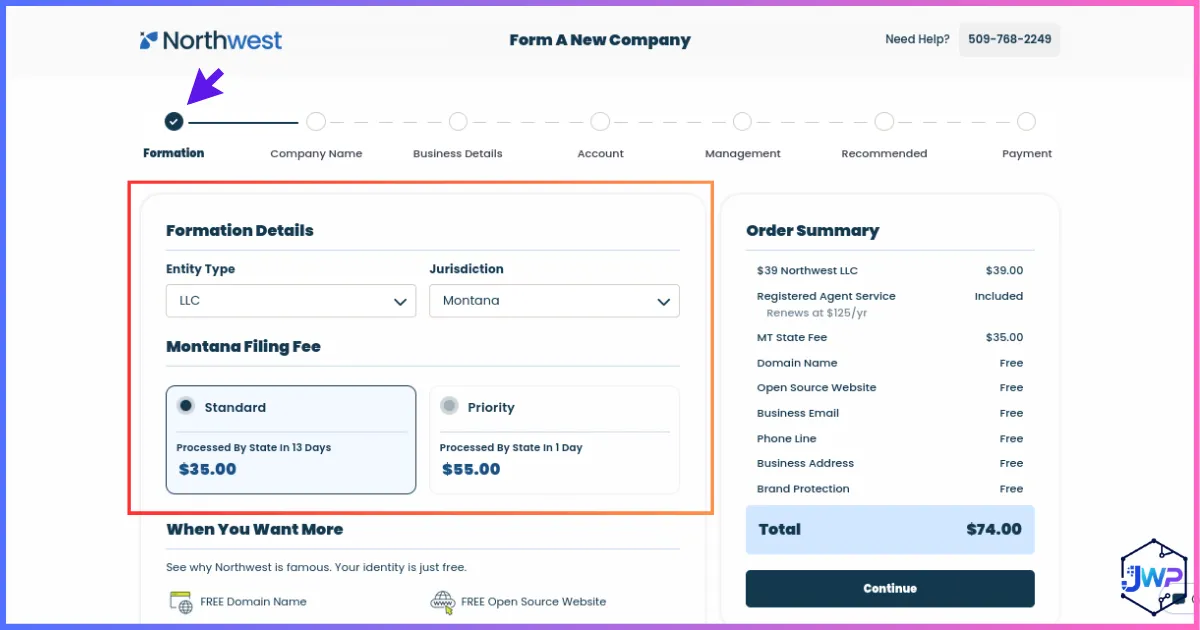
Open the order form and set formation details
Choose your entity type (LLC) and formation state. For most Uganda-based founders this is Wyoming; pick Delaware only if investment is on your roadmap.
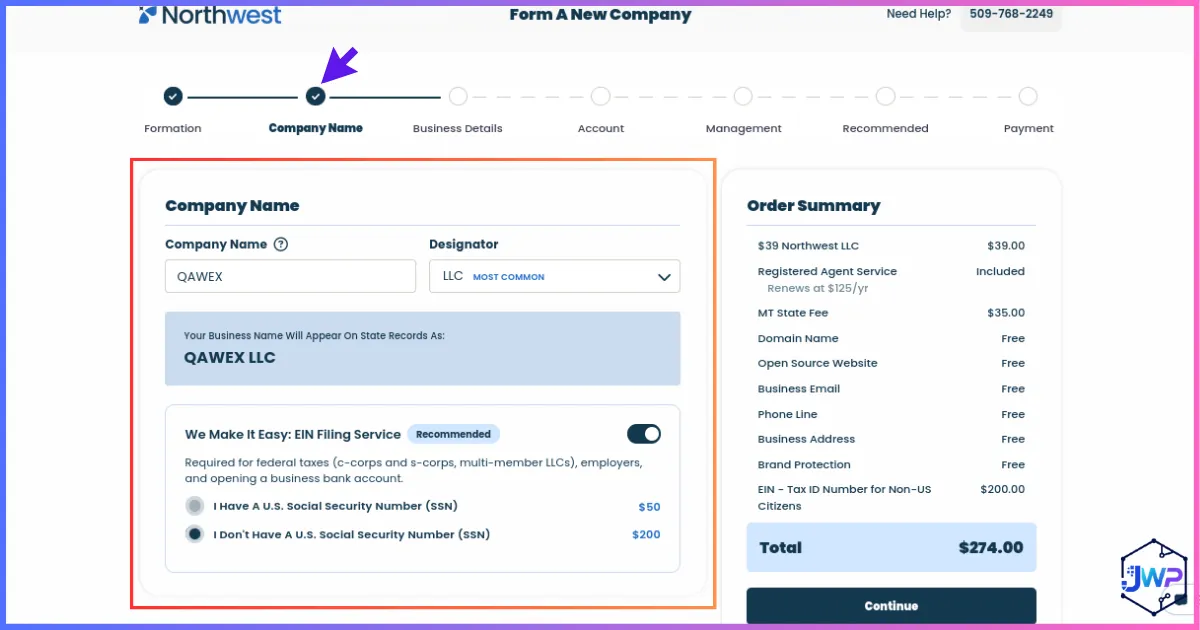
Add your company name (and decide on the EIN service)
Enter your desired LLC name exactly as it should appear, including the “LLC” or “Limited Liability Company” ending. Northwest runs the state availability check for you. On this screen you’ll also see the optional EIN service — recommended if you’d rather not handle IRS Form SS-4 fax correspondence yourself, but skippable to save money (we cover the free DIY route below).
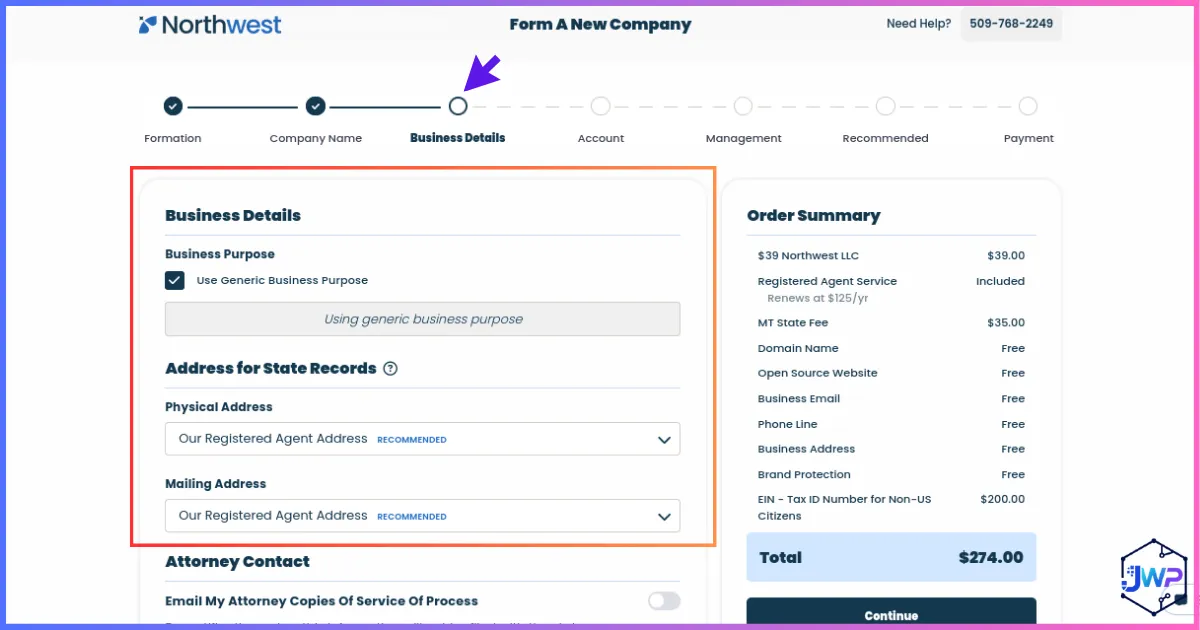
Enter business details
Purpose statement (a generic “any lawful business” line is standard and fine), your contact email, and mailing preferences. Your Ugandan residential address (or diaspora address, if you are based outside Uganda) is used for correspondence; the registered agent’s Wyoming address handles official state service.
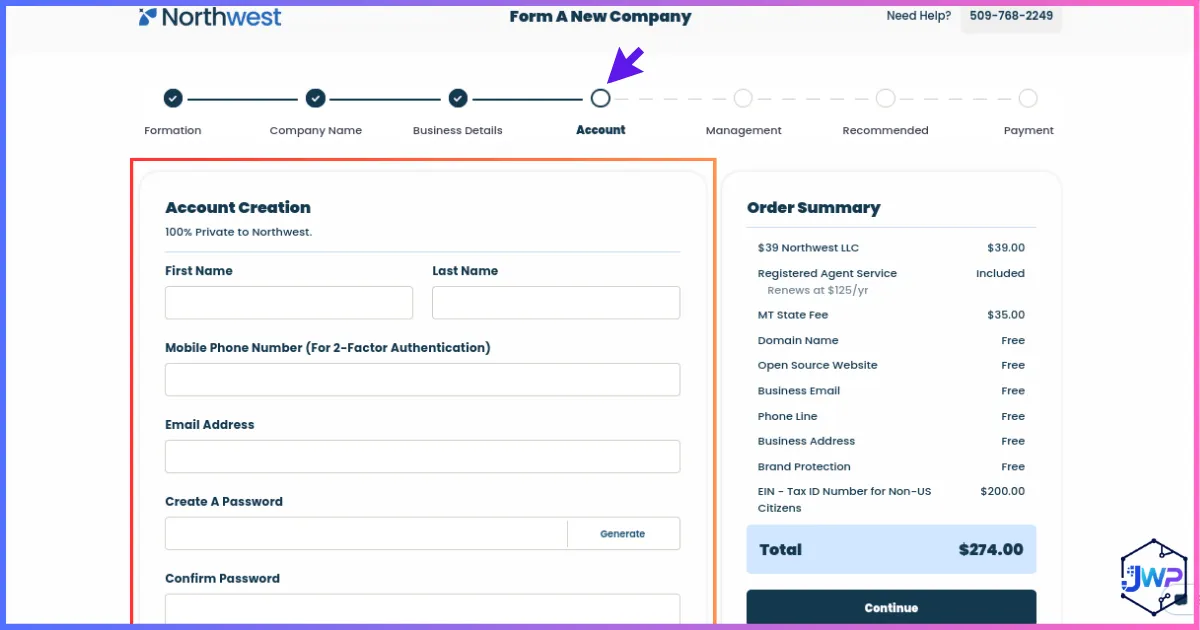
Create your client account
This account becomes your control panel: formation status, scanned mail from your registered agent, annual report reminders and renewal invoices. Use an email you’ll keep for years — losing access complicates renewals.
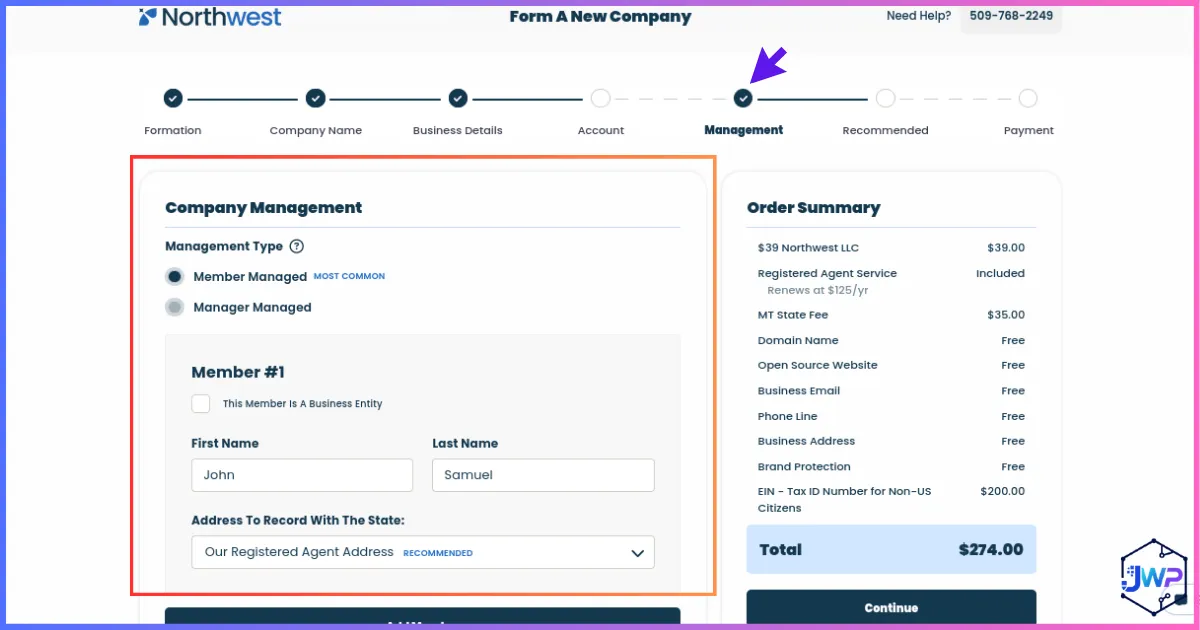
Enter company management details
Declare the management structure (member-managed for solo founders) and the owner’s details — name, residential address, and passport-based identity information. Ugandan passports are accepted; nothing on this screen requires US status.
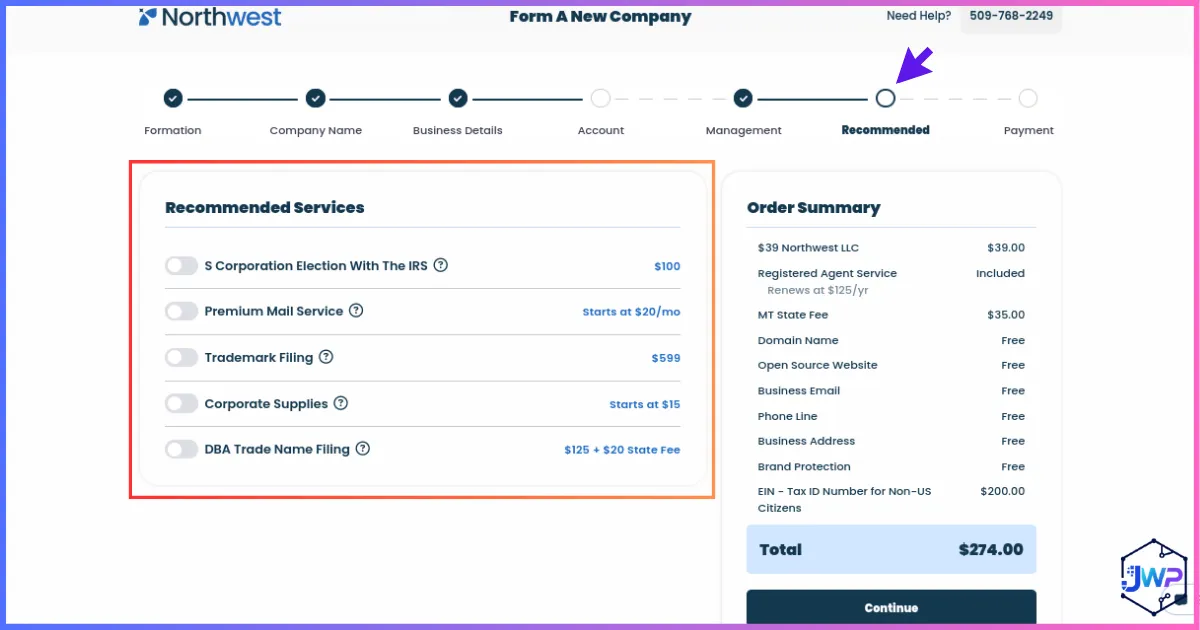
Review optional recommended services
Mail forwarding, certified copies, compliance monitoring and similar add-ons appear here. Honest advice: skip anything you can’t justify. Mail forwarding is the only one most non-residents eventually add.
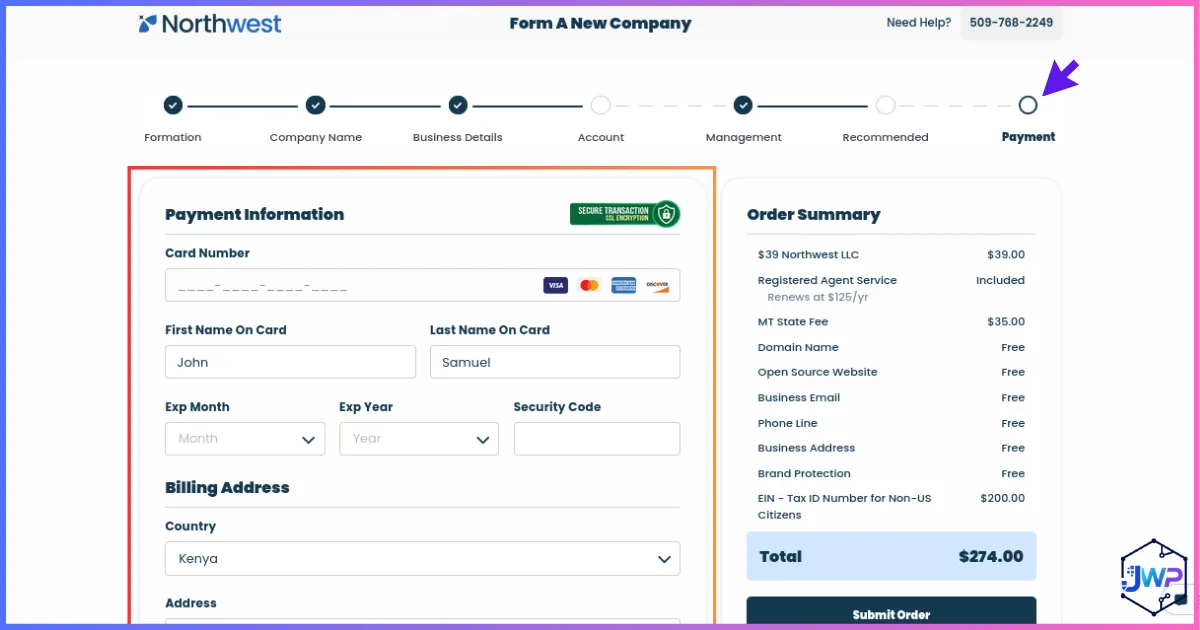
Enter payment information and submit
You’ll see the final breakdown — $39 service fee + your state’s filing fee (+ any add-ons) — before paying by card. After submission, Northwest prepares and files the Articles; you’ll receive the stamped formation documents by email once the state approves. Ugandan cards work well here: internationally enabled Visa/Mastercard from Stanbic, Standard Chartered, Centenary, Absa or Equity typically clears the charge; if yours is declined, enable international e-commerce with your bank or fund the order from a Wise/Payoneer USD balance.
After Formation: EIN, Operating Agreement, Banking & Getting Paid
1. Get your EIN (the foreign-founder route)
- Download Form SS-4 from IRS.gov and complete it for your LLC. On line 7b, leave SSN/ITIN blank and mark the foreign-owner indicators as instructed.
- Submit by fax (using the current international fax number published in the SS-4 instructions) or by mail if you prefer paper trails.
- Wait. IRS guidance suggests ~4 weeks by fax and 4–5 weeks by mail; foreign applications commonly land in the 3–8 week window during peak seasons. Paid formation-service EIN add-ons use the same IRS channels — they save effort, not time.
2. Adopt an operating agreement
Even single-member LLCs should sign one: banks, Stripe-style processors and marketplaces routinely request it, and it reinforces the liability shield by evidencing corporate separateness.
3. Open a US business bank account — from Uganda or the diaspora
- Mercury and Relay: US fintechs that onboard non-resident-owned LLCs with EIN + formation docs + passport; no US visit required. Ugandan-owned entities generally pass standard screening without the friction seen in sanctioned or high-risk jurisdictions.
- Wise Business: multi-currency USD/EUR/GBP account details; popular with Ugandan freelancers because it pairs cleanly with mobile-money withdrawals at the repatriation stage.
- Payoneer: receiving accounts for marketplaces (Amazon, Upwork enterprise billing, app stores).
PayPal needs care: Ugandan PayPal accounts can send but cannot receive money, and a US PayPal business account generally expects US tax status — so most Ugandan owners route client payments to Mercury/Wise instead. Our walkthrough on creating a US PayPal account as a non-US resident covers the eligibility realities and workarounds that stay compliant.
4. Invoice and get paid
Issue invoices from the LLC (US entity name + EIN + US bank details). For US clients paying for services you perform in Uganda or from the diaspora, provide Form W-8BEN (you, the foreign individual owner, since a single-member LLC is disregarded). Because Uganda has no income tax treaty with the US, you cannot claim treaty withholding relief — services performed entirely in Uganda with no US permanent establishment are generally outside US taxing rights regardless, but FDAP income like royalties and dividends remains subject to the standard 30% withholding. More in the treaty section below.
US Taxes for Ugandan LLC Owners: What You Owe (and What You Don’t)
The income-tax picture
A single-member LLC owned by a non-resident alien is a disregarded entity: the IRS looks through it to you. If you have no US trade or business — no US office, no US employees, no dependent agents in the US, and services performed from Uganda or a third country outside the US — your business income is generally not US-source and owes $0 US income tax. There is also no US self-employment tax for non-residents on foreign-performed services.
The filing you must not skip: Form 5472
Foreign-owned single-member LLCs must file Form 5472 together with a pro-forma Form 1120 every year — even with zero US tax and zero US activity. The failure penalty is $25,000 per violation under IRC §6038A. See the official IRS Form 5472 guidance for the current filing mechanics.
Other US tax touchpoints
- State level: Wyoming/Delaware-style LLCs with no in-state activity generally owe no state income tax, but the franchise/annual report fees in the charts above still apply.
- Sales tax / marketplace rules: selling digital or physical goods into US states can create economic-nexus sales-tax obligations independent of income tax — get advice before scaling e-commerce.
- Multi-member LLCs: become partnerships (Form 1065 + foreign-partner withholding rules) — a materially harder compliance load; structure deliberately.
- BOI reporting: under FinCEN’s 2025 interim final rule, US-domestic LLCs are not currently required to file Beneficial Ownership Information reports; foreign-formed entities registered in the US remain in scope. Rules are in flux — re-check FinCEN before assuming permanence.
No US–Uganda Tax Treaty: What That Means in Practice
Like Kenya, Tanzania, Rwanda and most of Sub-Saharan Africa (and unlike South Africa and Egypt, which have operative US treaties), Uganda has no bilateral income tax treaty with the United States. The US Treasury’s tax treaty table lists Uganda as having no operative treaty. This is an important factual difference for Ugandan founders planning long-term profit repatriation.
What the absence of a treaty means
- Standard withholding applies: US-source FDAP income (dividends, royalties, certain rents) paid to you as the disregarded owner of the LLC is generally subject to the full 30% US withholding, with no reduced treaty rate to claim.
- W-8BEN claims are limited: you can still file W-8BEN to certify foreign status and avoid backup withholding, but you cannot claim treaty-reduced rates on FDAP income — there is no treaty article to cite.
- Services performed in Uganda remain outside US taxing rights: business income from services performed entirely in Uganda with no US permanent establishment is generally not US-source regardless of the treaty picture. The absence of a treaty does not create new US tax on your locally performed services.
- No treaty mutual-agreement or tie-breaker relief: if both countries assert taxing rights over the same income, resolution depends on domestic law on both sides rather than a treaty dispute mechanism.
What the absence of a treaty does NOT change
- It does not exempt US filing obligations. Form 5472 is still due. State annual reports are still due. EIN is still required.
- It does not restrict your BoU framework. The Shilling floats freely and outbound transfers are liberal under Bank of Uganda rules — the absence of a treaty is irrelevant to moving your money.
- It does not grant visa or immigration rights. Uganda is not an E-2 treaty country; no treaty means no treaty-investor visa pathway either.
The Uganda Side: Bank of Uganda, the Shilling & Domestic Taxes
A US LLC does not switch off Ugandan tax or foreign-exchange obligations — but Uganda’s framework is one of East Africa’s most liberal for international business, and its mobile-money rails make the last mile of repatriation uniquely efficient.
The Shilling and the Bank of Uganda
- Free float, no parallel market: the Ugandan Shilling (UGX) floats under a liberal Bank of Uganda (BoU) framework — no fixed parity, no meaningful parallel-market spread, and no approval regime for ordinary business transfers.
- Liberal outward transfers: residents can hold foreign-currency accounts and transfer abroad with standard bank documentation; there is no annual allowance cap comparable to pegged-currency neighbours.
- Mobile-money last mile: inbound international remittances from WorldRemit, Remitly, Xoom and Wise settle directly into MTN Mobile Money and Airtel Money wallets — the same rails carry roughly $1.5 billion per year (World Bank) into the economy.
- Deep banking competition: Stanbic, Standard Chartered, Centenary, Absa, Equity, dfcu and Bank of Baroda all run FX desks; shop spreads on USD/UGX conversion.
- Practical consequence: most Uganda-based founders keep operating balances in USD inside the US LLC and repatriate to UGX through a bank or Wise→mobile-money corridor in tranches timed to Shilling volatility (UGX has traded roughly 3,500–3,900 per USD in recent years).
The remittance corridor Uganda already runs on — annual inflows, selected East African countries (USD billions)
Approximate annual worker-remittance inflows, World Bank Migration & Remittances data (recent editions). Uganda’s corridor is second only to Kenya’s in the region — a US LLC professionalises business flows beyond family remittances on rails that already exist.
Ugandan domestic taxes (if you operate locally)
- Personal income tax: progressive rates topping out at 40%, administered by the Uganda Revenue Authority (URA) under the Income Tax Act (Cap 340).
- Corporate income tax: standard 30% on company profits — applies only if you additionally operate a local entity registered through URSB (Uganda Registration Services Bureau).
- VAT: 18% on taxable supplies, with URA registration thresholds.
- Withholding on non-residents: Ugandan-source income paid to non-residents (royalties, management fees, technical-service fees) attracts local withholding — if your US LLC contracts with Ugandan clients from abroad, get local advice on which side withholds.
- Digital-service levies: Uganda has introduced excise and digital-tax measures in recent finance acts — monitor them if you sell digital products into or out of Uganda.
Your Annual Compliance Calendar
| Task | When | Cost | Consequence of skipping |
|---|---|---|---|
| State annual report / licence tax (WY) | Anniversary month (state-dependent) | $60 (WY) | Administrative dissolution |
| DE franchise tax (if Delaware) | By June 1 | $300 | Penalties + interest + loss of good standing |
| Registered agent renewal | Yearly | ~$125 | Agent resigns → state notices missed → dissolution risk |
| Form 5472 + pro-forma 1120 | April 15 (calendar year; extensions available) | $0 DIY / ~$250–600 preparer | $25,000 penalty per violation |
| OFAC SDN list re-check (recommended) | Quarterly | $0 (self-check) | Unintentional sanctions exposure |
| Ugandan domestic tax return (if resident in Uganda) | Per URA schedule | Per URA rules | Local penalties and interest |
| Country-of-residence tax return (if diaspora-based) | Per local schedule | Per local rules | Local penalties and interest |
| Bookkeeping catch-up (Mercury + Wise + Payoneer) | Quarterly recommended | Time / software | Messy 5472 filings |
Once money flows, decide deliberately how you’ll compensate yourself — our guide on how to pay yourself as an LLC compares draws, salaries and dividends for non-resident owners.
DIY vs Formation Services: What Should a Ugandan Founder Do?
| Route | Cost | Effort | Best for |
|---|---|---|---|
| Full DIY (state site + own RA search + SS-4 fax) | State fee + RA fee only | High — you own every mistake | Experienced founders comfortable with US paperwork |
| Northwest ($39 + state) ⭐ | Low, flat, transparent | Low — guided form, in-house RA, mail scanning | Most non-residents; privacy-minded founders |
| Bizee / similar budget brands | Low headline price; upsells at checkout | Medium | Price-shoppers who read checkout screens carefully — see our Bizee walkthrough |
| Premium non-resident bundles (doola, Business Anywhere) | $299–$500+ | Lowest — banking introductions bundled | Founders who want concierge onboarding; compare in our doola review and Business Anywhere walkthrough |
For a fuller market comparison including current non-resident eligibility, see our roundup of the best LLC formation services for non-US residents.
Common Mistakes Ugandan Founders Make (and How to Avoid Them)
❌ The mistakes
- Forming in California/New York “because it’s famous” and inheriting $800/yr or publication costs
- Skipping Form 5472 because “I owe no US tax” → $25k penalty exposure
- Letting the registered agent lapse → administrative dissolution → frozen bank account
- Converting all USD revenue to UGX immediately and losing control of conversion timing on a volatile Shilling
- Assuming the LLC grants US work rights or a visa pathway (Uganda is not an E-2 country)
- Ignoring URA obligations while resident in Uganda, or country-of-residence tax if diaspora-based
- Running LLC revenue through personal mobile-money wallets that pierce the liability shield and muddy documentation
- Applying for the EIN twice out of impatience → duplicate EINs
- Assuming PayPal receiving will work from Uganda — it won’t; plan Mercury/Wise/Payoneer from day one
- Claiming treaty benefits on W-8BEN when no Uganda–US treaty exists
✅ The fixes
- Default to WY / NM for cost, DE only for fundraising
- Diary the 5472 from day one; budget a preparer
- Auto-renew the registered agent on the same card as your domain renewals
- Keep the operating balance in USD; convert to UGX in tranches through the best-spread bank or Wise corridor
- Treat the LLC as a payments/liability tool; handle immigration separately
- Get URA-side advice if resident in Uganda and local-country advice if diaspora-based
- Invoice only from the LLC; keep business and personal flows strictly separate
- File SS-4 once, track the fax, wait the window out
- Build your payment stack on US fintechs from the start — not on services that can’t receive in Uganda
- Use W-8BEN correctly: certify foreign status, do NOT claim treaty rate reductions
Use Cases: Who Benefits Most from a Ugandan-Owned US LLC?
- ☐ Run OFAC SDN search on yourself and major counterparties before filing
- ☐ Choose state (WY default / DE for fundraising / NM for minimum cost)
- ☐ Search & reserve your LLC name (must end LLC / Limited Liability Company)
- ☐ Prepare an internationally enabled card or Wise/Payoneer USD balance for checkout
- ☐ Order formation via Northwest ($39 + state fee) with registered agent bundled
- ☐ Receive stamped Articles of Organization + agent confirmation
- ☐ Sign operating agreement (keep with records, don’t file)
- ☐ File Form SS-4 by fax/mail for EIN (or use the paid add-on)
- ☐ Open Mercury / Relay / Wise Business account with EIN + docs
- ☐ Set up invoicing + W-8BEN without treaty claims for US clients
- ☐ Plan USD→UGX repatriation through your best-spread bank or Wise→mobile-money corridor, in tranches
- ☐ Diary: state annual report, agent renewal, Form 5472 (April 15), OFAC re-checks
- ☐ Get URA-side advice (if resident in Uganda) and country-of-residence advice (if diaspora-based)
FAQs: Forming a US LLC from Uganda
Can a Ugandan citizen 100% own a US LLC?
Does Uganda have US sanctions or FATF restrictions I should worry about?
Do I need a US visa, SSN or ITIN?
Which state is best for someone living in Kampala, Entebbe, Jinja, Mbarara, or in the diaspora?
How much does it cost in total for year one?
How long does the whole process take?
Does Uganda have a tax treaty with the US?
Will I pay US income tax while living in Uganda or the diaspora?
How do Bank of Uganda exchange rules affect my US LLC?
Can I open a US business bank account without travelling?
Why not just use PayPal or MTN Mobile Money?
Does owning a US LLC help me move to the US?
What happens if I forget the annual report or registered agent renewal?
I’m diaspora-based (US/UK/Canada/Gulf). Does any of this change?
Final Thoughts: Is a US LLC Worth It for Ugandan Founders?
For Ugandan freelancers tired of the PayPal receiving gap, Kampala-based developers and creators, diaspora entrepreneurs and agri-traders serving US and global markets, a US LLC is close to essential infrastructure: ~$139 to start in Wyoming, 1–3 days to exist, and a USD-denominated, liability-shielded business identity with receiving accounts that actually work — on a home-country rails system (mobile money, liberal FX, $1.5B remittance corridor) that makes spending the money back home easy.
The honest trade-off Ugandan founders accept is discipline over difficulty: no US tax treaty means 30% withholding on US FDAP income and no treaty relief to claim, UGX volatility rewards tranche-based conversion planning, and the URA obligations continue if you operate locally. None of these are blockers — they are calendar items. Compared with founders in most neighbouring jurisdictions, Ugandans start with a payments-rails advantage at home that compounds once the US side is set up.
The obligations are real but finite — a registered agent, an annual report, one IRS information return, quarterly OFAC re-checks, and honest tax planning in every jurisdiction where you have a filing obligation. Do it in the right order (OFAC check → entity → EIN → bank → invoicing → compliance calendar), avoid the $25,000 Form 5472 trap, respect the BoU framework, and the LLC becomes quiet infrastructure that pays for itself with the first US contract it unlocks.
Sources & Research Notes
All fees and rules verified September 2026 against the primary sources below. US state fees, IRS procedures, FinCEN rules, Bank of Uganda regulations and Ugandan tax law change — confirm live before filing.
- US Census Bureau, Business Formation Statistics — annual US business applications exceeding 5 million since 2021.
- IRS — official Form 5472 guidance; Form SS-4 instructions (EIN application; foreign applicant fax/mail routes; $0 cost) and IRC §6038A penalty provisions ($25,000 per violation).
- US Treasury / IRS Tax Treaty Tables — confirms Uganda has no operative bilateral income tax treaty with the United States.
- FinCEN — Beneficial Ownership Information interim final rule (2025): domestic reporting companies exempt; foreign-formed registrants remain in scope.
- World Bank, Migration & Remittances — Uganda remittance inflows of roughly $1.5 billion per year in recent editions.
- OFAC Sanctions Search — standard SDN screening for founders and counterparties (no Uganda-specific comprehensive program).
- Bank of Uganda (BoU) — the Shilling’s free-float arrangement and the liberal foreign-exchange framework for residents.
- Uganda Revenue Authority (URA) — personal income tax (progressive to 40%), corporate income tax (30%) and VAT (18%) under the Income Tax Act (Cap 340); confirm current thresholds with a local adviser.
- Uganda Registration Services Bureau (URSB) — domestic company registration formalities.
- Wyoming Secretary of State — LLC filing fee ($100) and annual report licence tax (minimum $60).
- Delaware Division of Corporations — LLC formation fee ($90), $300 annual franchise tax; entity counts and Fortune 500 incorporation statistics.
- New Mexico Secretary of State — $50 LLC filing fee; no annual report requirement for LLCs.
- Florida Division of Corporations (Sunbiz) — $125 formation ($100 articles + $25 registered agent designation); $138.75 annual report.
- Texas Secretary of State — $300 LLC formation fee; Comptroller franchise-tax no-due threshold (~$2.47M).
- California FTB / SOS — $70 formation, $800 minimum annual franchise tax, $20 biennial statement of information.
- Nevada Secretary of State — initial fees ($75 articles + $150 initial list + $200 business licence) and annual renewals.
- Northwest Registered Agent — published formation pricing ($39 + state fee) and registered-agent renewal pricing ($125/yr).