How to Form a UK Limited Company from Nigeria
You can form and own a UK private limited company while living in Nigeria. You do not need to relocate or appoint a UK-resident director. This guide explains the UK requirements, real cost components, a 21-screen formation walkthrough and what to prepare locally. For Nigerian founders, special attention belongs to the 2026 Nigerian tax reforms, truthful financial-provider applications, and funding in sterling from naira.
Affiliate disclosure: We may earn a commission if you buy through our 1st Formations links, at no extra cost to you. Direct Companies House registration and other agents are alternatives. This guide does not promise banking approval or tax savings.
Quick Answer: How to Form a UK Limited Company from Nigeria
A founder living in Nigeria can register a UK company limited by shares online and own all its shares. Choose a compliant name, arrange an appropriate UK registered office, verify the directors’ identities, identify shareholders and PSCs, choose a SIC code and submit the incorporation application.
Use SIC 99999 — Dormant Company if the company is being formed to remain dormant. Use an accurate trading activity code if it will operate. Dormancy is determined by activity and transactions, not the code alone.
After approval, verify the register, complete any separate PSC verification requirement, organise official mail, bookkeeping and eligible banking, and set the UK filing calendar. Obtain local advice on the 2026 Nigerian tax reforms, truthful financial-provider applications, and funding in sterling from naira before funding or trading through the company.
Table of Contents
When a UK Limited Company Makes Sense for a Nigerian Founder
A UK Ltd is a separate legal entity. It can enter contracts, own assets, hire staff and have shareholders. For a Nigerian business expanding into Britain, it can provide a clear local contracting entity and a structure for UK operations.
It can also add administration without solving a real business problem. A Nigerian freelancer with Nigerian clients may already have an adequate domestic structure. Opening a second company just to obtain a UK address or a payment account can leave you with two sets of compliance costs.
Reasons to consider it
- You are establishing a genuine UK operation, team or subsidiary.
- A UK customer or partner has a commercial reason to contract with a UK entity.
- You need a separate vehicle for a UK product, investment or joint venture.
- You have priced the accounting and Nigerian reporting into the business model.
Reasons to pause
- Your only goal is to avoid Nigerian tax.
- You assume incorporation guarantees a bank or payment account.
- You expect an address service to prove physical UK operations.
- You have no plan for official mail, bookkeeping or annual filings.
Ask a practical question: what will the UK company do that the existing Nigerian business cannot do efficiently? A written answer helps you choose the ownership structure, account provider and package without buying unnecessary services.
For a broader eligibility overview, see our guide to forming a UK limited company as a non-resident.
UK company incorporations: April–June 2026
Monthly incorporations, all company types. The quarter recorded 192,287 incorporations; 5,516,377 companies were on the register at the end of June.
Scale: 0–80,000 incorporations. Source: Companies House, released July 30, 2026. These are registrations, not evidence of profitability, Nigerian ownership or banking success. [4]
Can Someone in the Nigeria Legally Form a UK Limited Company?
Yes. Directors do not have to live in the UK. A private company needs at least one director, and an individual director must be at least 16. A private company does not have to appoint a company secretary. Disqualification and bankruptcy restrictions can affect whether a person may act as a director. [2]
Your genuine residential address in Nigeria can be supplied as your actual home address. The company itself needs an appropriate registered office in its UK incorporation jurisdiction. There is no general requirement to give a Nigerian founder a UK co-owner or appoint a nominee just because they live overseas.
Citizenship, location and tax residence are different
Living in Nigeria does not establish every tax outcome. Nationality, personal residence, the legal shareholder and the company’s actual management location all matter. A citizen living abroad and a resident operating locally should not automatically be given the same advice.
If a Nigerian company will own the shares, decide that before filing. Corporate-parent ownership, trusts and personal holdings can have different control and tax results. Ask advisers to draw the intended structure and document the funding before entering shareholder names.
A director’s role continues after the application
Directors must make sure the company’s accounts and reports are prepared correctly and its statutory obligations are met. Paying an agent or accountant does not transfer that responsibility away from the board. [5]
- Use accurate personal details and keep the company’s information current.
- Understand the company’s finances before signing accounts or approving distributions.
- Manage conflicts, approvals and contracts carefully, especially where you own another business.
- Make arrangements for someone to handle urgent UK correspondence while you are unavailable.
UK Ltd vs a Local Company vs UK LLP
Choose the structure around the business purpose. A UK Ltd, a Nigerian company and a UK LLP are not interchangeable just because each can be used in business. Assess ownership, tax, customers, funding and the place where the work happens.
| Option | Commercial role | What to resolve before choosing |
|---|---|---|
| UK private company limited by shares | Separate UK contracting or operating entity | UK corporate filings plus Nigeria residence, owner income and local-operation rules |
| A Nigerian company | Business organised around domestic operations | Whether it can serve the customers directly and whether a UK subsidiary adds value |
| UK LLP | Genuine multi-member venture using a partnership-style structure | At least two members; UK and home-country tax treatment must be assessed |
| US LLC alternative | A separate alternative where the business actually needs a US entity | State and federal obligations plus home-country classification; it is not a UK Ltd |
Do not assume that overseas incorporation creates a lower total tax bill. A second company adds another legal person, separate records and potential cross-border transactions. Compare the annual administrative cost with the commercial benefit before buying a package.
For the US alternative, our formation services guide for non-US-resident LLC owners provides background. If your plan involves two or more members, see forming a UK LLP as a non-resident. Neither comparison replaces local classification advice.
If you already trade personally in Britain, moving activity into a company is a separate project. See changing from sole trader to a UK limited company for the contracts, assets and registration questions to review.
What You Need Before Starting the Application
Preparing a single information sheet makes the registration faster and reduces inconsistencies between your formation, banking and tax records. Keep identity documents and personal codes in a secure location rather than in a shared public folder.
| Prepare | What to decide or collect | Why it matters |
|---|---|---|
| Legal company name | Preferred name and one or two alternatives | Availability is not trademark clearance |
| Jurisdiction | England and Wales, Scotland, or Northern Ireland | Registered office must match the jurisdiction |
| Registered office and email | Provider permission, mail-handling agreement and monitored email | The company must be reachable |
| Director details | Legal name, birth date, nationality, occupation, home and service addresses | Identity and filing information must agree |
| Verified identity | Companies House personal code for every proposed director | Required for new-company director registration |
| Shareholders and PSCs | Who owns shares and who controls votes or board appointments | Legal ownership and control must be disclosed correctly |
| Share structure | Number, nominal value, class, rights and paid/unpaid status | Defines ownership and shareholder obligations |
| Business activity | Appropriate SIC code; 99999 for a dormant company | Describes intended activity accurately |
| Constitution | Memorandum and articles; advice for bespoke arrangements | Sets the company’s governance rules |
| Cross-border plan | UK accountant, Nigerian adviser, bank shortlist and filing budget | Formation alone does not create an operational business |
Choose a name that can actually be used
A name cannot be the same as an existing registered name under the naming rules. Sensitive words or a suggestion of government connection can require permission. Companies House availability also does not settle trademark rights. [7]
Check the brand separately in your target markets, including website domains and relevant trademarks. A clean formation search is useful, but it is not a guarantee that a competitor cannot object to your use of the brand.
Keep share capital proportionate
For an uncomplicated sole-owner company, one ordinary £1 share is a common illustrative arrangement. One hundred £1 shares can make whole-share percentage allocations easier. Neither arrangement means the business is funded adequately, and the appropriate rights depend on your plan.
Record whether the subscribed amount is paid or unpaid. Share capital, a shareholder loan and an expense reimbursement are different accounting entries. If there are multiple owners, agree voting, exits, transfers and dispute procedures before choosing a default constitution.
Companies House Identity Verification and PSC Requirements
Identity verification became a legal requirement on November 18, 2025. For a new company, the incorporation filing requires the personal code for each director. A person who becomes a PSC after that date can provide their code when added to the register or within 14 days of being added.
If you are both a director and a PSC, the code must be provided separately for each role. Do not assume recording it as a director completes the PSC requirement. [8]
How a Nigeria-based founder can verify identity
The official service uses GOV.UK One Login. Its app route can accept a valid biometric passport from any country. Verification through Companies House is free. Alternatively, an Authorised Corporate Service Provider, or ACSP, can verify you; it may charge a fee. Available methods depend on your documents and circumstances. [9]
Follow the official Companies House identity-verification guidance before the application. Use the same legal name and birth details across all records. Keep your code private and share it only when needed with a trusted filing agent.
A formation provider may also perform its own anti-money-laundering checks. Ask explicitly whether those checks satisfy Companies House verification and whether the provider is acting as an ACSP. Uploading a passport during checkout is not proof that every statutory verification step has been completed.
Who counts as a person with significant control?
Common PSC conditions include holding more than 25% of shares or voting rights, or the right to appoint or remove a majority of directors. Significant influence or control can also qualify. Exactly 25% does not, by itself, meet the “more than 25%” shareholding condition. [10]
In a straightforward 100%-owned company, the sole individual shareholder is normally a PSC. With holding companies, trusts, agreements or indirect holdings, identify the actual reportable control structure rather than selecting “no PSC” because the ownership chart is complicated.
UK Registered Office, Service Address and Nigerian Home Address
The registered office must be a physical, appropriate address in the company’s incorporation jurisdiction. Someone acting for the company must be made aware of delivered post, and delivery must be capable of acknowledgement. A Royal Mail PO Box, or a similar service alone, is not acceptable. A monitored registered email is also required and is not published on the public register. [11]
| Address | Purpose | Practical choice for a Nigerian founder |
|---|---|---|
| Registered office | Official company correspondence; publicly listed | A compliant provider address in the correct UK jurisdiction |
| Director service address | Official correspondence for the individual; publicly listed | Provider’s permitted service address or another valid correspondence address |
| Usual residential address | Actual home address supplied for the director | Your genuine Nigerian home address; generally protected from public disclosure |
| Business/trading address | Where the business operates or receives commercial mail | Describe actual operations; use a mail service only within its agreed scope |
| Forwarding address | Destination for scanned or physically forwarded mail | A current monitored destination, which can be in the Nigeria |
A registered office package may cover Companies House and HMRC mail but exclude customer letters, parcels or business correspondence. A business-address service may be a separate purchase. Read the coverage before using one address everywhere.
Questions to ask an address provider
- Which jurisdiction does the address support?
- Are registered office and director service-address use both included?
- Which types of government and business mail are accepted?
- How quickly are scans sent, and are they retained securely?
- Does physical forwarding to the Nigeria cost extra?
- What is the renewal price, and what happens if payment fails?
Privacy is useful, but a public UK address does not make a remotely operated business physically established in Britain. Banks, payment providers and VAT rules can look beyond the address to actual management and activity.
How Much Does It Cost to Form a UK Limited Company from Nigeria?
As of October 2026, the Companies House digital incorporation fee is £100. Postal incorporation is £124. The digital confirmation statement fee is £50, payable with the first statement in each 12-month payment period. It is not charged for every additional statement filed in that same period. [1]
Formation agents can bundle the filing fee into a package or show it separately. Read the checkout total before adding £100 to an advertised price. This guide does not quote an unverified 1st Formations package price.
| Budget item | Status | What to check |
|---|---|---|
| Companies House incorporation | Mandatory filing fee | £100 digital; confirm whether included in agent package |
| Agent preparation/submission | Optional if filing yourself | Current package price and exact scope |
| UK registered office | Mandatory address; paid service if you lack a suitable one | Annual renewal, permission, scan coverage and international forwarding |
| Director service address | Separate function; paid service optional | Included or separately billed; permitted users |
| Identity verification | Mandatory for relevant individuals | Official service free; ACSP fees can vary |
| Confirmation statement | Recurring company obligation | £50 digital per payment period; agent filing charge may be extra |
| UK accounts and tax preparation | Required work; professional help depends on circumstances | Dormant versus trading scope, software, VAT and payroll |
| Nigerian tax and information reporting | Depends on ownership and tax status | Foreign-company experience, number of forms and annual fee |
| Banking and payments | Operational choice | Account fees, FX spread, transfer charges and settlement costs |
Government filing fees: digital versus paper
Common scale: £0–£124. These are separate transactions, not a combined package. Source: Companies House fees, effective February 1, 2026. [1]
Budget for the company’s life, not just its certificate
Request UK and Nigerian accounting quotes before buying a package. Describe the owner’s tax status, projected revenue, activity, countries involved and anticipated transactions with other businesses you control. A cheap registration can still produce substantial annual compliance costs.
Illustrative £1,000 planning reserve
Original budgeting illustration, not provider pricing, a market average, or a sufficient budget recommendation. Only the £100 filing fee is statutory. Replace the £300 and £600 allowances with quotes; cross-border accounting and tax work can exceed this reserve.
Maintain costs in GBP and NGN in your own budget. The sterling filing fee does not change because the exchange rate moves, but your card issuer’s conversion and foreign-transaction charges can affect what you pay.
Direct Companies House Filing vs 1st Formations vs Other Agents
The direct route gives you control over the application. An agent can help prepare the filing and provide address or administrative services. Neither route replaces UK accounting or Nigerian cross-border tax work.
| Route | Useful when | Main limitation |
|---|---|---|
| Direct Companies House registration | You have the required information, verified identities and a suitable UK address | You arrange address services and ongoing support yourself |
| 1st Formations | You want a guided order flow and a package to compare for remote formation | Package contents, add-ons and annual renewals must be reviewed |
| Another formation agent | A different address, service scope or support model better fits the business | Compare current terms rather than headline price alone |
| Accountant or solicitor-led setup | Ownership, governance or cross-border structure needs bespoke work | Professional fees exceed a basic filing-only service |
GOV.UK says companies are usually registered within 24 hours through its online route. Postal applications normally take 8–10 days. Name issues, missing information and checks can extend the process. A provider’s order confirmation is not the same as incorporation approval. [3]
Compare service scope in our UK company formation agents guide, the 1st Formations versus Your Company Formations comparison, and our Your Company Formations review. Recheck live checkout terms before paying.
Look for clear cancellation terms, reliable overseas support and a way to export documents. If you use an agent, make sure you know which future filings are included, which require an additional instruction and which remain entirely your responsibility.
How to Form a UK Limited Company from Nigeria: 21-Step Walkthrough
The following walkthrough uses the supplied 1st Formations screenshots. They are reference examples, not a live inspection of the provider’s checkout. Page order, pricing, identity checks and package options can change. Follow the current prompts while using these explanations to understand the decisions.
For a provider-focused companion, see our complete 1st Formations company formation guide.
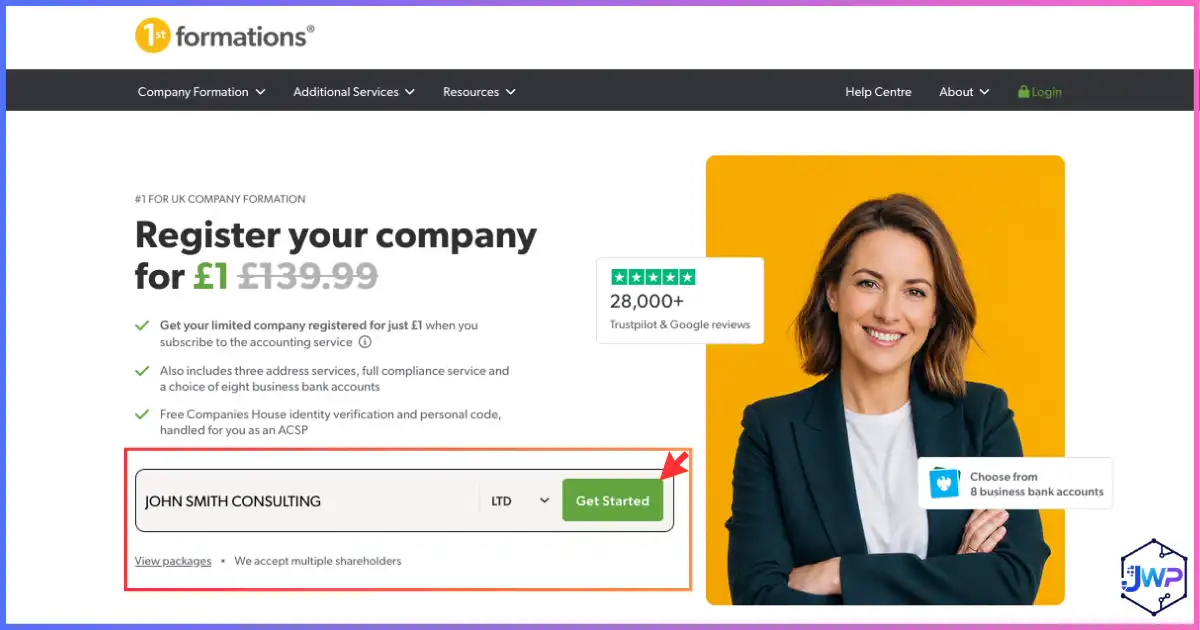
Step 1: Enter your proposed limited company name
Start with the legal company name you want to register. Use a distinctive name and check the spelling carefully. The legal name should be consistent with the name you intend to use on contracts and account applications.
Keep alternatives ready in case the name is unavailable or requires permission. A company name check is separate from trademark, domain and social-handle research.
Step 2: Review the name-availability result
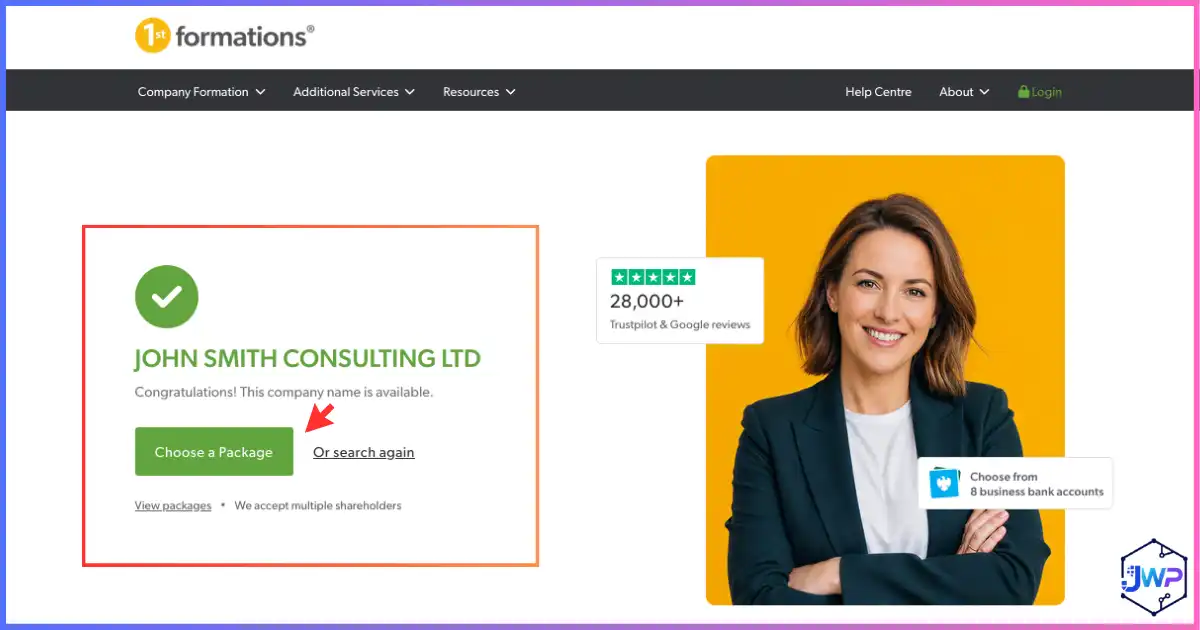
An available result means you can proceed with that name in the order flow. It does not reserve the name indefinitely, guarantee Companies House acceptance or give you trademark rights.
Recheck the displayed name, including the intended Limited or Ltd ending. If the name implies a regulated activity, make sure the required permissions have been considered.
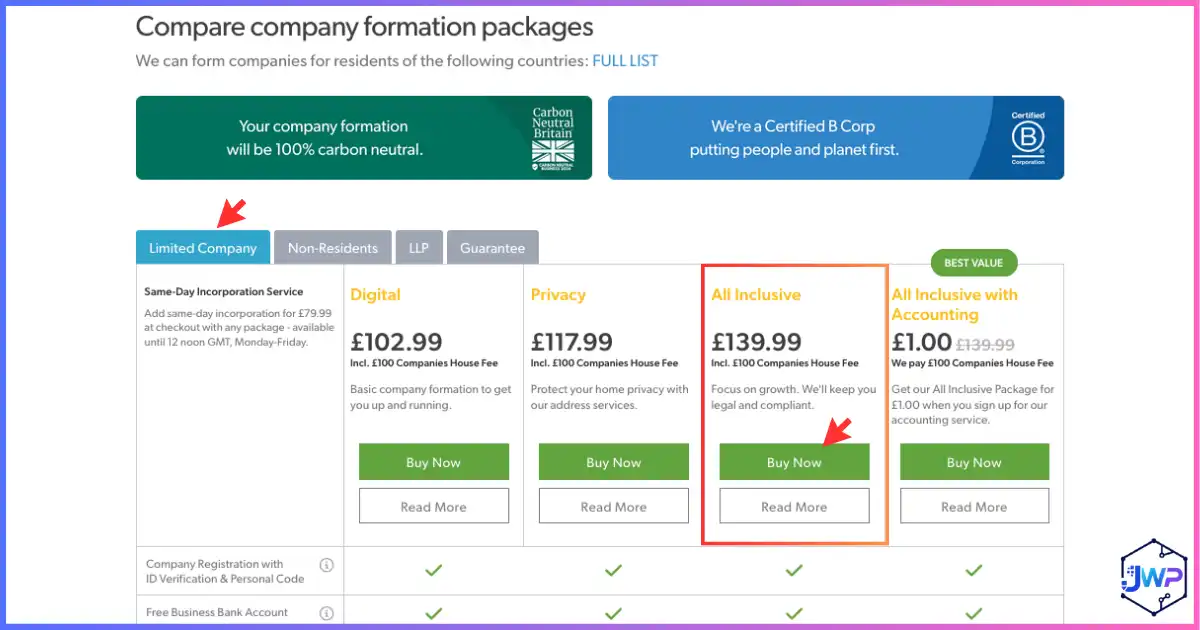
Step 3: Choose a package suitable for a Nigerian resident
Compare the package contents against your information sheet. A Nigeria-based founder without a suitable UK address usually needs a registered office service and may also want a director service address.
Check whether the government filing fee, identity verification, documents and annual renewals are included. Banking introductions and optional business tools should not determine the legal structure.
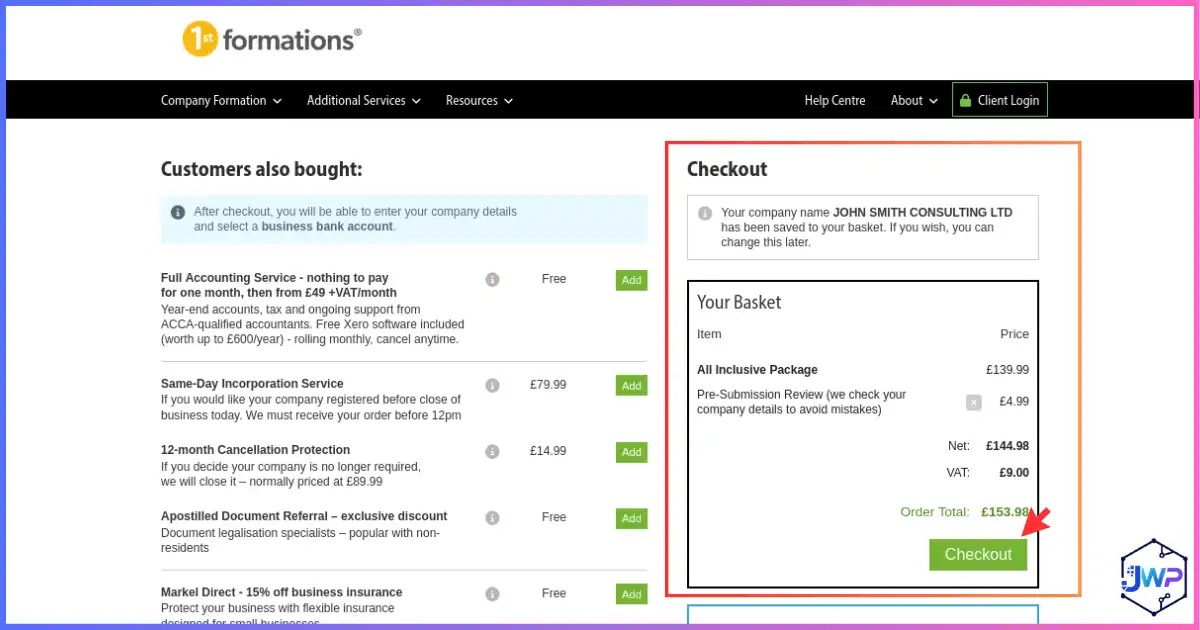
Step 4: Check the checkout total
Review the itemised order. Identify one-time services, recurring subscriptions, taxes and any delivery or forwarding charges. Confirm whether the incorporation filing fee is already part of the total.
Save the order summary for your records. If paying with a Nigerian card, check your issuer’s foreign-transaction fee and the checkout currency.
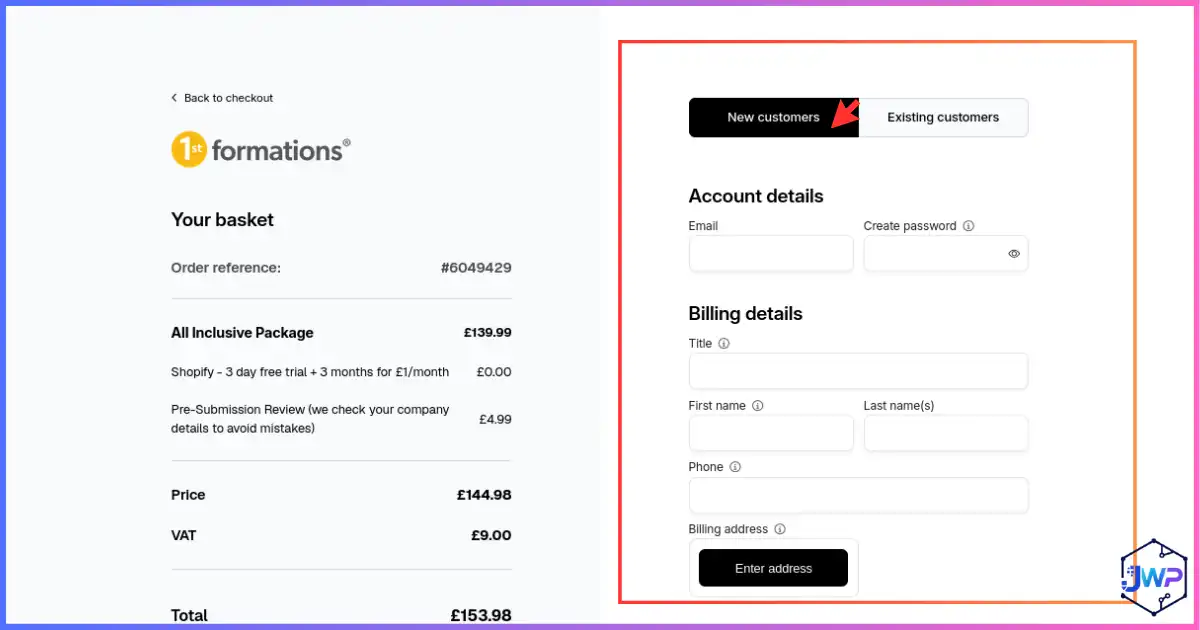
Step 5: Create an account and complete payment
Use an email address you control and will continue to monitor. Choose a unique password and enable stronger account security if available. Your formation account can contain sensitive personal data and statutory documents.
Payment completes the purchase of the service. It does not mean the company is registered. Keep the receipt and monitor any requests for identity or application information.
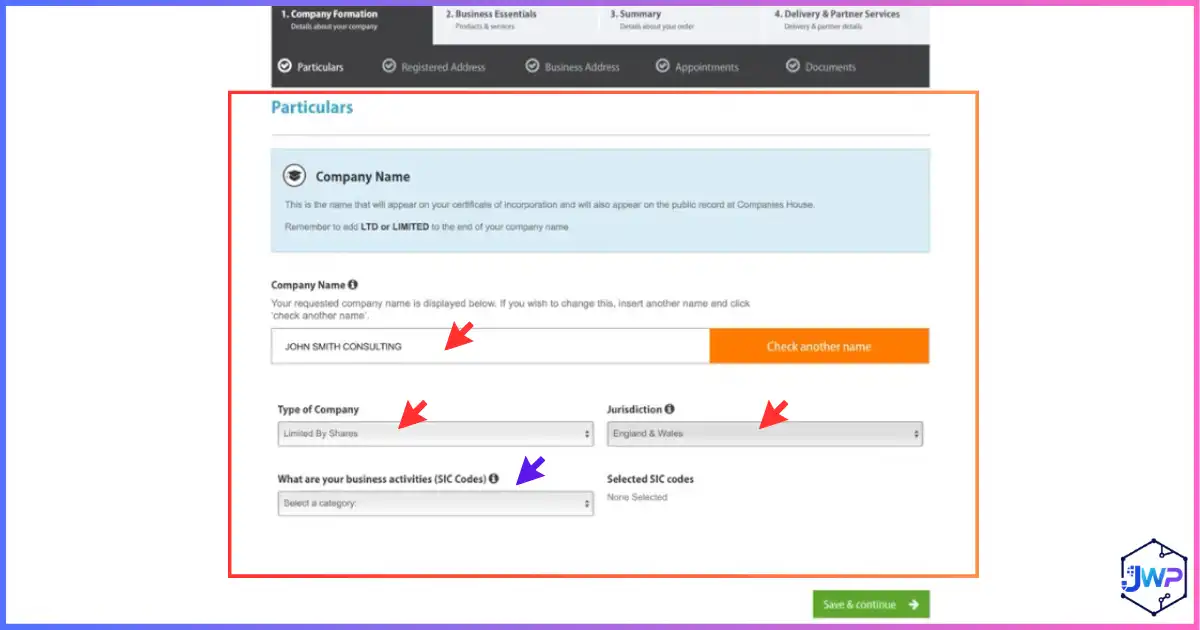
Step 6: Enter company particulars and the SIC code
Enter the company details and select the SIC code that accurately describes the intended business activity. For a company being formed to remain dormant, enter 99999 — Dormant Company.
If the company will trade, choose the appropriate trading code instead. SIC 99999 does not exempt an active business from tax or accounts, and a company with no sales can still have transactions that affect dormancy.
Step 7: Set the registered office and forwarding destination
Choose an appropriate UK registered office in the same jurisdiction as the incorporation. Confirm that you have permission to use the address and that government mail is covered.
Enter the real destination for scans or forwarded mail. A Nigerian forwarding address can differ from the public UK registered office. Confirm how urgent HMRC letters and access codes are delivered.
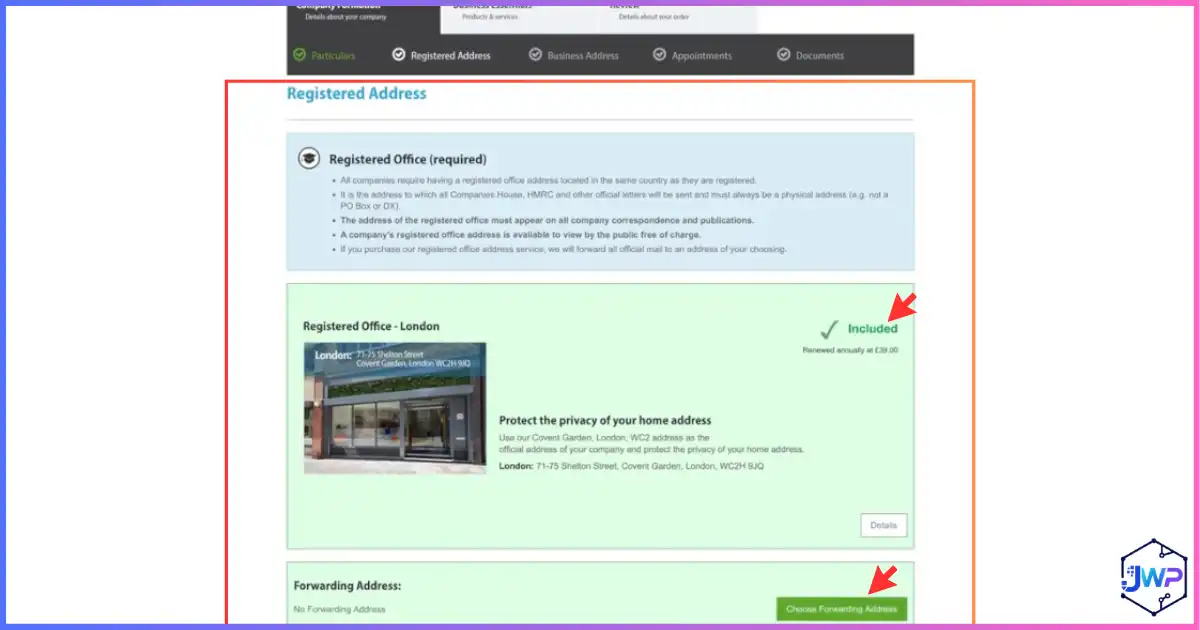
Step 8: Review the business-address service
A business address can be used for agreed commercial correspondence. It may be separate from the registered office and may have a different mail allowance.
Check whether ordinary customer letters, supplier mail and parcels are accepted. Describe your genuine trading location accurately when a bank or regulator asks; a mail service does not establish a staffed UK office.
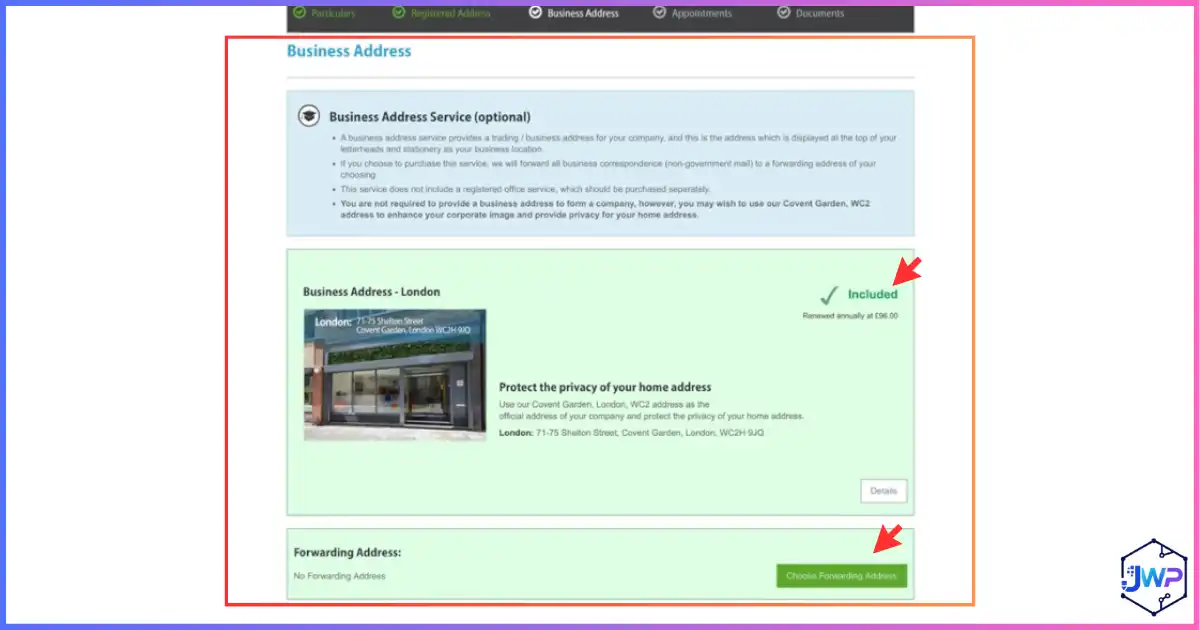
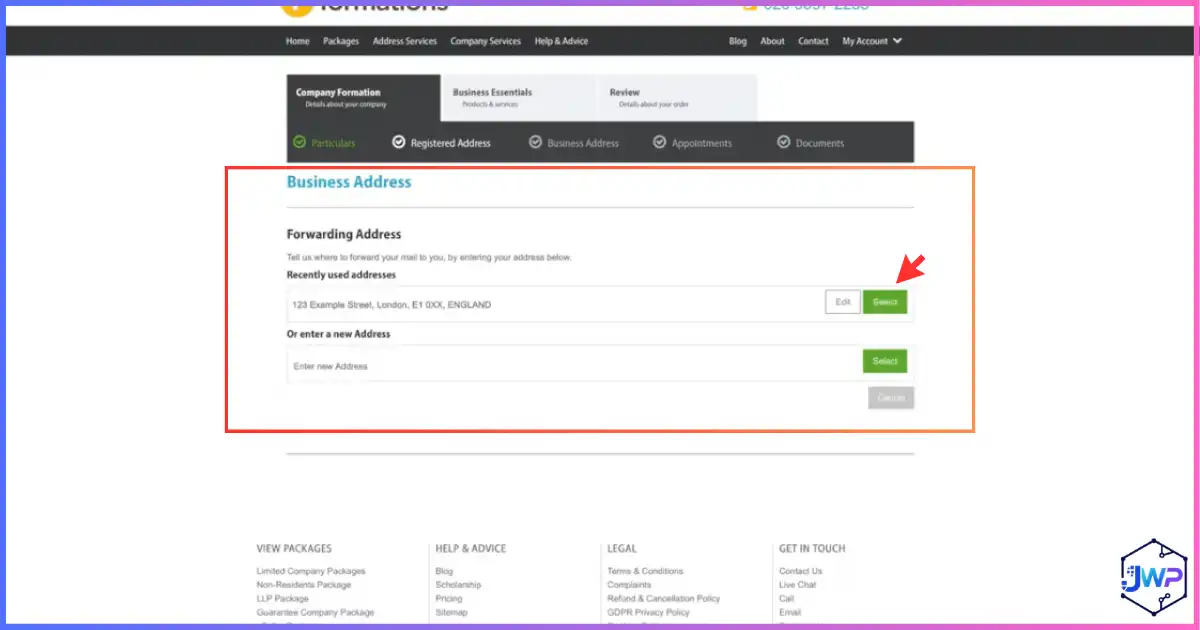
Step 9: Add the business mail-forwarding address
Supply the address where business correspondence should be delivered. Use the correct street, unit, city, region and postal details for your country if physical forwarding is needed.
Compare digital scanning with physical delivery. Ask about postage, customs issues for parcels, minimum forwarding charges and which originals are retained or destroyed.
Step 10: Start the company appointments
Add the people or entities required for the chosen structure. An individual founder can be the sole director, shareholder and PSC, but those are different capacities.
If a Nigerian entity will own the shares, confirm the legal structure with advisers first. Do not enter yourself as personal shareholder just to speed up a form if that is not the intended ownership.
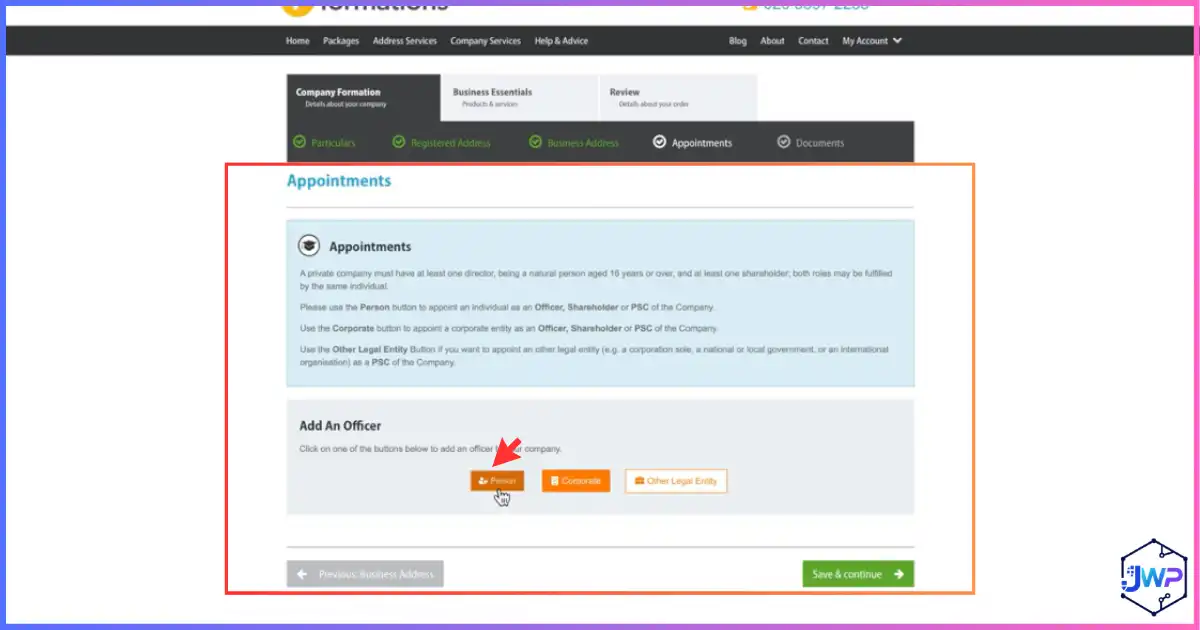
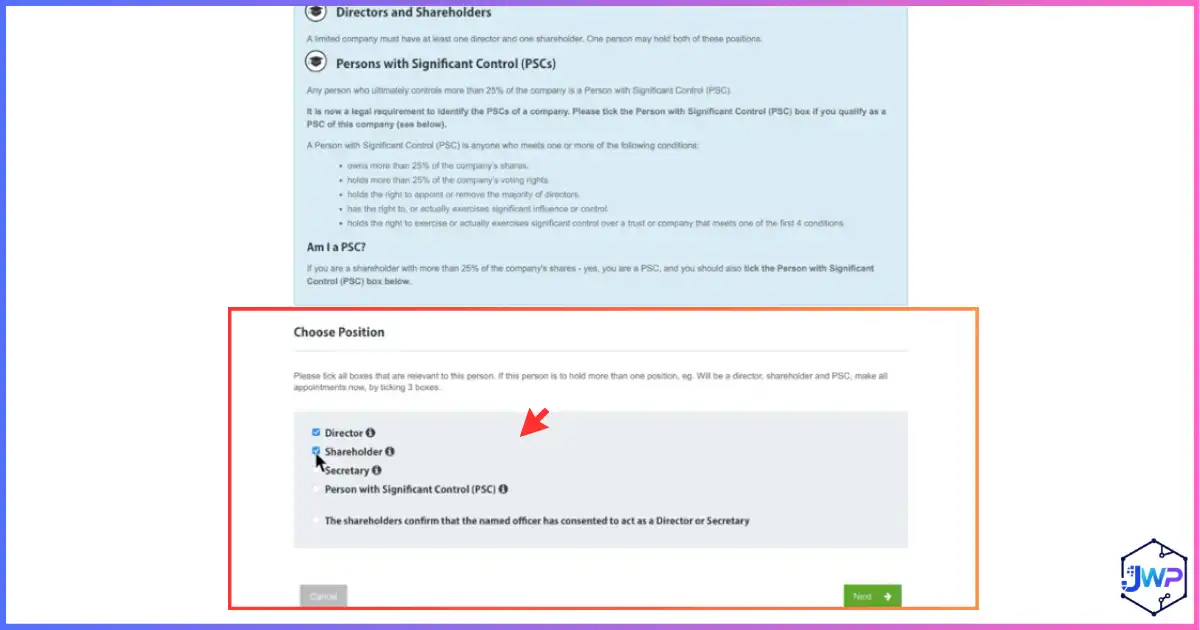
Step 11: Choose each person’s positions
Select the actual roles held by each person. A director manages the company, a shareholder owns shares, and a PSC meets the control conditions. One person can hold all three roles.
A private company secretary is optional. Do not add a nominee or extra officer simply because you live in the Nigeria; overseas residence alone does not require one.
Step 12: Enter officer details accurately
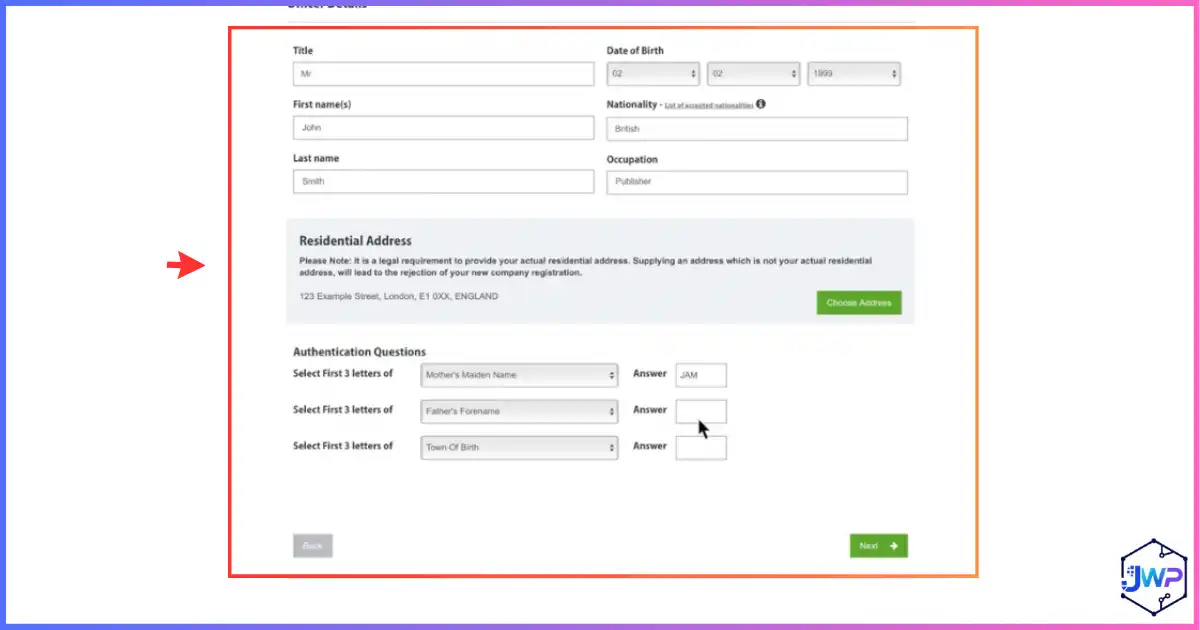
Enter the person’s legal name and requested details as supported by their identity documents. Provide their genuine usual residential address. Avoid initials or name variations that conflict with the identity-verification record.
Complete any current Companies House personal-code fields for directors. If verification is pending, resolve it through the official route or an authorised provider before the filing proceeds.
Step 13: Choose the director’s service address
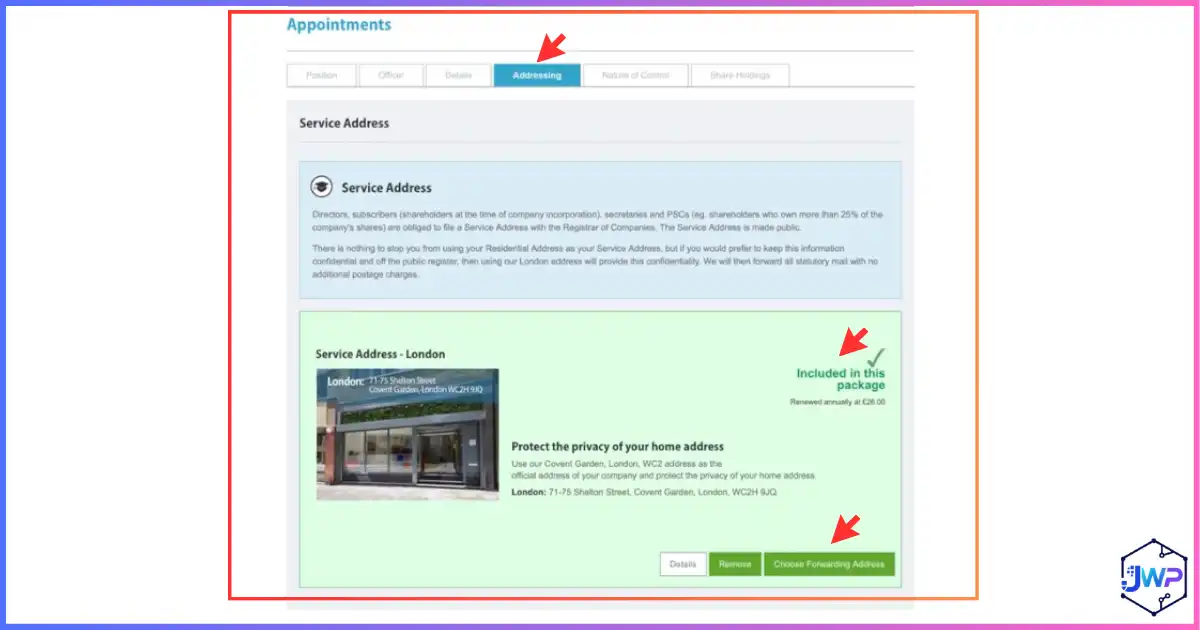
Choose a correspondence address that can reliably reach the director. A permitted provider address can protect the Nigerian home address from appearing as the public service address.
Do not substitute the service address for the actual residential address in a field asking where the director lives. Confirm whether the selected package covers all intended directors.
Step 14: Declare the nature of control
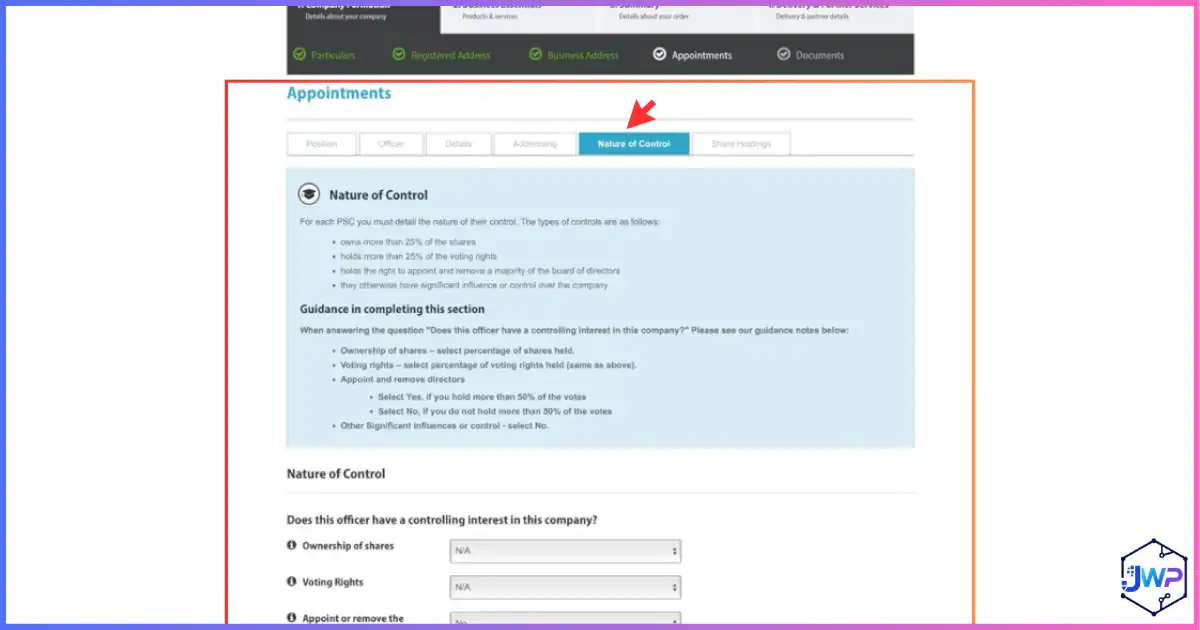
Record the actual PSC conditions and the relevant control band. A sole individual shareholder with all voting shares normally has more than 75% of shares and voting rights.
Where ownership is divided or indirect, assess voting arrangements and board appointment rights as well as percentages. Keep evidence of the analysis and complete the separate PSC identity-verification requirement.
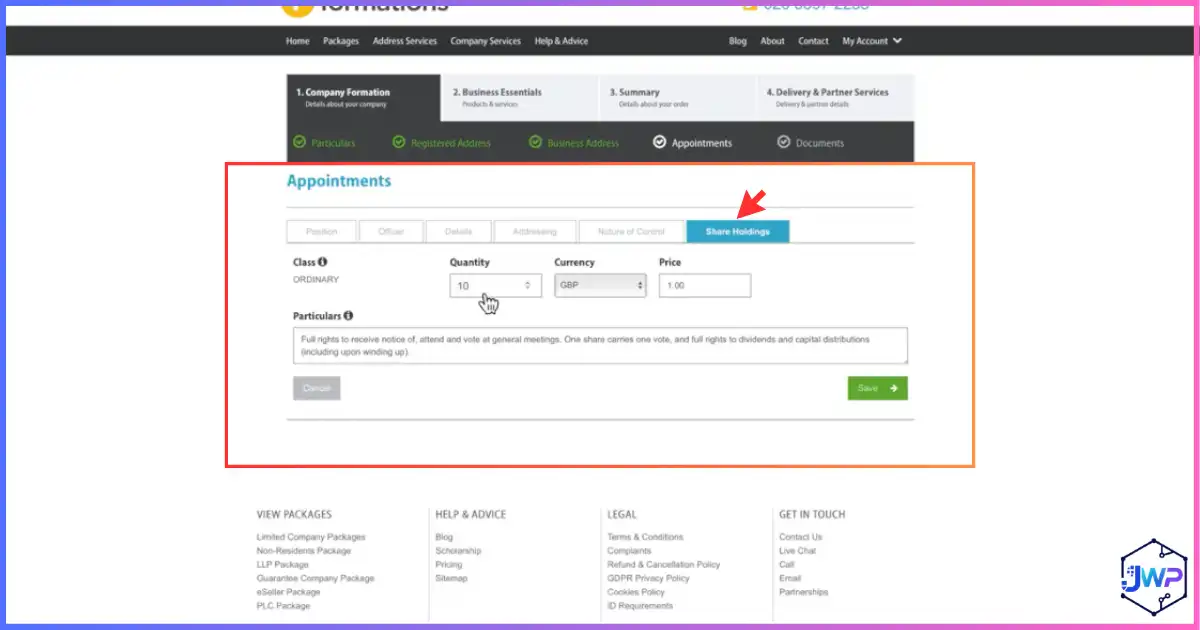
Step 15: Enter shareholdings and capital
Check the shareholder names, share class, number of shares, nominal value and paid or unpaid amounts. The totals should match the agreed ownership and statement of capital.
For example, 100 ordinary £1 shares allocated 60 to one founder and 40 to another create a simple 60/40 allocation if the shares have equal rights. Nominal capital is not the company’s market valuation.
Step 16: Add another person only if needed
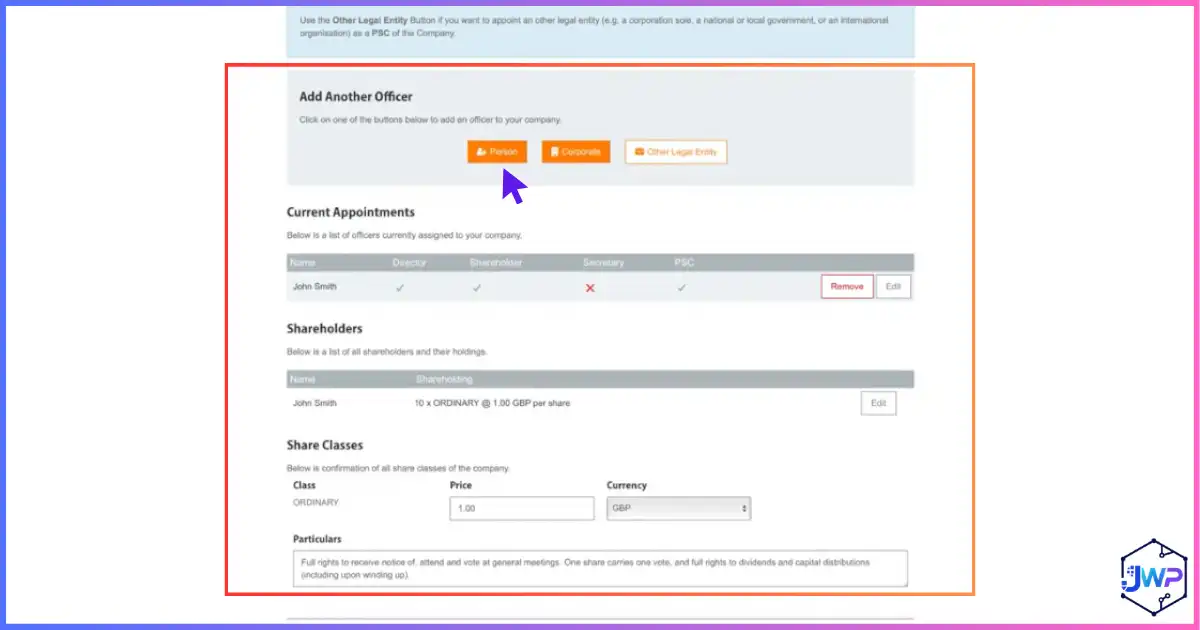
Add any remaining director, shareholder or other relevant participant. Confirm that the individual has agreed to the appointment and supplied their own accurate information.
Collect each additional director’s verified personal code. If the company truly has one owner and one director, there is no need to invent a second person to satisfy an overseas-founder requirement.
Step 17: Review the incorporation documents
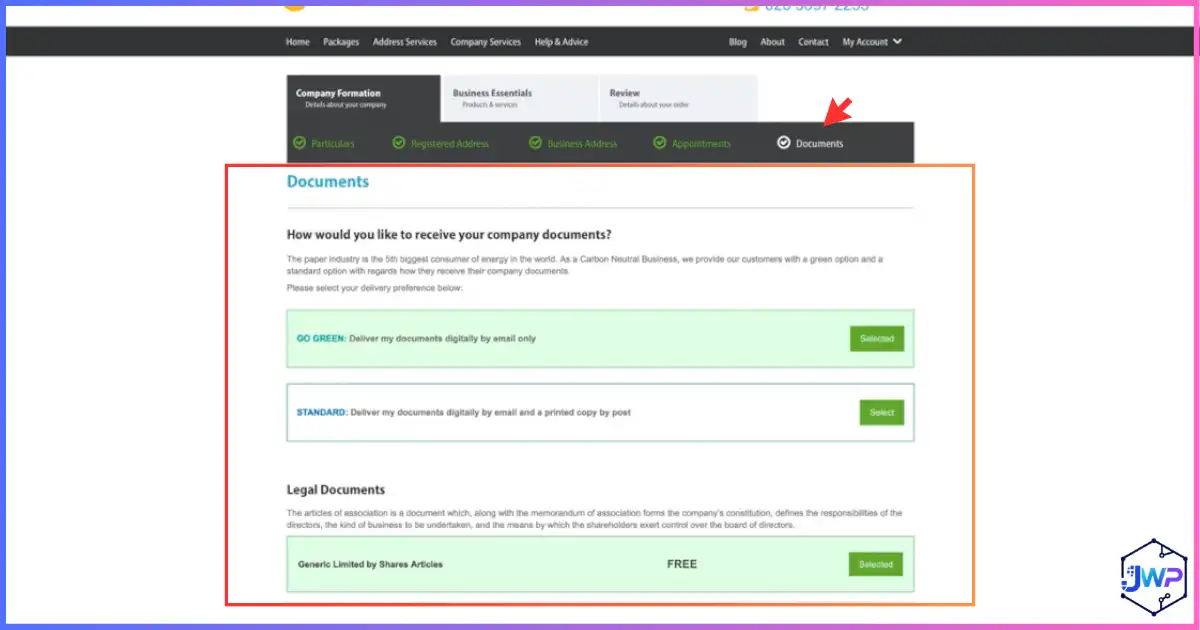
Review the proposed constitutional documents and shareholder information. Standard articles may suit a simple company, but they should not be assumed suitable for every investor, joint venture or multi-class share structure.
Check the memorandum, articles and statement of capital where provided. If anything differs from the ownership plan, resolve it before authorising submission.
Step 18: Evaluate business essentials
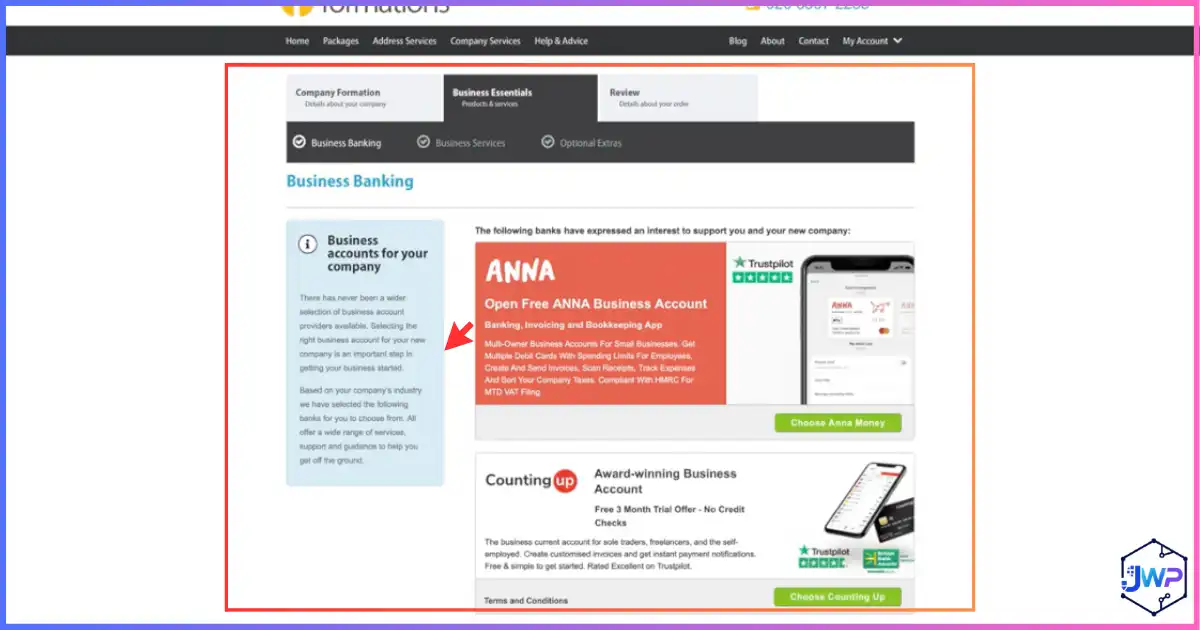
Review any bundled tools, referrals or business services individually. Check whether they are trials, subscriptions or introductions requiring a separate application.
Buy only what the company will use. Bookkeeping, tax software and insurance can be important, but the best choice depends on your activity and advisers rather than their appearance in a checkout flow.
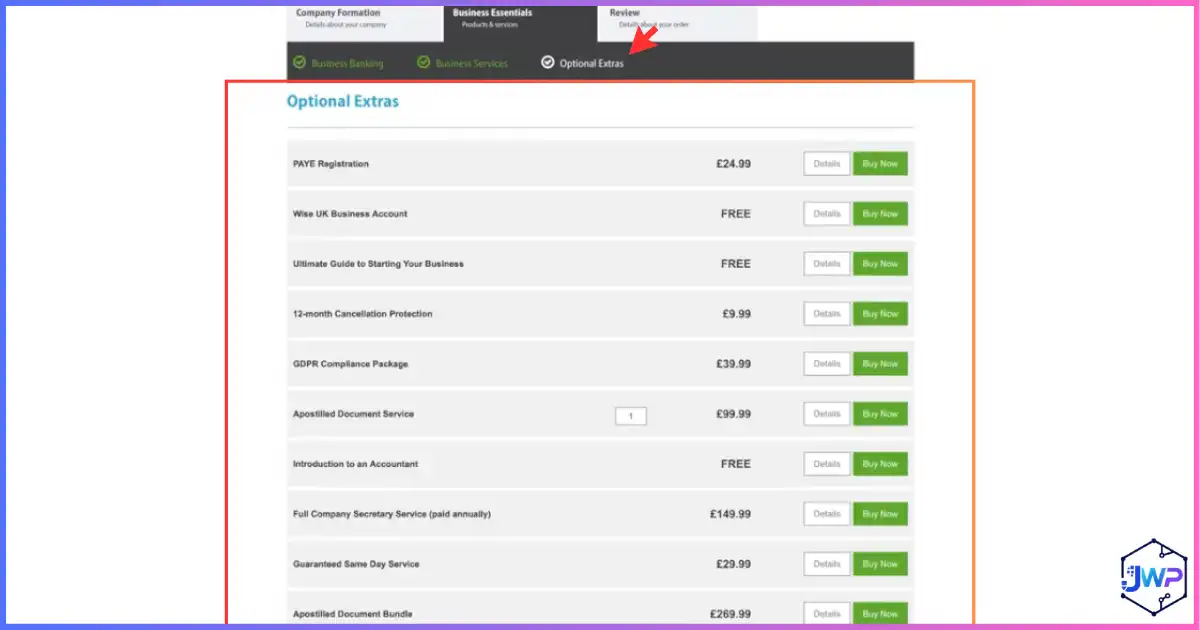
Step 19: Review additional services and remove unnecessary items
Assess extras such as document certification, printed records, mail services or administrative support against actual requirements. A bank or overseas authority may request certified documents, but many applicants can start with digital incorporation records.
Check what is already in your selected package. Avoid paying twice for equivalent address, document or filing services.
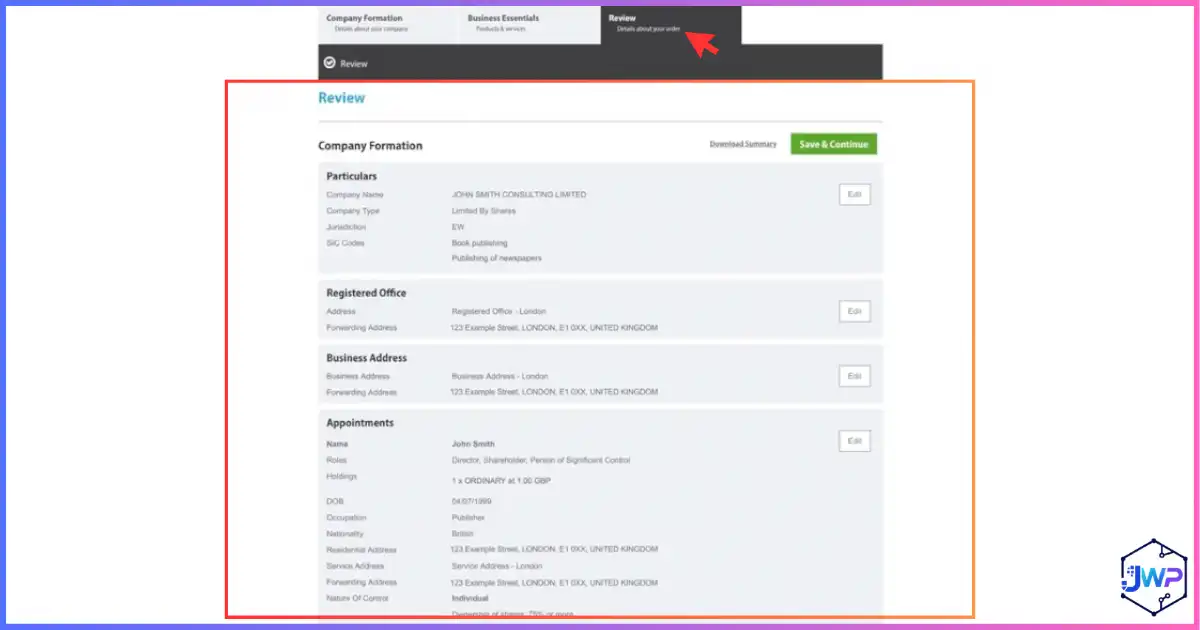
Step 20: Review the complete application
Read the final summary as if you were the bank checking it later. Verify the legal name, jurisdiction, addresses, SIC code, appointments, PSCs, share capital and document choices.
Check the current lawful-purpose declarations and any outstanding identity requests. Correct errors before authorising submission; do not assume the agent will infer what you meant.
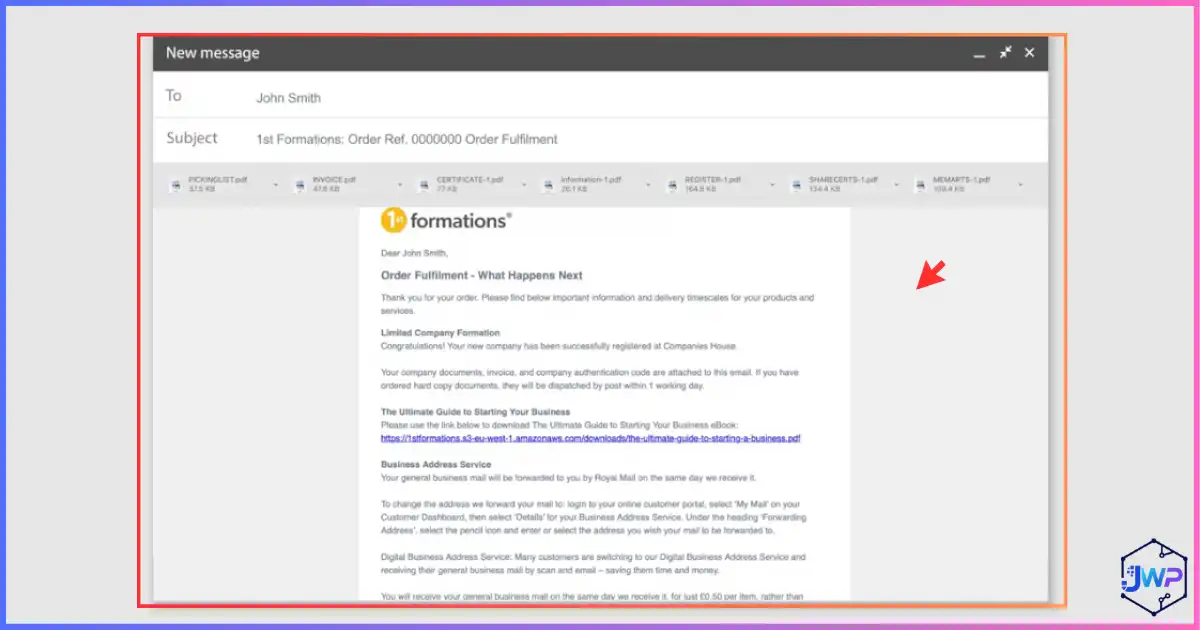
Step 21: Read the email confirmation and await approval
Determine what the email actually confirms: an order, receipt of information, submission to Companies House, or completed incorporation. Respond to outstanding requests and keep watching your inbox.
Once incorporation is approved, obtain the certificate and company number. Verify the public register details and begin the post-formation checklist rather than assuming everything else is finished.
What to Do Immediately After Companies House Approves the Company
Approval creates the legal entity. The next job is to make it usable and keep it compliant. Work through these tasks in a deliberate order rather than applying to every bank or payment processor at once.
- Verify the register. Check the company name, number, registered office, officers, PSC information and SIC code.
- Save the documents. Keep the certificate, articles, memorandum, share records and order receipt together.
- Complete outstanding PSC verification. Check the applicable deadline and confirm that the correct role submission was made.
- Secure filing access. Arrange control of the company’s Companies House filing credentials and monitored email.
- Track HMRC correspondence. Obtain the company’s UTR and follow instructions for Corporation Tax access.
- Decide whether the company is active or dormant. Base the decision on activity and transactions, not only the SIC code.
- Set up bookkeeping and banking. Record funding correctly and separate company money from personal spending.
- Establish the filing calendar. Confirm the actual deadlines recorded for the company.
The company number identifies the legal entity. A UTR identifies the company for UK tax. A VAT number identifies a VAT registration. These numbers are not interchangeable, and incorporation does not automatically provide all of them.
Present the company accurately to customers
Use the legal entity that actually contracts with the customer. Put accurate company details on invoices, contractual documents and the business website as applicable. Make clear whether a payment goes to the UK company or to an existing Nigerian business.
If the UK company buys services from your Nigerian business, document the work, price and payment terms. Common ownership makes clear records more important, not less. Obtain advice about transfer pricing and local registration obligations before intercompany arrangements become routine.
Can a Nigerian Resident Open a UK Business Bank Account?
Possibly, but incorporation does not guarantee acceptance. Each provider decides which entities, owner-residence countries, industries and operating models it supports. A UK company with a Nigeria-based director can be assessed differently from one with a UK-resident management team.
Check eligibility for the combination UK-incorporated company + Nigerian resident beneficial owner + your actual activity. A provider supporting Nigerian customers or UK companies generally does not prove it supports that combination.
Prepare a coherent application file
- Certificate of incorporation, articles and company number.
- Director and beneficial-owner identification and proof of actual residential address.
- Explanation of services or products, customers and expected revenue.
- Website, contracts or invoices showing genuine intended business.
- Source-of-funds evidence and anticipated countries of payment.
- Accurate trading address and the registered-office service agreement if requested.
- Tax-residency information for the company and relevant owners.
| Option | Potential use | Questions to resolve |
|---|---|---|
| UK bank business account | UK payment facilities and bank services | Nonresident directors accepted? UK presence needed? Remote opening possible? |
| Multicurrency business account | GBP receipts, FX conversion and international transfers | This exact company/owner combination supported? Which entity holds funds? |
| Existing Nigerian bank or international bank | A starting discussion with an established relationship | Foreign-company account offered? GBP and account-title requirements? |
| Payment processor | Card collection or marketplace settlement | Actual business location eligible? Required settlement account and verification? |
Read our guides to opening a Wise account and opening a Payoneer account as background, then verify the current provider rules for your entity. Those guides are not promises of UK company eligibility.
For PayPal, review UK PayPal considerations for non-UK residents. Use truthful residence and business details, and proceed only where the provider’s terms support them.
Distinguish deposits from safeguarded balances
A business payment account is not automatically a bank deposit account. Check the regulated entity, safeguarding or deposit-protection arrangements, eligible currencies, account limits and withdrawal process. Assess whether the account is suitable for operating receipts or for holding a substantial reserve.
If an application is declined, identify the issue before trying elsewhere. Country support, industry restrictions, inconsistent addresses and weak business evidence need different solutions. Keep enough working capital outside an application that may take time to approve.
UK Corporation Tax, VAT and Payroll for a Nigerian-Owned Company
Where the company is tax resident
A UK-incorporated company is generally UK tax resident under the incorporation rule. A treaty can affect the position in specific circumstances; having an overseas director does not itself switch UK tax off. The company’s residence is distinct from the owner’s residence. [12]
For a UK-resident company, foreign customers and a foreign bank account do not automatically exclude profits from UK Corporation Tax. If management, staff or operations are in the Nigeria, review Nigerian business and tax obligations as well.
Corporation Tax rates
The main rate is 25%. The small-profits rate is 19% for qualifying companies with profits of £50,000 or less, with marginal relief potentially available between £50,000 and £250,000. These thresholds are reduced for short accounting periods and associated companies. Eligibility restrictions also apply. [13]
These percentages apply to taxable profits, not gross revenue. Book profit and taxable profit can differ because of allowances, adjustments and disallowed expenses. Have your accountant calculate the actual liability rather than reserving a percentage of every receipt mechanically.
Tell HMRC when business activity starts
An active company within the charge to Corporation Tax must tell HMRC within three months of starting its tax accounting period. The activity assessment is broader than receiving the first customer payment. [14]
The HMRC online Company Tax Return service closed on March 31, 2026. Plan for commercial software or an accountant to file the return, computations and accounts in the required electronic format. [15]
VAT: the £90,000 threshold is not a universal exemption
For businesses to which the normal UK registration threshold applies, registration is triggered when taxable turnover exceeds £90,000 over the previous 12 months, or is expected to exceed £90,000 in the next 30 days. Taxable turnover includes zero-rated sales and differs from profit. [16]
A non-established taxable person can have a registration requirement for taxable UK supplies without that turnover threshold. HMRC says a registered, serviced or virtual office alone is not enough to create a business establishment. [17]
Check the actual establishment and place-of-supply rules for your activity. Selling services to businesses, digital services to consumers and goods held in UK fulfilment facilities can lead to different results. A Nigerian owner should not assume either automatic VAT registration or automatic exemption.
Payroll and hiring
Director pay, UK staff and overseas workers need a location-specific review. Payroll withholding, social-security contributions and employment obligations can arise where the work is performed. A UK PAYE arrangement does not, by itself, resolve Nigerian payroll obligations for someone working in the Nigeria.
Before hiring, identify the employing entity and work location. Include employment contracts, employer obligations and insurance in the operating plan rather than treating them as formation-package extras.
Nigeria Tax, Offshore Ownership and Funding
The UK filing is only one part of the structure. For someone operating from Nigeria, the practical priorities are the 2026 Nigerian tax reforms, truthful financial-provider applications, and funding in sterling from naira. Get advice before moving substantial funds or attributing income to the new company.
Nigerian residence and overseas income
The Nigeria Tax Act 2025 provides that a resident individual’s income, gains or profits are taxable wherever they arise, whether or not brought into Nigeria. UK incorporation is therefore not a general way to move your personal income outside Nigerian taxation. The Act also contains controlled-foreign-company provisions for a foreign company controlled by a Nigerian company; personal and corporate ownership require different analysis. [34]
Have an adviser apply the current law to the owner, distributions, local services and any Nigerian company that holds the UK shares. Do not rely on an older tutorial quoting rules from before the 2026 reform period.
Funding the company from Nigeria
The Central Bank of Nigeria launched the fourth edition of its Foreign Exchange Manual in May 2026. Check the current banking process rather than assuming a formation payment and a capital investment use identical documentation. [35]
Ask your authorised bank which documents it needs for the actual purpose: paying a formation invoice, subscribing for shares or lending money to the company. Confirm card eligibility, sterling conversion, transfer fees and proof-of-funds requirements before placing an order.
Using the UK–Nigeria tax treaty correctly
HMRC publishes the UK–Nigeria treaty documents and their status. Read the applicable convention and subsequent modifications when planning residence, income allocation or double-tax relief. A treaty is not a universal exemption and does not cancel every domestic filing requirement. [36]
Start your local review with Nigeria Tax Act 2025 — NIPC official copy, then have an adviser apply the rules to the proposed structure.
Prepare a written ownership and funds-flow plan
Draw the relationships between you, any existing local business and the UK company. For each planned payment, identify its purpose, currency, payer, recipient and documents. A share subscription, shareholder loan, service invoice and dividend should not share one vague description.
Ask the local adviser to confirm which tax registrations and information returns apply, whether overseas ownership must be disclosed, and whether local staff or management create company obligations. Ask the UK accountant to check the same transactions from the UK side.
Do not assume the tax paid by one legal person is automatically creditable by another. The UK company’s Corporation Tax and the owner’s personal tax concern different taxpayers; relief needs the appropriate rule and evidence.
Record the activity where it really happens
A remote business may serve British customers while its founder works from Lagos, Abuja or Port Harcourt. Record those facts honestly in contracts, tax-residence forms and banking applications. Nominal addresses or paper meeting locations should not contradict the real management arrangements.
Keep a log of major decisions and approvals, and store the underlying contracts and invoices. The purpose is a reliable record of operations, not manufacturing an overseas presence.
Questions to put to both advisers
- Who should legally own the shares, and why?
- Where is the company resident under each domestic rule and the relevant treaty?
- Does local work create a permanent establishment, registration or payroll obligation?
- Can retained profits create owner-level or controlled-company taxation?
- How are capital, loans, fees, dividends and gains reported?
- Which currency conversion and recordkeeping rules apply?
- What is the annual compliance cost before and after trading begins?
Obtain a written filing calendar, including the formation year. A statement that the company is dormant or unprofitable does not answer all the home-country questions.
How to Pay Yourself from a UK Limited Company
The company’s funds belong to the company. Record every payment to an owner by its legal and accounting purpose, rather than using the business account like a personal wallet.
| Payment | What it represents | Points to review |
|---|---|---|
| Salary or director remuneration | Payment for work or office held | UK and Nigerian payroll, income tax and social-security treatment |
| Dividend | Distribution to shareholders out of available profits | Profit support, approvals, dividend records and personal tax |
| Expense reimbursement | Repayment of substantiated business costs | Receipts, business purpose and bookkeeping |
| Loan repayment | Return of a documented amount lent to the company | Loan balance, terms and any interest treatment |
| Director’s loan | Amount borrowed from the company | Recordkeeping, repayment and possible tax consequences |
Dividends cannot exceed available profits. Record the approval and dividend documentation, including where the director and shareholder are the same person. Money taken out that is neither salary, dividend nor a valid repayment can be a director’s loan. [27]
A dividend is not a business expense for calculating Corporation Tax. Personal taxation in Nigeria, foreign-income rules and any relief also need review. Ask for an owner-payment policy that fits both tax systems before making regular withdrawals.
Choose a currency and transfer schedule that avoids repeated unnecessary conversion. Keep the gross payment, fees, conversion rate and final amount received in your records so both advisers can reconcile them.
How to Set Up a Dormant UK Company from Nigeria
A dormant company can be useful for reserving a legal entity before launch. It is still a company with filing responsibilities. “No sales,” “no profit” and “dormant” are not interchangeable descriptions.
Companies House dormancy
For Companies House, a company is dormant if it has no significant accounting transactions during the financial year. Certain transactions are excluded, including payment for subscriber shares on formation, filing fees paid to Companies House and late-accounts penalties. Ordinary bank charges or business payments can affect dormancy. [28]
HMRC dormancy is a separate assessment
Corporation Tax dormancy focuses on activity within the charge to tax. Tell HMRC about the correct status and respond to any notice to file. Do not ignore a return request because you believe the company is dormant; have the notice withdrawn where appropriate or comply with it.
Use SIC code 99999 correctly
Companies House lists 99999 as the SIC code for a dormant company. Choose it in step 6 if that is the genuine intended status. When the business starts operating, update the activity information appropriately and tell HMRC about the change. [29]
For a deeper operational guide, see how to set up a dormant UK company.
| Question | Dormant company answer |
|---|---|
| Must it file annual accounts? | Yes; dormant accounts may be appropriate if eligible |
| Must it file a confirmation statement? | Yes, even without trading |
| Does it still need a registered office? | Yes; keep the address and email arrangements active |
| Does SIC 99999 guarantee tax exemption? | No; real activity and transactions determine the position |
| Can it start trading later? | Yes; update the relevant registrations and accounting treatment |
| Are Nigerian owner filings automatically waived? | No; Nigerian reporting requires a separate assessment |
Before opening an account or paying recurring services from company funds, ask how those transactions affect the proposed dormant accounts. A zero account balance is not proof that the company had no accounting transactions during the year.
Your UK and Nigerian Compliance Calendar
Build reminders from the company’s actual recorded dates. Your home-country filing periods and the UK company’s financial year can differ, so your two advisers may need separate reconciliations.
| Task | Normal timing | Important distinction |
|---|---|---|
| New director verification | Before the relevant new-company registration filing | Collect each director’s personal code |
| New PSC verification details | At registration of the PSC or within 14 days of being added | Separate from director-role code provision |
| Active-company HMRC notification | Within three months of the tax accounting period starting | Dormant and active companies differ |
| Confirmation statement | At least annually; file within 14 days after review period ends | Separate from accounts and tax returns |
| First Companies House accounts | Normally 21 months after incorporation | Check the company’s exact due date |
| Subsequent private-company accounts | Normally nine months after financial year end | Separate from the tax payment date |
| Corporation Tax payment | Normally nine months and one day after the tax accounting period ends | Large-company instalment rules can differ |
| Company Tax Return | Normally 12 months after the tax accounting period ends | Payment is usually due earlier |
| Home-country returns and ownership reporting | According to the applicable local filing and extension rules | Obtain a written form-by-form calendar |
| Address and support renewals | According to each service agreement | Keep a valid payment method and notice email |
UK accounts and Corporation Tax deadlines follow separate rules. [30] The confirmation statement verifies register information; it is not a financial return. [31]
Four checkpoints around a standard UK year-end
Sequence diagram, not a scale drawing. First accounts and large-company payment rules can differ. Source: GOV.UK accounts and tax-return deadlines. [30]
First statutory accounts can span more than 12 months, while a Corporation Tax accounting period cannot. That can require two first-year Company Tax Returns. [32]
Keep accounting records for the relevant statutory retention period. GOV.UK’s company guidance normally specifies six years from the end of the financial year they relate to, with situations requiring longer retention. [33] Store bank statements, invoices, expenses, funding records and owner-payment documentation together.
Practical Examples for Nigerian Founders
1. A lagos software agency entering a uk customer contract
The founder first checks whether the customer actually needs a UK contracting entity. If the existing local business can perform the contract directly, a second company may add unnecessary costs. If a UK entity has a commercial role, the ownership plan is settled before filing.
The application accurately describes the director’s residence and business location. The advisers review the 2026 Nigerian tax reforms, truthful financial-provider applications, and funding in sterling from naira. The company prepares contracts and accounting records that explain which entity performs the work and receives the income.
2. A product seller planning UK stock
A seller based in Nigeria wants to use British fulfilment. They review who imports and owns the goods, who makes the sales and what VAT and customs obligations arise. The company is not treated as ready to sell simply because the formation certificate is available.
The seller confirms banking support for the actual ownership and country combination. They budget separately for initial stock, returns, payment fees and annual accounting rather than treating a registration package as the whole launch cost.
3. A dormant company before launch
A founder chooses SIC 99999 to establish an entity before starting activity. They maintain the registered office, monitor mail and calendar the accounts and confirmation statement. They also obtain local advice on ownership, funding and any home-country declarations.
When launch approaches, they review transactions and notify HMRC of active status where required. They update business activity and organise full bookkeeping before the company begins invoicing or buying stock.
4. A local parent considering a UK subsidiary
An established business in Nigeria considers owning the UK company directly. It documents the commercial role of the subsidiary and the intended capital, loans and service agreements. The shareholders are entered according to that plan rather than registering personally and hoping to transfer the company later.
Both advisers review related-party pricing, distributions, reporting and closure consequences. The parent retains the incorporation records and a clear authority process for the UK director to enter contracts.
Common Mistakes and Troubleshooting
| Issue | Why it matters | Practical response |
|---|---|---|
| Assuming foreign registration eliminates local tax | Residence, income source and ownership rules remain relevant | Review the UK and Nigeria positions together |
| Using a UK mail address as physical trading premises | Can conflict with actual operations and onboarding rules | Describe the real work and management location |
| Using SIC 99999 while trading | The code does not override activity or transactions | Choose an accurate code and review active status |
| Missing identity or PSC verification | Director and PSC roles have separate requirements | Confirm both submissions and their deadlines |
| Bank declines the application | Formation is separate from banking eligibility | Check residence support, industry and document consistency |
| Sending funding with the wrong description | Capital, loans and services have different treatment | Match bank evidence, approvals and bookkeeping |
| Ignoring a tax notice because there is no profit | A filing obligation can remain without tax due | Respond or arrange a valid withdrawal of the notice |
| Letting the UK address service lapse | Official mail may no longer reach the company | Track renewals and update any changed address |
| Abandoning an unused company | Accounts, register and tax obligations can continue | Plan a lawful closure and complete final obligations |
If registration stalls
Determine whether the problem is a name query, inconsistent personal details, an incomplete verified-identity step or missing application information. Correct the issue through the provider or the relevant official service before making duplicate orders.
If the company is no longer needed
Ask both advisers about closure, outstanding creditors, assets, bank accounts, final returns and owner reporting. A strike-off service may handle one administrative filing without covering every tax consequence. Keep records after closure for the required period.
Complete Formation and Launch Checklist
Before payment and submission
- Confirm why a UK entity is commercially useful.
- Choose the legal owner and obtain cross-border structural advice.
- Check the company name and relevant brand rights.
- Arrange an appropriate registered office and monitored email.
- Verify each director’s identity and collect personal codes securely.
- Identify shareholders, PSCs, share rights and capital.
- Choose a real activity code or SIC 99999 for intended dormancy.
- Compare package totals, included filing fees and renewal terms.
- Check banking eligibility before relying on a specific account.
After incorporation
- Verify the register and save the incorporation documents.
- Complete separate PSC verification details where required.
- Secure filing access and official-mail delivery.
- Review HMRC registration or dormant status.
- Record capital and loans accurately.
- Apply for eligible banking and payment services using truthful details.
- Set up bookkeeping and UK filing reminders.
- Confirm the Nigeria reporting and funding obligations.
- Review VAT, payroll and local registration before trading.
- Document a compliant owner-payment policy.
FAQs: How to Form a UK Limited Company from Nigeria
Can someone in Nigeria own 100% of a UK limited company?
Yes. A founder living in Nigeria can be the sole shareholder and director of a UK private company, subject to eligibility rules. A UK co-owner is not generally required because you live abroad. Review home-country tax and operating obligations separately.
Do I have to travel to the UK to register?
Generally, no. UK online formation can be completed from Nigeria with the required information and identity verification. Financial providers have separate onboarding rules and may ask for additional evidence.
Do I need a UK-resident director?
No. Directors do not have to live in the UK. The company still needs an appropriate registered office in its UK incorporation jurisdiction.
Can I use my home address in Nigeria as the registered office?
No. The registered office must be in the UK and match the incorporation jurisdiction. Give your genuine home address in the residential-address field, and choose a separate permitted service address for public correspondence if needed.
What are the Companies House fees in 2026?
Digital incorporation costs £100 and paper incorporation costs £124 from February 1, 2026. The digital confirmation statement fee is £50 per 12-month payment period. Address services and agent charges may be additional.
How long does formation take?
GOV.UK says online registration usually takes 24 hours. This is not a guaranteed timeline for the whole setup. Identity checks, name queries, missing information and banking can extend the process.
When should I use SIC code 99999?
Use 99999 for a company intended to remain dormant. If the company will trade, use the relevant activity code. The code does not create a tax exemption or remove accounts and confirmation-statement obligations.
Can one person be the director, shareholder and PSC?
Yes, for a straightforward sole-owner company. The roles are different, and director and PSC identity-verification details must be provided through the applicable separate processes.
Will a UK company guarantee banking for a resident of Nigeria?
No. Confirm the provider supports a UK company with your actual owner-residence country and business activity. Incorporation, a registered office and a banking introduction do not guarantee account approval.
Can I use Wise, Payoneer or PayPal for this company?
Only if the provider’s current rules support the exact entity, owner-residence and activity combination. Check the account type, eligibility and verification requirements directly. General country support does not prove support for every foreign company.
Do Nigeria’s 2026 tax reforms affect a UK company owner?
They can. Review the Nigeria Tax Act 2025 for the owner’s residence, foreign income, corporate ownership and any Nigerian operations. A UK registration or overseas account is not a blanket exemption from Nigerian taxation.
Can the UK company remove my tax duties in Nigeria?
Not automatically. Assess personal residence, company residence, source of income, ownership and actual local operations. UK incorporation and overseas receipts do not by themselves settle Nigeria tax obligations.
Does a dormant company still need annual filings?
Yes. Eligible dormant accounts and a confirmation statement still need to be filed, and address and email arrangements must stay active. HMRC and home-country obligations require separate assessment.
Do I need UK VAT registration immediately?
It depends on establishment and taxable supplies. The normal £90,000 threshold is not available to every non-established business. A registered office alone does not create a UK business establishment for VAT purposes.
Can my existing local company own the UK shares?
Corporate ownership can be possible, but decide the structure before filing. Review shareholder information, control disclosure, funding, related-party transactions and tax reporting with advisers in both jurisdictions.
Can I pay myself dividends from the UK company?
Dividends need available distributable profits and the appropriate approvals and records. Assess personal tax and any foreign-company rules locally. Salary, expenses and loan repayments have different treatment.
Does UK company ownership give me a visa?
No. Ownership does not grant UK residence permission or work rights. Follow the appropriate immigration route separately if relocation is intended.
How do I close an unused UK company?
Use the appropriate lawful closure process after reviewing creditors, assets, bank accounts, final accounts and tax returns. Confirm home-country consequences as well; simply stopping activity does not complete closure obligations.
Your Next Steps: Form the Company with a Complete Operating Plan
Learning how to form a UK limited company from Nigeria starts with an accessible online process. Making the structure work requires a clear business purpose, verified identities, appropriate addresses, accurate ownership records and a plan for both countries’ obligations.
Prepare the information sheet, obtain UK and Nigerian advice on the proposed structure, and compare formation routes against the real service requirements. Once approved, turn the certificate into a functioning business with banking, bookkeeping and a reliable compliance calendar.
Sources & Research Notes
Research checked October 8, 2026. UK sources support formation and statutory compliance. Country-specific sources below support local tax, residence or funding considerations. Editorial planning examples are not individual tax rulings. Formation screenshots were supplied for the article; the affiliate URL was not crawled or inspected.
- Companies House fees — Digital and paper incorporation and confirmation-statement fees; effective February 1, 2026.
- GOV.UK: Appoint directors and a company secretary — Director eligibility, overseas residence and optional company secretary.
- GOV.UK: Register your company — Direct registration cost, normal processing guidance and incorporation certificate.
- Companies House: Incorporated companies, April–June 2026 — Published July 30, 2026; monthly incorporations and end-June register size. Counts include company types beyond private Ltds.
- GOV.UK: Being a company director — Continuing director responsibilities.
- GOV.UK: Choose a company name — Naming restrictions, permissions and trademark distinction.
- GOV.UK: When you need to verify your identity — Director personal codes and separate PSC role requirements.
- GOV.UK: Verify your identity for Companies House — Official verification methods, accepted documents and ACSP alternative.
- GOV.UK: People with significant control — Shareholding, voting and other control conditions.
- GOV.UK: Registered office and email addresses — Appropriate physical address, jurisdiction and monitored email.
- HMRC: Company residence overview — Incorporation, management and treaty-residence considerations.
- GOV.UK: Corporation Tax rates — Main and small-profits rates, marginal relief and threshold adjustments.
- HMRC: Corporation Tax trading and non-trading — Activity status and notification within three months.
- HMRC: Company Tax Return obligations — Commercial software and electronic format after the March 2026 service closure.
- GOV.UK: When to register for VAT — Normal threshold and overseas-business registration considerations.
- HMRC: VAT Notice 700/1 — Non-established taxable persons and why a virtual office alone is insufficient.
- GOV.UK: Taking money out of a limited company — Salary, dividend support and director-loan distinctions.
- GOV.UK: Dormant for Companies House — Significant transactions and exclusions.
- Companies House: SIC codes — 99999 for a dormant company; SIC is an activity classification.
- GOV.UK: Accounts and tax returns overview — Standard accounts, tax payment and tax-return deadlines.
- GOV.UK: Filing your confirmation statement — Review periods, submission timing and payment periods.
- GOV.UK: First accounts and Company Tax Return — First-year accounts and possible two-return requirement.
- GOV.UK: Company and accounting records — Records and usual six-year accounting retention guidance.
- Nigeria Tax Act 2025 — NIPC official copy — Resident income and controlled foreign company provisions; check the complete current application.
- Central Bank of Nigeria: Reforms and initiatives — May 2026 launch of the fourth Foreign Exchange Manual; current operational guidance should be checked with the bank.
- HMRC: Nigeria tax treaties — Official treaty text and status; a signed agreement must be in force and applicable before relief is assumed.
Official incorporation statistics cover all company types. The £1,000 reserve chart is an original illustration, not a price quote or a sufficient-budget recommendation. Banking eligibility, individual relief and local filings depend on the facts. This article covers a UK private company limited by shares.